
What if your most carefully crafted professional advice became the very thing that threatened your life’s work? It’s a heavy thought, and you’re likely here because the fine print of your current policy feels more like a barrier than a safety net. You’ve probably felt the frustration of trying to get a straight answer from a chatbot while worrying if a simple oversight could bankrupt your business. Understanding what is professional indemnity insurance australia wide shouldn’t require a law degree, yet the industry often hides behind dense jargon.
We’re here to change that by providing a clear, human-led breakdown of how to shield your reputation and assets in 2026. We’ll explore your specific legal obligations, including the July 1, 2026, requirements for NSW building practitioners, and how to identify the hidden risks that automated platforms often overlook. By the end of this guide, you’ll have the clarity needed to protect your future with absolute confidence.
Key Takeaways
- Gain a clear, jargon-free understanding of what is professional indemnity insurance australia wide and how it serves as a protective shield for your professional reputation.
- Discover the technical mechanics of “claims-made” triggers to ensure your business remains secure against allegations arising from work performed years ago.
- Recognise why a personalised, consultative risk assessment provides far greater security than the “tick and flick” approach of automated insurance platforms.
- Stay ahead of 2026 regulatory changes and professional standards to ensure your policy meets every legal obligation while providing genuine peace of mind.
The Foundation: Defining Professional Indemnity in the Australian Market
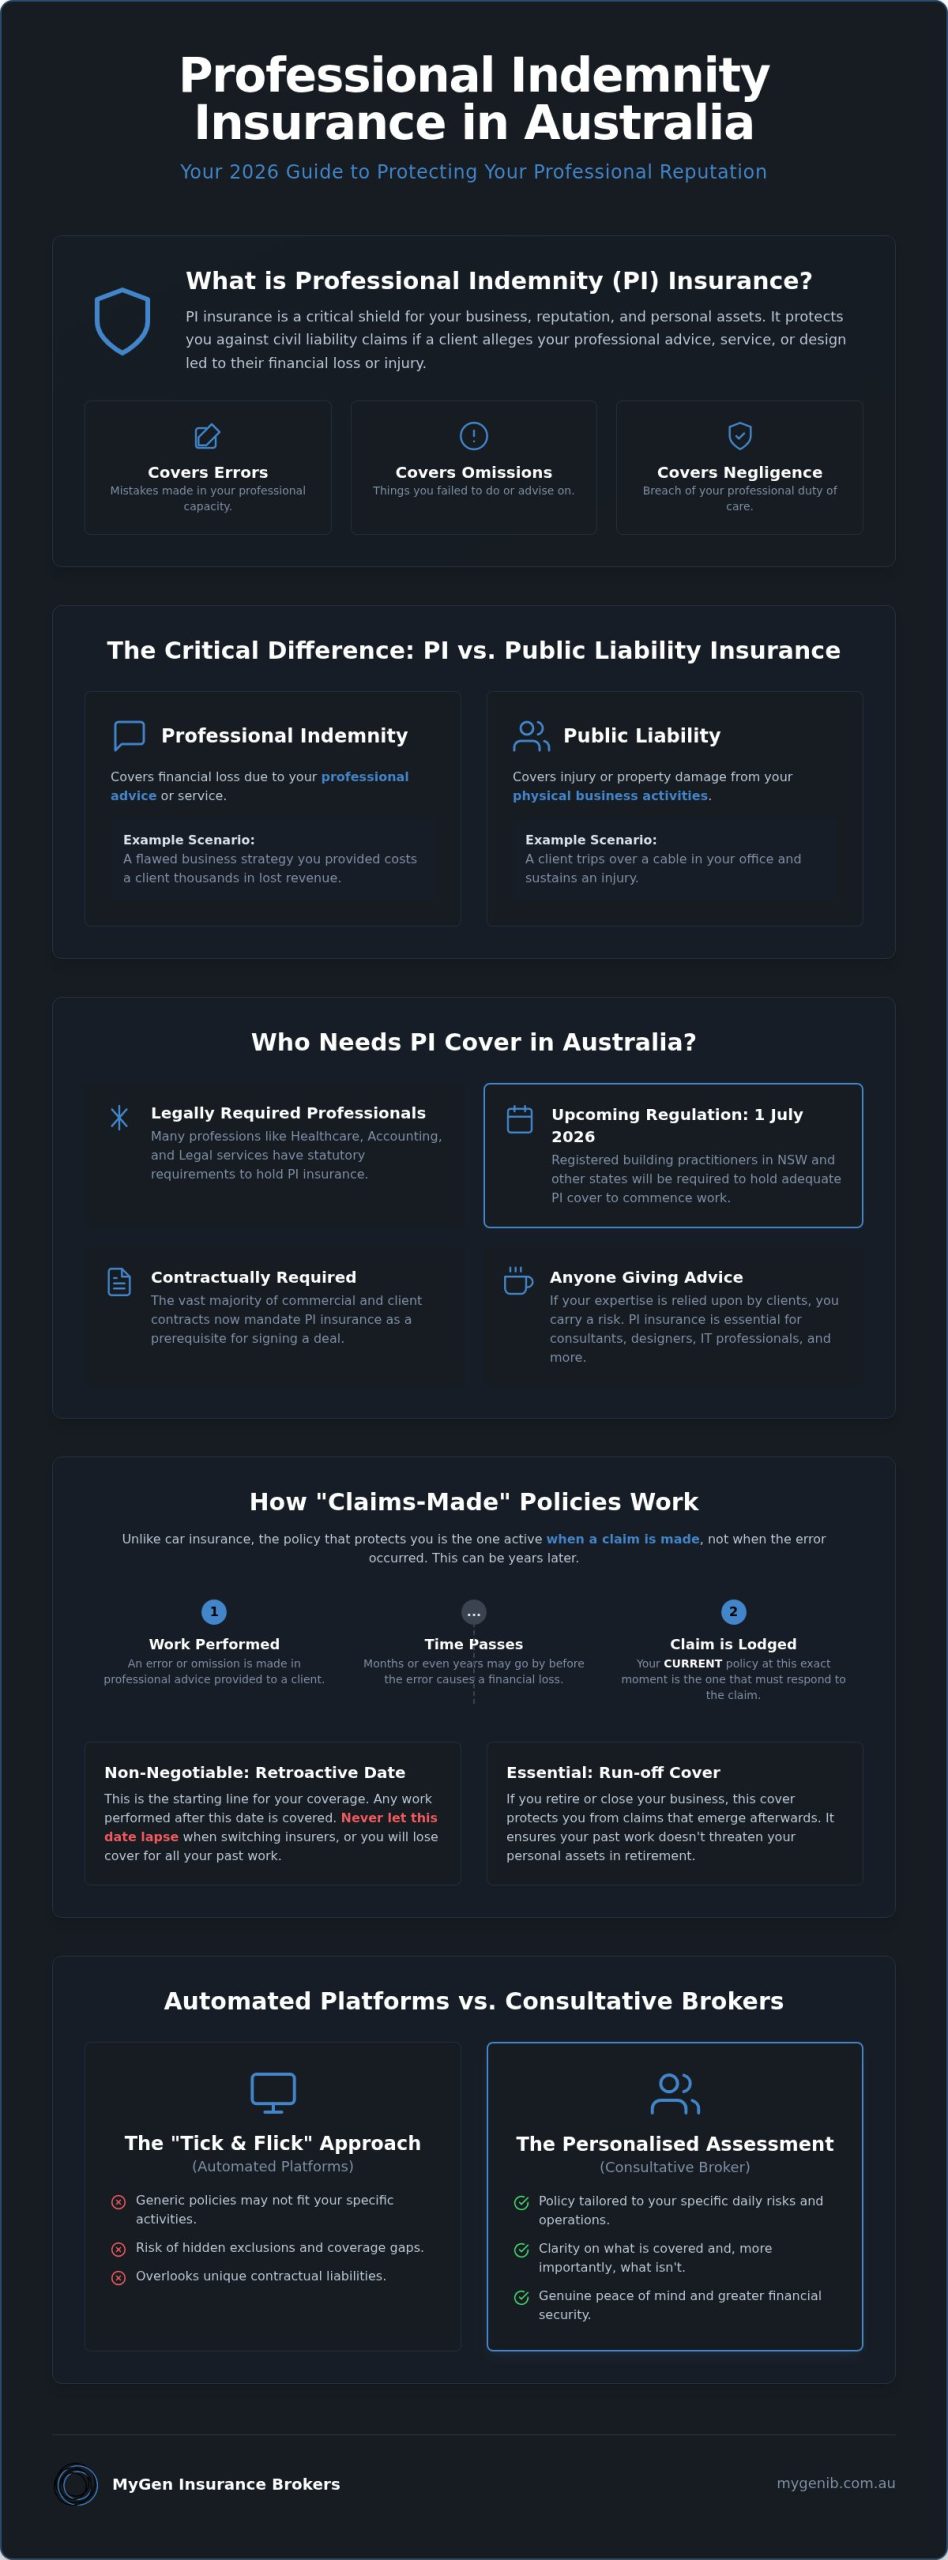
When you share your expertise, you’re also sharing your vulnerability. Understanding what is professional indemnity insurance australia professionals rely on starts with defining it as a shield for your personal assets and hard-earned reputation. At its core, Professional liability insurance, commonly known as professional indemnity (PI) in Australia, protects you from civil liability claims arising from professional advice or services. It’s the safety net that catches you when a client alleges that your error, omission, or professional negligence led to their financial loss or injury.
To better understand this concept, watch this helpful video:
Many business owners confuse PI with public liability, but the distinction is vital. While public liability covers physical actions like a slip and fall, PI covers your professional advice. If a consultant provides a flawed strategy that costs a client thousands, public liability won’t help, but PI will. We view a business insurance policy as a bespoke legal contract tailored to your specific risks, rather than a generic off-the-shelf product that skims over the details.
Who is Legally or Contractually Required to Hold PI Insurance?
For many, holding this cover isn’t a choice. Industries like healthcare, accounting, and legal services have statutory requirements to maintain specific cover levels. From July 1, 2026, upcoming regulatory changes will require registered building practitioners in various Australian states and territories to hold adequate PI insurance before commencing work. Even if the law doesn’t mandate it for your specific field, most commercial contracts now require PI before you can even sign a deal. Any professional offering specialised expertise carries an inherent risk. If your advice is relied upon, you’re potentially liable for the outcome, making it essential to have a policy that actually understands your day-to-day operations.
The Mechanics: Understanding Claims-Made Triggers and Policy Limits
Understanding what is professional indemnity insurance australia wide requires a shift in how you view time. Most professional indemnity insurance policies are “claims-made” contracts. This means the policy in force when a claim is lodged is the one that protects you, regardless of when the mistake occurred. It’s a technicality that often catches people out, especially when they assume their cover works like a standard car or home policy where the event and the claim usually happen simultaneously.
Standard policies typically include protection against negligence, defamation, intellectual property infringement, and breach of confidentiality. However, they aren’t catch-alls. You’ll often find exclusions for “prior known acts” or “contractual liability” clauses that can leave you exposed if you haven’t read the fine print. You can find general advice on these concepts in the Moneysmart guide to professional indemnity insurance. If you’re feeling uncertain about your current limits, we can help you investigate your specific risks to ensure your shield is actually solid.
Why ‘Retroactive Dates’ and ‘Run-off Cover’ are Non-Negotiable
The “tail” of professional risk is long. You could be sued years after a project is completed, which is why your retroactive date is so critical. This date acts as a starting line; any advice given after this point is covered by your current policy. If you switch insurers without ensuring this date is preserved, you essentially leave your past work unprotected. Similarly, run-off cover is essential for those planning to retire or close their business. It provides a safety net for claims that emerge after you’ve stopped trading, ensuring your personal assets don’t pay the price for a mistake from your past career.
The Human Element: Why Professional Risks Require Consultative Care
Many digital platforms promise a quote in seconds, but for complex professional risks, speed is often the enemy of security. While a “tick and flick” automated model might satisfy a contract requirement on paper, it often fails to account for the nuances of your specific daily activities. Expert insurance brokers act as deep-divers into your business, uncovering hidden exposures that an algorithm isn’t programmed to see. When asking what is professional indemnity insurance australia wide, it’s vital to remember that the policy is only as good as the risk assessment behind it.
We take on the heavy lifting of interpreting 100-page Product Disclosure Statements to ensure you aren’t caught out by obscure exclusions. As highlighted in this Insurance Council of Australia submission, the complexity of these products means professional advice is often necessary to avoid coverage gaps. If a claim does arise, we stand as your advocate, managing the friction of the legal process so you can focus on your work.
The MyGen Insurance Brokers Method: Moving from Uncertainty to Clarity
Our approach begins by validating your specific anxieties and investigating the unique landscape of your profession. The difference between a successful payout and a denied claim often rests on a single sentence in your policy schedule. A generic business description is a liability; a personalised one is a shield. By building a long-term relationship with a dedicated mentor, you gain more than just a policy. You gain the peace of mind that comes from knowing your reputation is guarded by a steady, experienced hand who understands your journey from the ground up.
Securing Your Professional Legacy in 2026
Protecting your business requires more than just meeting a contractual obligation; it’s about ensuring a single oversight doesn’t dismantle years of hard work. We’ve seen how the “claims-made” nature of these policies makes continuous cover and retroactive dates essential for your long-term safety. By now, the answer to what is professional indemnity insurance australia wide should be clear. It’s a bespoke legal shield that requires human interpretation to be truly effective.
You don’t have to navigate complex PDS documents alone. With over 20 years of Australian industry experience as an Authorised Representative of the Community Broker Network, we’re here to do the heavy lifting. We reject the “tick and flick” automated model in favour of a personalised, consultative approach that identifies your specific vulnerabilities. Let MyGen deep-dive into your professional risks for true peace of mind. Your expertise is your greatest asset. Let’s work together to keep it protected.
Common Questions About Professional Indemnity
What is the difference between an occurrence-based and a claims-made policy?
Occurrence-based policies trigger based on when the error happened, while claims-made policies trigger when the claim is officially lodged against you. In the Australian market, almost all professional indemnity is claims-made. This means you must have an active policy at the time a client sues you, even if the work was completed years prior. It makes continuous cover and retroactive dates vital for your protection.
Does professional indemnity insurance cover my legal defence costs?
Yes, legal defence costs are a fundamental inclusion in most policies. When you’re trying to understand what is professional indemnity insurance australia wide, it’s helpful to view it as a legal shield. The policy typically pays for solicitors, barristers, and court fees to defend an allegation of negligence, even if the claim is eventually found to be groundless. This ensures your personal funds aren’t drained by legal bills.
How much professional indemnity cover does my small business actually need?
The amount of cover depends on your specific industry standards and the potential financial impact of your advice. For instance, the Tax Practitioners Board requires at least A$2 million in cover for many tax agents. We recommend looking at your largest contract and the “worst-case scenario” financial loss a client could suffer from your error to determine an appropriate limit that offers genuine peace of mind.
What happens if I forget to disclose a past mistake when applying for insurance?
Failing to disclose a past mistake can lead to a total denial of your claim or the cancellation of your entire policy. Under the Insurance Contracts Act, you have a duty of disclosure. If you’re aware of a potential issue, it’s vital to discuss it with us during the application process so we can manage the risk correctly and ensure your cover remains valid.