
A policy that looks suitable on paper may still miss the way you train. If a client is injured during a session or you accidentally damage a venue’s property, questions can arise about your responsibility. Public liability for personal trainers is intended to address certain claims of this kind. It differs from professional indemnity, which relates to claims about your advice or training programmes.
The right cover depends on how, where and whom you train. Gyms, fitness facilities and councils may also set their own insurance requirements. This guide explains the types of claims public liability may address, how it differs from professional indemnity, and what to check about activities, locations, limits and exclusions. Use these points to compare policies and discuss your actual work with an insurance adviser.
Key Takeaways
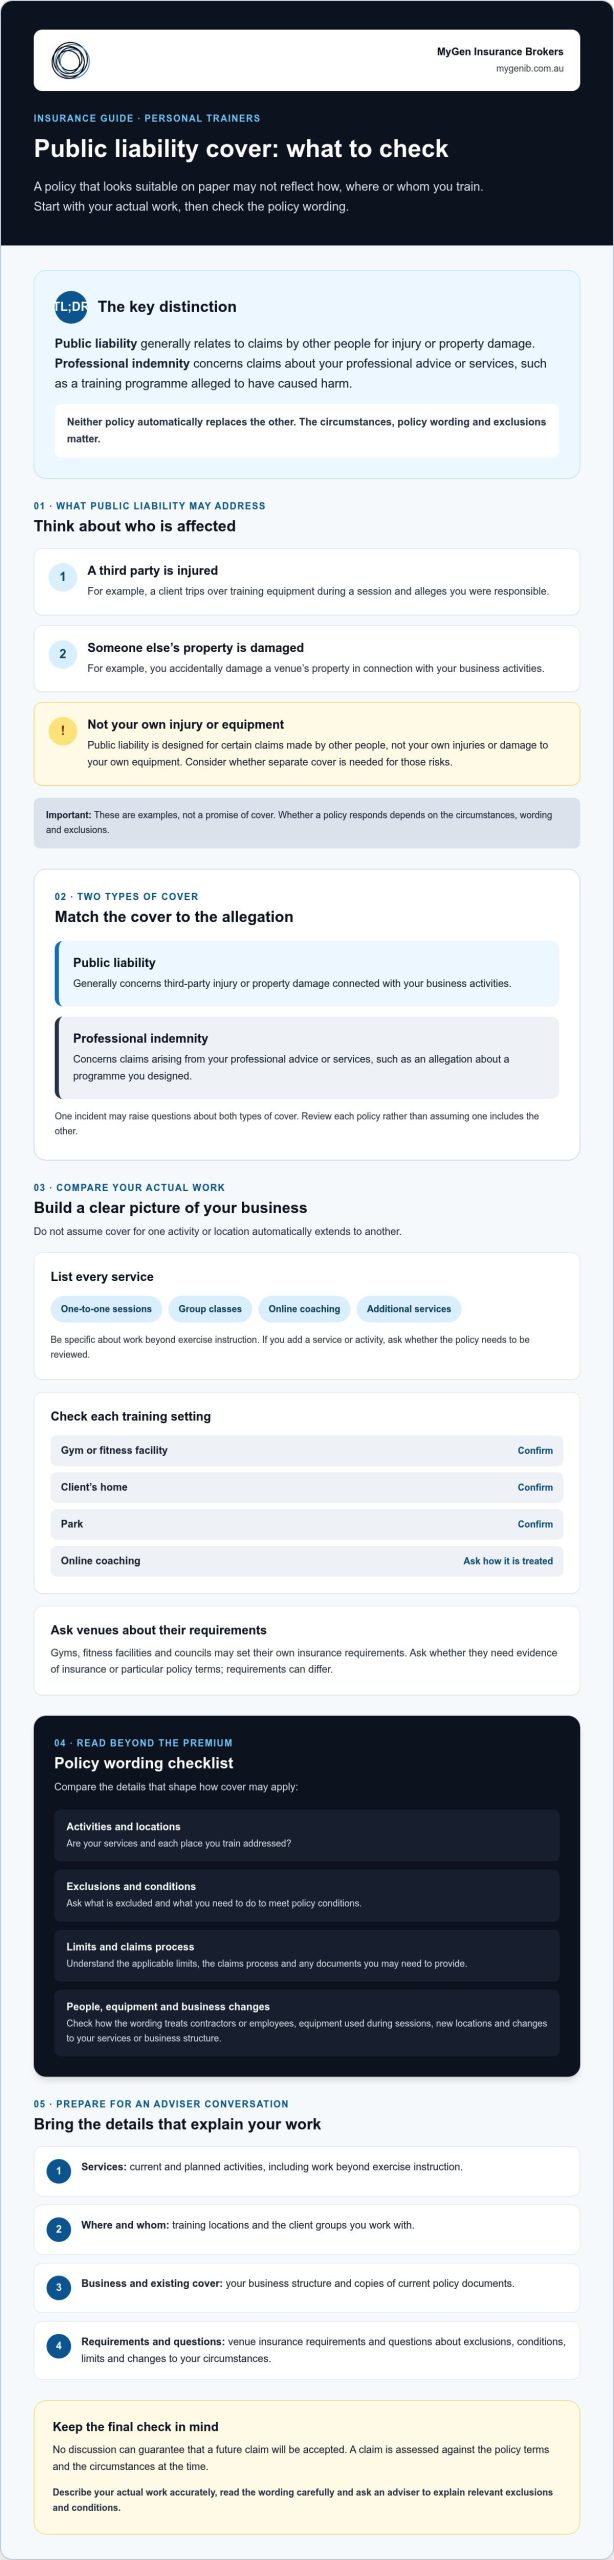
- Check how public liability for personal trainers may respond to third-party injury or property damage claims, and read the policy wording carefully.
- List every service you provide, including one-to-one sessions, group classes, online coaching and any additional services, when comparing cover.
- Confirm that the policy addresses each place you train, such as gyms, client homes and parks, and ask how online work is treated.
- Prepare details about your clients, business structure and existing cover, then ask an adviser to explain relevant exclusions and conditions.
Public liability for personal trainers: what it may cover
Public liability for personal trainers may respond to claims that someone was injured or their property was damaged in connection with your business activities. For example, a client might trip over training equipment during a session and allege that you were responsible. Whether the policy responds depends on the circumstances, the wording and any exclusions. The general concept of Liability insurance can help explain how this type of cover relates to claims made by other people.
Public liability is designed for certain claims made by other people, not for your own injuries or damage to your own equipment. Read the policy wording to see what is included and whether you need to consider separate cover for those other risks.
Public liability versus professional indemnity for trainers
The main difference is the type of allegation. Public liability generally relates to third-party injury or property damage. Professional indemnity concerns claims arising from your professional advice or services. For example, a client might allege that a training programme you designed caused them harm. Depending on the circumstances, an incident could raise questions about both types of cover.
Do not assume either policy replaces the other. Their scope depends on the wording, your work and the claim being made, so review each policy carefully. For a broader explanation of the distinction and related considerations, read this professional indemnity insurance guide.
How to compare public liability for personal trainers
Start by describing your work accurately. List every service you provide, including one-to-one sessions, group classes, online coaching and any additional services. Then check how the policy treats each setting, such as a gym, a client’s home, a park or online coaching. Do not assume cover for one activity or location automatically extends to another.
Compare more than the premium. Look at the activities covered, exclusions, conditions, claims process and documents you may need to provide if an incident occurs. The Australian Government’s overview of Types of business insurance can help place public liability within the broader business insurance picture.
What to check before choosing a trainer insurance policy
Ask each venue whether it requires evidence of insurance or particular policy terms. Requirements can differ, so confirm them directly rather than assuming one policy will satisfy every venue. Check how the wording treats contractors or employees, equipment used during sessions and changes to your services. If you add online coaching or another activity, ask whether your policy needs to be reviewed.
For broader context, read this Australian business insurance guide. A broker can help you review your activities, locations and existing cover. You can discuss your business insurance needs with MyGen Insurance Brokers, without assuming a particular policy outcome.
Arrange suitable public liability cover for your training business
Read the policy wording and ask about exclusions, conditions, limits and what you need to do if your circumstances change. No discussion can guarantee that a future claim will be accepted. A claim is assessed against the policy terms and the circumstances at the time.
What to have ready for a broker conversation
Gather venue insurance requirements, copies of existing policy documents and a list of questions. For example, ask how the wording treats a new training location, an added service or a change to your business structure. This gives the broker a clearer picture to assess and helps avoid relying on assumptions about what standard cover might include.
MyGen Insurance Brokers takes a personalised, consultative approach to reviewing business liability and professional indemnity needs. It uses a tailored broker assessment rather than instant automated quotes. Any options depend on the information provided and available policy terms. Read more about how insurance brokers add value.
To discuss your training activities and business insurance needs, enquire with MyGen Insurance Brokers.
Take the next step towards cover that fits your training
The right public liability for personal trainers depends on the work you do, where you train and the people you work with. Check that the policy wording reflects your activities and locations, and review its exclusions and conditions before deciding. Public liability and professional indemnity address different types of claims, so consider whether your advice and services also need to be assessed.
A conversation with an insurance broker can help clarify these details. At MyGen Insurance Brokers, Anthony Simpson brings over 20 years of industry experience to a personalised assessment rather than an instant automated quote. The discussion can help clarify your business liability and professional indemnity needs, without promising a particular policy outcome.
Discuss insurance for your personal training business and take a considered next step towards cover suited to the way you work.
Frequently Asked Questions
Do personal trainers in Australia need public liability insurance?
Public liability insurance isn’t a strict legal requirement for every personal trainer in Australia, but it may be required in practice. Gyms, fitness facilities and local councils may ask trainers to hold their own cover before working on their premises or in public spaces. Check the requirements of each venue or organisation directly, as conditions can vary.
Does public liability cover a client injury during a personal training session?
It may respond if a client makes a claim alleging that your business activities caused their injury, but cover isn’t automatic. For example, a client might allege they were hurt during a supervised exercise. Whether the policy responds depends on its wording, the circumstances and any exclusions or conditions. Review the policy and ask for clarification if the scope is unclear.
Do personal trainers need both public liability and professional indemnity insurance?
Consider both, because they address different types of allegations. Public liability may respond to claims involving third-party injury or property damage, while professional indemnity relates to claims about your professional advice or services, such as a training programme you designed. A single incident could raise questions about both. Check each policy’s wording rather than assuming one replaces the other.
Does public liability cover personal training in a client’s home or online?
It depends on the policy wording and the work you’ve disclosed. Check specifically whether in-home sessions are included, and tell the insurer or broker if you provide online coaching. Online services may involve advice and programming, so ask whether professional indemnity cover is also relevant. Confirm any exclusions or conditions before relying on cover for a particular activity or location.