
A ransom demand is only one part of a cyber extortion incident. Responding may also involve specialist negotiators, forensic investigation, system restoration and business interruption. For Australian businesses, understanding cyber extortion insurance coverage means looking beyond whether a policy may cover a ransom payment. The limits, exclusions and response conditions can also shape what protection is available.
This guide explains the costs a policy may address, how to assess its wording and which incident-response requirements could affect a claim. It also shows how to map your business’s systems, sensitive data and operational dependencies before reviewing cover. With that groundwork, you can have a more focused discussion about cyber insurance with a broker.
Key Takeaways
- Cyber extortion insurance coverage may address response, negotiation, restoration and interruption costs, subject to the policy wording.
- Map your critical systems, sensitive data and likely downtime to understand the protection your business may need.
- Compare limits, sublimits, waiting periods, exclusions and notification requirements, not just the headline policy limit.
- A clear picture of your systems and response arrangements can help a broker assess your risks and consider suitable cyber insurance.
What cyber extortion insurance coverage may include
Cyber extortion insurance may respond to specified costs arising from a covered incident, such as a ransomware threat to encrypt systems or release stolen data. It forms part of broader Cyber insurance, which can include different forms of first-party and liability protection. The policy wording, the circumstances of the event and whether the business meets the policy conditions determine how cover applies.
Which cyber extortion costs may be covered?
Depending on the wording, cover may include specialist incident response, forensic investigation, legal advice, negotiation support and data or system restoration. These expenses may each be subject to a separate limit or sublimit. The policy may also require insurer approval or specify which providers can be used, so check the process before arranging services where possible.
Business interruption cover may address some loss of income or extra operating expenses if a covered extortion incident disrupts operations. Check how the policy defines interruption, what event triggers cover and when the cover starts. A waiting period or time limit may apply. For example, if a system outage prevents you from fulfilling orders, the policy wording determines whether that disruption and its financial effects meet the relevant conditions.
The policy wording determines which incident costs may be covered, and under what limits and conditions.
A ransom payment isn’t automatically covered. The policy may set approval, notification or other requirements before a payment is considered, and payment must also be lawful. Don’t assume that paying a demand guarantees reimbursement: the circumstances, applicable requirements and policy terms all matter. Before an incident, identify who is responsible for notifying the insurer and what response steps your business should follow. This can help avoid confusion when decisions need to be made quickly.
How to assess cyber extortion insurance terms before an incident
Start by identifying what your business relies on, then compare those exposures with the policy wording. The Insurance Council of Australia outlines common cyber insurance response areas, but the cover that applies to your business depends on its own policy terms.
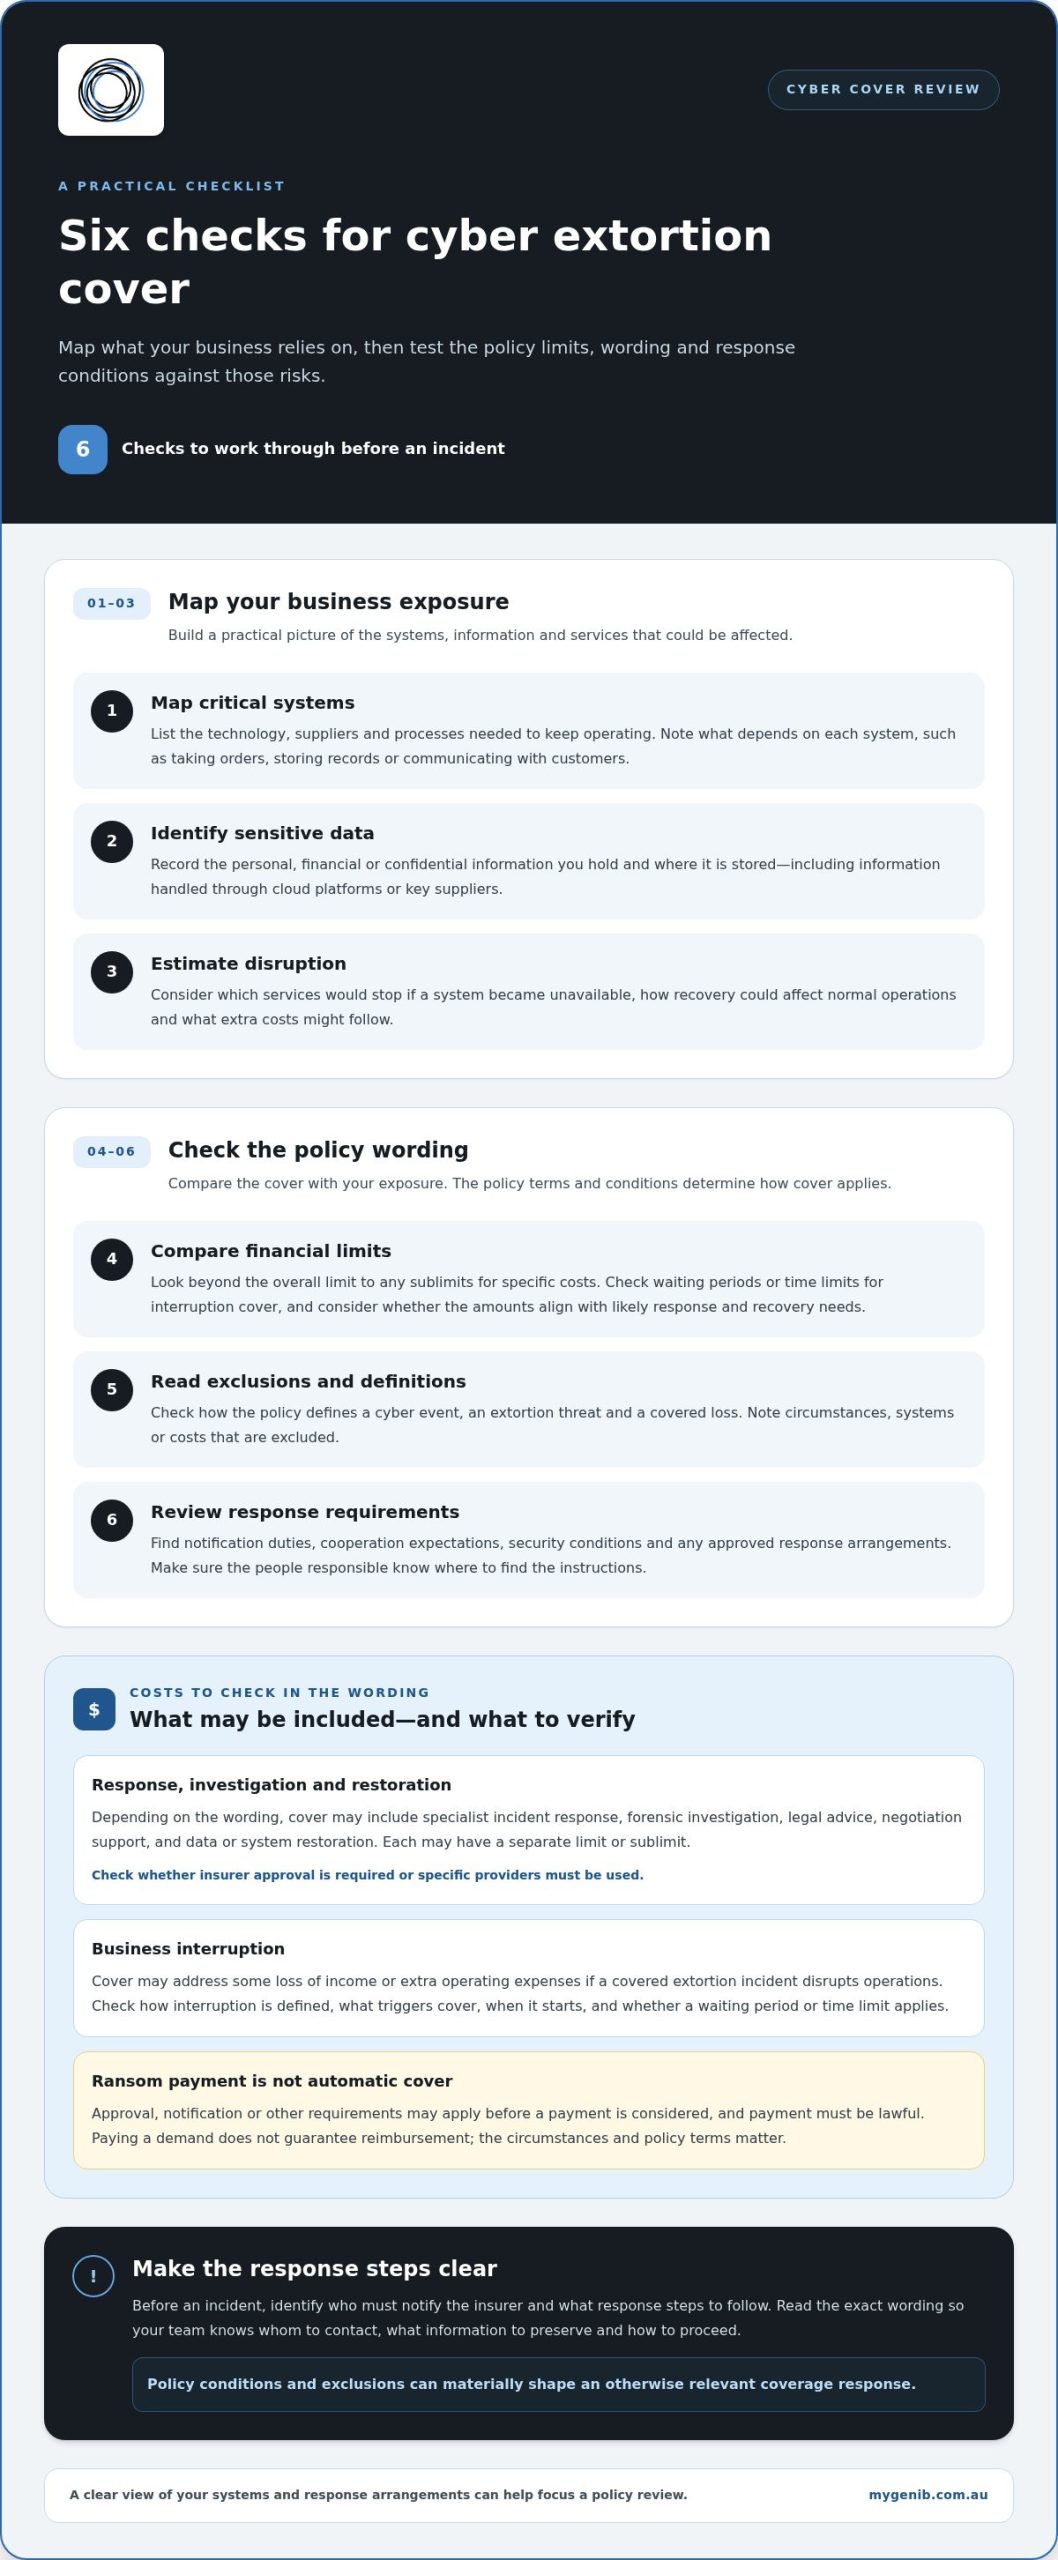
- 1. Map critical systems. List the technology, suppliers and processes your business needs to keep operating. Note which services depend on each system, such as taking orders, storing records or communicating with customers.
- 2. Identify sensitive data. Record the types of personal, financial or confidential information you hold and where it is stored. Include information handled through cloud platforms or key suppliers.
- 3. Estimate disruption. Consider which services would stop if a system became unavailable, how recovery could affect normal operations and what extra costs might follow. This helps make potential business interruption more concrete.
- 4. Compare financial limits. Look beyond the overall limit to sublimits for specific costs. Check any waiting periods or time limits that may apply to interruption cover, and consider whether the amounts align with your likely response and recovery needs.
- 5. Read exclusions and definitions. Check how the wording defines a cyber event, an extortion threat and a covered loss. Note any circumstances, systems or costs that are excluded.
- 6. Review response requirements. Find notification duties, cooperation expectations, security conditions and any approved response arrangements. Make sure the people responsible for an incident know where to find these instructions.
What policy conditions can affect an extortion claim?
Conditions vary between policies. One may set specific security-control requirements or direct you to notify the insurer promptly; another may describe different response and information-sharing steps. Read the exact wording so your team knows whom to notify, what information to preserve and how to proceed if an incident occurs. Policy conditions and exclusions can materially shape an otherwise relevant coverage response.
Use this review to frame a discussion about whether your cyber extortion insurance coverage aligns with your operational risks. MyGen Insurance Brokers provides cyber insurance through a personalised, consultative approach, helping businesses examine their risks and consider policy terms. Learn more about cyber insurance for your business.
How an Australian insurance broker can help you prepare
A clear view of your operations makes a cyber insurance review more useful. Note the systems your team relies on, where sensitive information is held, which suppliers or platforms support essential services, and what arrangements are in place if those systems become unavailable. This gives a broker practical context for discussing how policy wording relates to your business.
MyGen Insurance Brokers takes a personalised, consultative approach to assessing business risks and arranging insurance. A broker can help you examine your exposure, consider how policy wording relates to it and identify questions to address when comparing options. For broader context, read our Australian business insurance guide and the Insurance Council of Australia on cyber risk.
What to have ready for a cyber insurance review
You don’t need a perfect technical inventory to begin. A practical overview can give the discussion a solid foundation:
- Critical systems, cloud platforms and key third-party dependencies.
- Types of sensitive information held, and where it is stored.
- Existing insurance documents, security measures and incident response arrangements.
- Important business functions and the likely effects if they are disrupted.
These details can help you assess whether your cyber extortion insurance coverage reflects your circumstances, rather than relying on assumptions about what a policy includes. MyGen’s broker-led guidance can help bring the relevant risks and wording into focus. Read about the value of working with an insurance broker as you prepare for a considered review.
Build confidence in your cyber insurance decisions
Cyber extortion insurance coverage involves more than whether a ransom demand is addressed. Response costs, interruption protection and claim conditions all depend on the policy wording and your business’s circumstances. Reviewing your systems, sensitive data and operational dependencies can help you spot where cover needs a closer look.
A personalised risk assessment can bring those details into focus. Anthony Simpson brings more than 20 years of industry experience to MyGen’s approach to assessing business risks and arranging insurance. To discuss your circumstances and policy needs, contact the team through MyGen’s cyber insurance guidance.
Understanding your exposure and the terms that matter is a practical first step towards making a more informed cyber insurance decision.
Frequently Asked Questions
Does cyber extortion insurance cover ransom payments?
Not automatically. Whether a ransom payment may be covered depends on the policy wording, applicable requirements and the insurer’s processes. The policy may require prompt notification, insurer approval or the use of specified response arrangements. Review these terms before an incident so you understand the steps that apply. Don’t assume a payment will be reimbursed simply because you hold cyber insurance.
What costs can cyber extortion insurance cover?
Depending on the policy, cyber extortion insurance coverage may include incident response and forensic investigation, negotiation support, data or system restoration, and some business interruption losses. A policy might also address extra expenses incurred to maintain operations during disruption. These are examples, not guarantees. Wording, limits, sublimits, waiting periods and exclusions determine which costs may be covered and how a claim is assessed.
Does cyber insurance cover ransomware attacks?
A ransomware attack is a cyber incident, but that alone doesn’t establish that a policy will respond to a claim. The wording defines which events and losses are covered, while conditions and exclusions may affect how cover applies. Check the policy’s definitions, limits and response requirements, including any obligations around security controls, notification and cooperation, rather than relying on the policy label alone.
What should a business do after receiving a cyber extortion demand?
Activate your incident response plan, preserve relevant information and follow the policy’s notification instructions. Record the demand and related communications, and avoid altering affected systems or evidence unless your response process requires it. Notify the people responsible for managing the incident and follow the response arrangements set out in your plan and policy. Requirements vary, so use the specific wording that applies to your business.