
What if your business has to stop trading, not because your own premises are damaged, but because a key supplier can no longer deliver? Whether business interruption due to supplier failure is covered depends on your policy’s wording and the event that triggers cover. Standard business interruption cover and supplier-related extensions can respond to different events, so don’t assume that a disruption to operations automatically means a loss is insured.
Lost income, continuing expenses and recovery time can all be affected when supply stops. This article explains the difference between direct and supplier-caused interruption, and how to review policy triggers, exclusions and the indemnity period. It also sets out practical steps for mapping supplier dependencies and preparing for disruption. A broker can help relate your business risks to the insurance wording and cover arranged.
Key Takeaways
- Map the suppliers your operations rely on and identify how a delivery failure could affect production, sales or service.
- For business interruption due to supplier failure, cover can depend on the policy wording and the event that triggers it.
- Review definitions, extensions, exclusions, waiting periods and indemnity periods to identify questions about your cover.
- Keep supplier details current, document key dependencies and consider workable alternatives as part of continuity planning.
Business interruption due to supplier failure: what can disrupt your operations?
A supplier outage can affect far more than stock levels. If a manufacturer cannot provide a key component, production may stop. If a wholesaler misses deliveries, sales may fall. If an essential service provider goes offline, your business may struggle to serve customers. The resulting pressure on cash flow can arise even when your own premises and equipment are undamaged.
Supplier-related business interruption is the operational and financial impact on your business when a supplier problem prevents or limits your ability to trade. The cause could be damage at the supplier’s premises or another event that affects its ability to deliver. Whether your resulting loss is insured depends on the policy wording, the events covered, any applicable conditions and relevant extensions.
How is supplier-caused interruption different from direct business interruption?
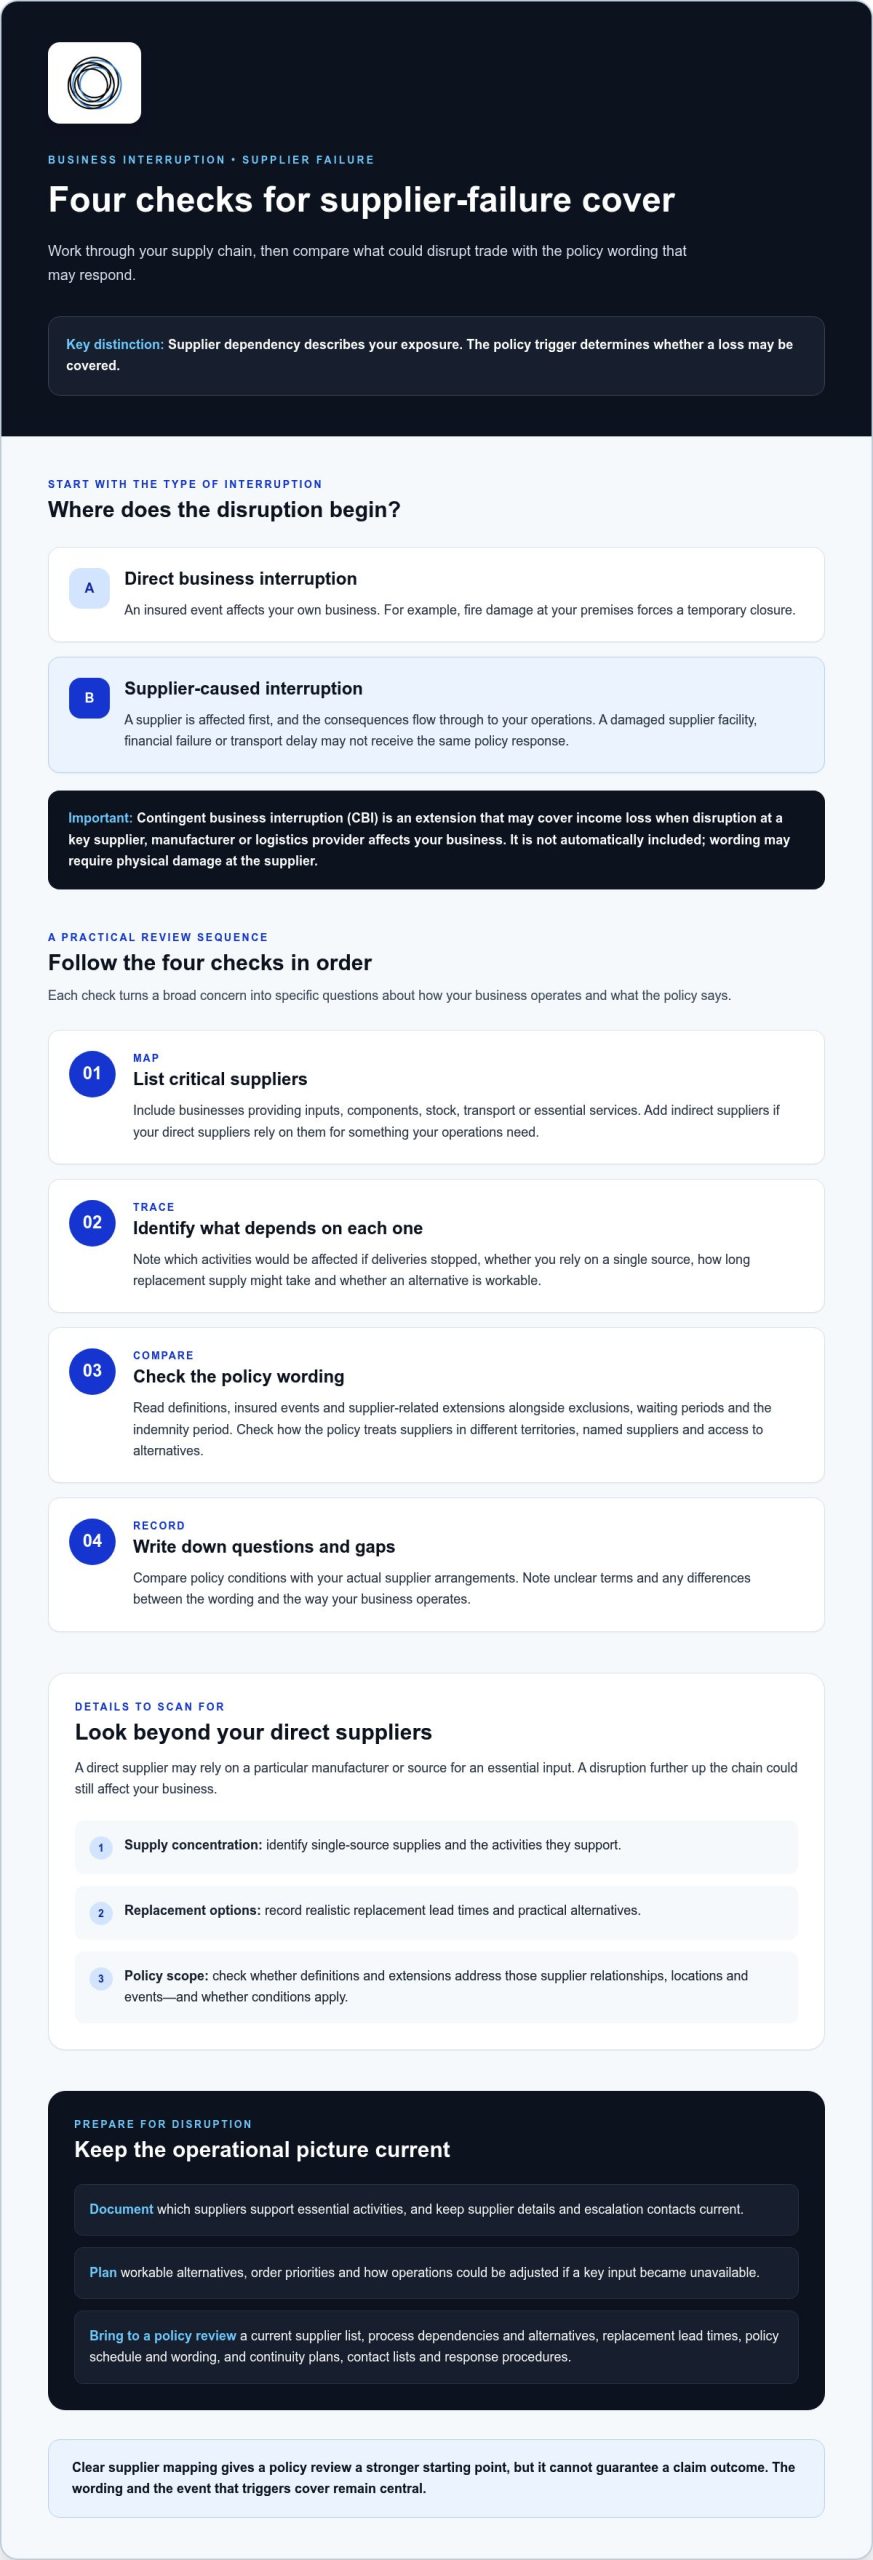
Direct business interruption begins with an insured event affecting your own business, such as fire damage at your premises that forces a temporary closure. Supplier-caused interruption begins elsewhere: a supplier is affected, and the consequences flow through to your operations. A dependency explains how disruption can reach your business, but it does not establish that a policy trigger has been met.
Supplier dependency describes your exposure; the policy trigger determines whether a loss may be covered. Contingent business interruption (CBI) is an extension that may cover income loss when disruption at a key supplier, manufacturer or logistics provider affects your business. It is not automatically included, and cover may depend on specific wording, including whether physical damage at the supplier is required. The overview of business interruption insurance provides useful background, but your own policy wording is what matters.
For example, damage to a supplier’s facility could stop delivery of a part your production line depends on. A supplier’s financial failure or a transport delay could also interrupt supply, but the same policy response may not apply to each event. Check which events and supplier relationships the wording addresses before relying on cover.
How to assess business interruption cover for supplier failure
A structured review turns a general concern into specific questions about your operations and insurance. Start by tracing your supply chain, then compare the dependencies you identify with the policy wording.
- Map critical suppliers. List the businesses providing inputs, components, stock, transport or essential services. Include indirect suppliers if your direct suppliers rely on them for something your operations need.
- Identify dependencies. For each supplier, note which activities would be affected if deliveries stopped, whether you rely on a single source, how long replacement supply might take and whether an alternative is workable.
- Review the wording. Read the definitions, insured events and supplier-related extensions alongside exclusions, waiting periods and the indemnity period. Check how the policy treats suppliers in different territories, named suppliers and access to alternatives.
- Record questions. Note unclear terms and compare the policy conditions with your actual supplier arrangements. This makes it easier to focus a review on the gaps between the wording and the way your business operates.
Which supplier risks and policy details should you review?
Separate direct suppliers from upstream dependencies. A direct supplier may rely on a particular manufacturer or source for an essential input, so a disruption further up the chain could still affect your business. Record single-source supplies, realistic replacement lead times and practical alternatives. Then check whether the policy’s definitions and extensions address those relationships, and whether conditions apply to particular suppliers, locations or events.
The disruption explains your loss; the policy wording determines whether it may respond. The Australian Government guidance on business insurance offers broader context, but your own wording needs to be considered against your dependencies. MyGen’s business insurance advice takes a personalised approach to assessing business risks and suitable insurance solutions.
Prepare for supplier failure and review your insurance with a broker
Insurance is only one part of resilience. A practical continuity plan helps your team respond to disruption while you manage its operational and financial effects. Document which suppliers support essential activities, identify workable alternatives and keep contact details current, including escalation contacts and relevant account information. Consider how you would prioritise orders or adjust operations if a key input became unavailable.
These preparations also make a review of business interruption due to supplier failure more specific. A broker can consider how your business operates, where supply-chain dependencies sit and how those exposures relate to policy definitions, extensions and conditions. MyGen takes a personalised, consultative approach to assessing business risks and insurance needs, helping connect operational realities with relevant policy wording.
What to bring to a business interruption policy review
Bring information that shows how your business runs and where a supplier interruption could affect it. Useful documents include:
- A current supplier list, noting critical inputs and any single-source arrangements.
- A simple outline of processes that depend on each supplier, including possible alternatives and replacement lead times.
- Your existing policy schedule and wording, along with current continuity plans, contact lists and response procedures.
Clear supplier mapping gives a policy review a stronger starting point, but it cannot guarantee a claim outcome. It can make the discussion more specific and highlight where the wording or your preparations need closer attention.
For broader context, MyGen’s The Complete Guide to Business Insurance in Australia: Protecting Your Future explores business protection, while Why Expert Insurance Brokers Provide More Value Than Automated Quotes in 2026 explains the value of tailored advice. A considered broker review can help you assess your exposures and consider suitable insurance solutions.
Take the next step towards greater supply-chain confidence
Supplier relationships can change, and a business that once relied on several sources may become dependent on one. Keep your supplier map and insurance review up to date as operations, suppliers or sourcing arrangements change. This helps you make more informed decisions about business interruption due to supplier failure before a disruption puts pressure on your plans.
MyGen’s personalised, consultative approach connects your business activities and risk-management needs with relevant insurance advice. Anthony Simpson brings over 20 years of industry experience to these conversations, helping you work through the details with care.
Talk with MyGen about reviewing your business risks and insurance needs. A considered review is a practical step towards preparing for supply-chain disruption.
Frequently Asked Questions
Is business interruption due to supplier failure covered by insurance?
It may be, depending on the event, policy wording and circumstances. If a supplier disruption occurs, keep a clear record of when deliveries stopped, which orders or services were affected and the resulting business impact. This information can help your broker assess the circumstances against the cover arranged. A loss of trading alone does not confirm that a claim will be accepted.
What is contingent business interruption cover?
Contingent business interruption is a type of cover that may respond to certain losses when disruption at another business affects your operations. The wording sets the boundaries. It may specify which suppliers or locations are considered, what event must occur and whether indirect suppliers are addressed. Read these details in the policy rather than relying on the label alone.
What happens if my business relies on one supplier and it fails?
Your business may need to pause or adjust work while it manages the supply gap, potentially affecting income and ongoing expenses. Put your continuity procedures into action and keep a timeline of decisions, cancelled or delayed work and communications with the supplier. Then speak with your broker about the circumstances and any relevant policy notification steps.
How can a business prepare for supplier failure?
Make preparation part of ordinary business reviews, rather than waiting until a supplier is already in trouble. Assign someone to keep continuity information current, test whether proposed workarounds are realistic and revisit the plan when a supplier or process changes. A short discussion exercise can also help staff understand who makes decisions and what to prioritise during a disruption.