
What if the title “building designer” on a policy tells you less than the design work you actually do? Professional indemnity for building designers should be assessed against your services and project contracts, not an occupation label alone. A policy may look suitable at first glance, yet its wording, exclusions or limits may not match your responsibilities.
It can be difficult to work out which activities need to be covered or how to compare policy details. This guide explains the professional risks to consider, what to look for in limits, excesses and exclusions, and why contract requirements matter. You’ll have a clearer basis for weighing cover against your work and obligations. MyGen Insurance Brokers takes a personalised, considered approach to professional indemnity, drawing on Anthony Simpson’s more than 20 years of industry experience rather than relying on a generic online quote.
Key Takeaways
- Map your design tasks, advice and coordination duties to the professional indemnity for building designers cover you’re considering.
- Compare policy wording side by side, including covered services, exclusions, retroactive dates, excesses and sub-limits.
- Check how each policy treats defence costs and whether they reduce the indemnity limit. The details can vary by wording.
- Gather your service descriptions, project contracts, current policy details and information about upcoming business changes before reviewing cover.
Professional indemnity for building designers: which work creates exposure?
A design issue can begin with a drawing, a detail left out of documentation or advice relied on during a project. Professional indemnity is cover to consider when a client alleges professional error, omission or harmful advice. Whether a claim is covered depends on the policy wording, including its definitions, exclusions and conditions. Professional indemnity insurance is distinct from cover for claims involving physical injury or property damage.
For professional indemnity for building designers, the key is matching the policy’s description of insured services to the work you actually perform. Drafting plans, preparing construction documentation, advising on design choices and coordinating with other project professionals can involve different responsibilities. Don’t assume a policy covers every activity simply because it names your occupation.
How project duties shape a building designer’s PI needs
Start by listing your services, project types and responsibilities. Note whether you prepare drawings, provide advice, coordinate consultants or take on design-and-construct work. For example, if you make design decisions as well as prepare documentation, that broader role may affect the risks that need to be considered. An allegation of negligent design is different from a claim about physical injury or property damage. The relevant policy response depends on the circumstances and wording.
Next, compare your list with your client contracts and project scope. Contract terms may specify insurance limits or impose responsibilities beyond your usual day-to-day services. State and territory registration or professional requirements can also affect your decisions. Check current rules with the relevant regulator.
This work-by-work approach gives you a stronger starting point for reviewing cover. Our broader professional indemnity insurance guide explains the cover’s wider role for Australian professionals.
How to compare building designer PI policies before choosing cover
Compare the wording, not just the premium or headline limit. For professional indemnity for building designers, check whether each policy describes the services you’ve declared and how it treats the risks and costs relevant to your projects.
Which policy details deserve close attention?
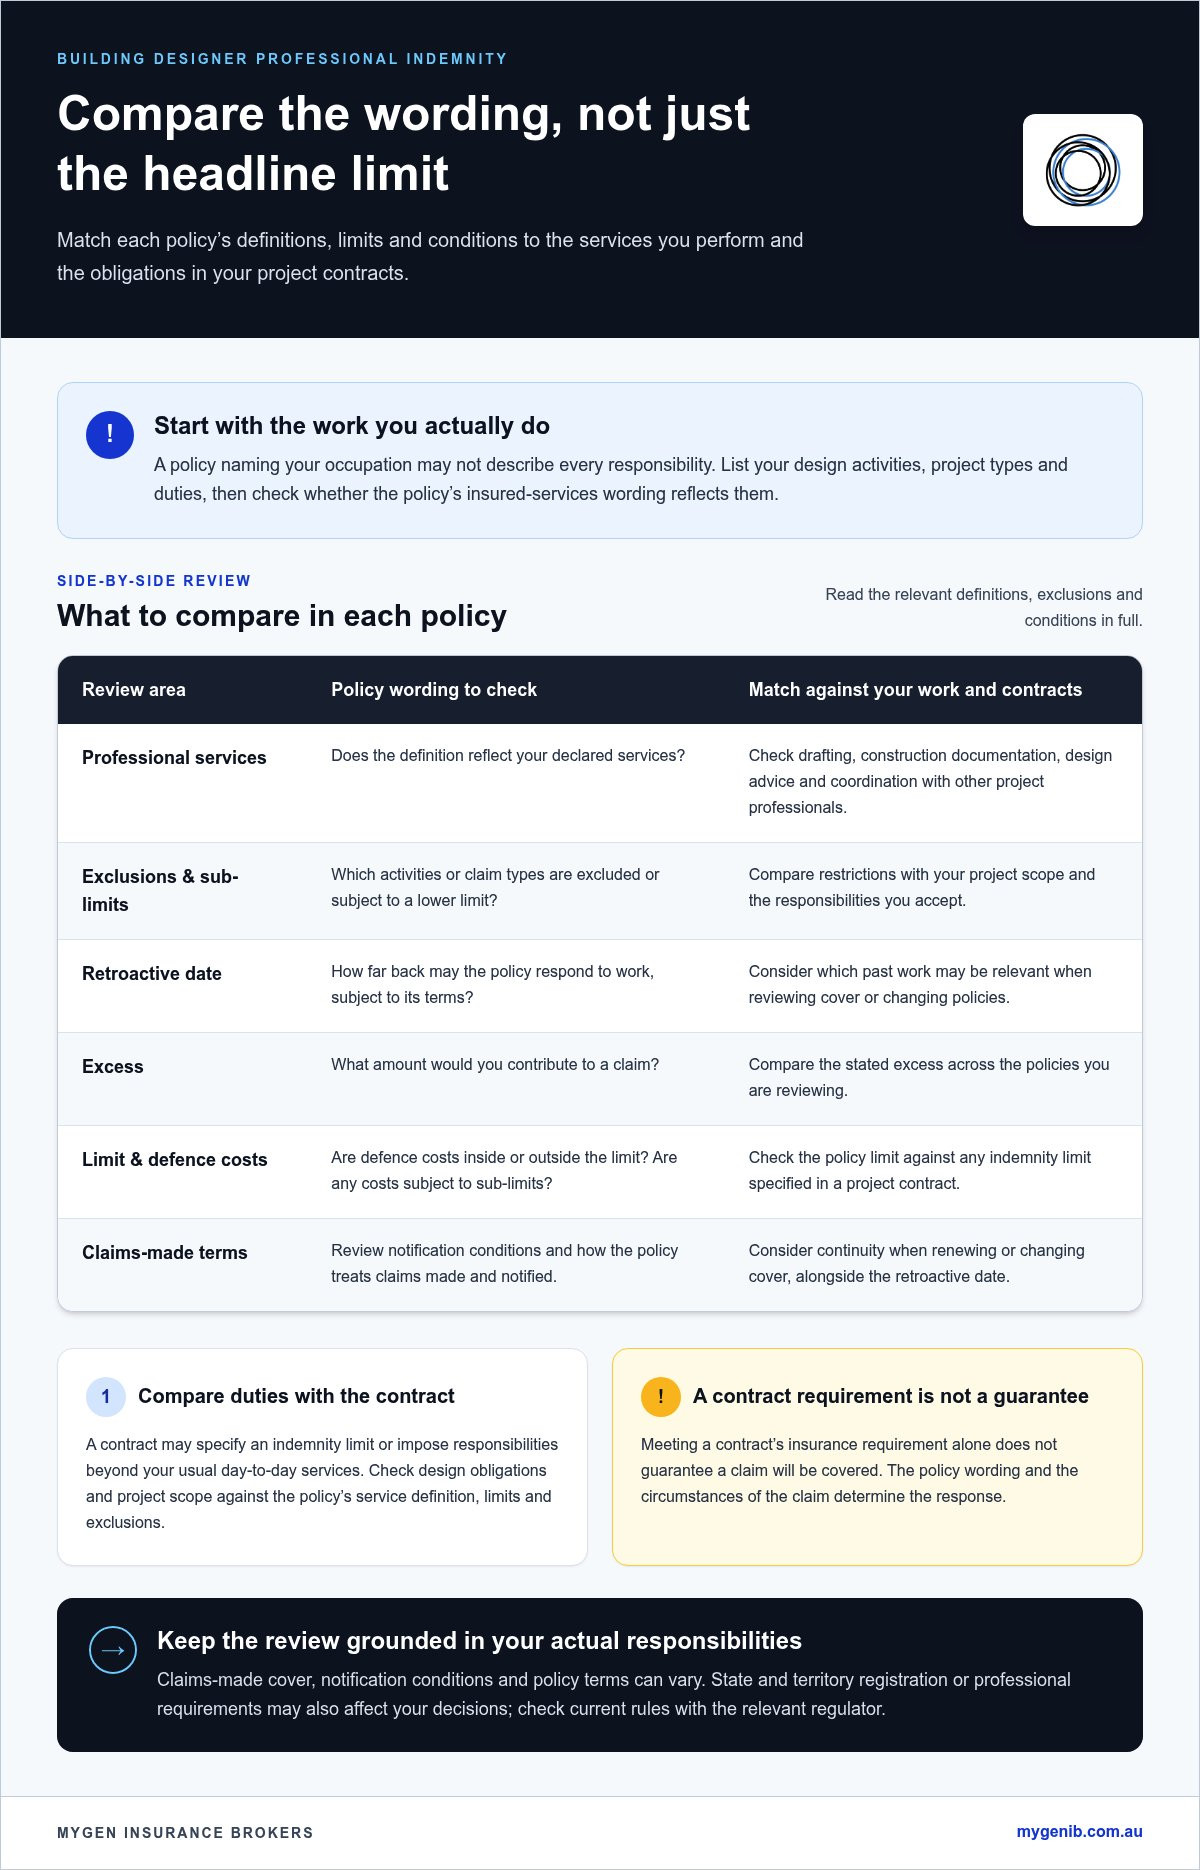
Use a side-by-side comparison to identify differences. Start with your stated design activities, then read the relevant definitions, exclusions and conditions in full.
| Policy detail | What to compare |
|---|---|
| Professional services | Does the definition reflect your declared drafting, documentation, advice and coordination work? |
| Exclusions and sub-limits | Which activities or claim types are excluded or subject to a lower limit? |
| Retroactive date | How far back does the policy potentially respond to work, subject to its terms? |
| Excess | What amount would you contribute to a claim? |
| Limit and defence costs | Are defence costs inside or outside the limit, and are any costs subject to sub-limits? |
Professional indemnity is generally claims-made. The policy in force when a claim is made and notified may be relevant, so review notification conditions and continuity when renewing or changing cover. The retroactive date can affect which past work may be considered. Terms vary between policies, and this information is not legal advice. The UK’s Architects Registration Board guidance on PI insurance applies to architects under its remit, not Australian building designers.
For example, if a project contract specifies an indemnity limit and includes a design obligation, compare both with the policy’s limit, service definition and exclusions. A contract requirement alone doesn’t guarantee that a claim will be covered. MyGen’s complete Australian business insurance guide provides wider context. MyGen also provides personalised insurance advice to help you assess policy wording against your risks.
Arrange building designer professional indemnity with a clear advice process
Once you’ve mapped your duties and compared policy wording, bring the information together for a focused review. Professional indemnity for building designers should reflect the services you perform, the contracts you accept and any changes on the horizon. Preparing these details makes the discussion more specific than relying on an occupation label or a generic quote.
What to prepare for a professional indemnity review
Gather documents that show how your work operates in practice. Set out what has changed, or may change, so the review can account for your current and planned activities.
- Describe your services: Include design, drafting, documentation, advice and coordination, as relevant, with examples of the project types you take on.
- Gather contracts: Note insurance requirements and responsibilities that affect your work, including any design-and-construct obligations.
- Review existing cover: Have your current policy schedule and relevant correspondence ready to compare with your work and contracts.
- Flag upcoming changes: Mention a larger project scale, new design-and-construct responsibilities or changes to subcontracting arrangements.
This gives MyGen a clearer view of your business risks and supports a considered discussion about arranging suitable insurance. MyGen serves businesses nationally and takes a personalised, consultative approach rather than relying on instant automated quotes. Anthony Simpson brings more than 20 years of industry experience to the process.
A review can help identify questions about suitability and policy wording, but it can’t guarantee that a particular claim will be covered or accepted. The policy’s terms and the circumstances of any claim determine the response. Discuss professional indemnity cover with MyGen.
Take the next step with confidence
Your professional indemnity arrangements should keep pace as your design work and project responsibilities evolve. Treat each renewal or change in scope as an opportunity to check whether your cover still reflects the work you intend to take on. Clear information about your services and obligations makes that review more focused.
MyGen offers personalised, consultative insurance brokerage rather than instant automated quotes. Anthony Simpson brings more than 20 years of industry experience to the discussion, helping you consider professional indemnity for building designers with a clearer view of your risks and options.
Talk with MyGen about professional indemnity for your building design work and take a considered next step towards cover that suits your business.
Frequently Asked Questions
Does professional indemnity insurance cover building design errors?
It may respond to certain claims alleging professional errors or omissions, but it won’t cover every design mistake or resulting loss. For example, whether a claim about a missing detail in drawings is covered depends on whether the work was declared, the policy’s exclusions and conditions, and the circumstances. Compare the wording with your services and clarify any terms you’re unsure about during your insurance review.
Do building designers in Australia have to hold professional indemnity insurance?
There isn’t one universal requirement that applies to every Australian building designer. Your position may depend on your state or territory, registration status, professional obligations, contracts and project arrangements. Check current requirements with the relevant regulator and review each contract’s insurance terms. Meeting a requirement is separate from deciding whether a policy suits your actual work.
What is the difference between professional indemnity and design and construct insurance?
The names don’t guarantee a standard scope, and the policies aren’t automatically interchangeable. A designer who also takes on responsibilities within a design-and-construct arrangement should compare the wording with their role, including insured professional services, contractual duties, exclusions and definitions. Review the actual policy and project agreement together before relying on either type of cover.
How much professional indemnity cover should a building designer consider?
There’s no single limit that suits every practice. Consider project values, contract requirements, the services you perform and the potential severity of a claim. Also check whether defence costs reduce the available limit, as this can affect how much remains for a settlement or other covered costs. A personalised review can help you assess your exposure and compare policy wording without assuming a fixed amount is right.