
If you’re working out how to dispute an insurance claim decision, it can be difficult to separate the insurer’s reasoning from dense policy wording, especially when you’re concerned about deadlines or missing evidence. A claim denial or reduced payment does not necessarily end the conversation. Start by identifying the decision and understanding the reasons behind it.
This guide explains how to review the insurer’s explanation, organise relevant documents and make a clear complaint through the appropriate channel. It also covers the insurer’s internal dispute resolution process, when you may be able to take an unresolved complaint to the Australian Financial Complaints Authority (AFCA), and why it’s important to keep track of time limits.
Key Takeaways
- A claim dispute asks the insurer to review its decision against your policy and the information available.
- To understand how to dispute an insurance claim decision, start with the written reasons and relevant policy wording.
- Organise your correspondence, policy documents and supporting evidence before making a clear written complaint, and keep copies.
- Your next step depends on the insurer’s response and the complaint pathway. MyGen offers personalised support through the policy period and claims process. All services are subject to its terms and conditions.
How to dispute an insurance claim decision: first understand the reason
A declined or reduced claim can leave you confused and under pressure, particularly when the decision relies on policy wording that’s difficult to interpret. Knowing how to dispute an insurance claim decision starts with identifying what the insurer decided and why. A dispute asks the insurer to review its decision against the policy and available information. It is more effective to point to specific concerns than to state only that the outcome feels unfair.
Read the decision letter alongside your policy documents and claim records. The letter explains the insurer’s position, the policy wording shows which terms it has applied, and your claim records help you compare that explanation with what happened. Note any unclear reasons or references, and write down the specific point you want explained.
This video offers a general perspective on disputing a claim. Insurance policies and complaint pathways differ between countries, so use your Australian policy and insurer’s process as your guide.
What should you check in a declined or reduced claim letter?
Work through the decision methodically. List each reason the insurer gives, match it to the policy section cited, then note the facts or documents the insurer appears to rely on. For example, if the letter says information was missing, check what was requested and whether you supplied it. This comparison can help you identify a factual gap or a precise question to raise, without assuming the decision is automatically wrong.
Clarify exactly what outcome you’re disputing. A fully declined claim differs from a settlement you believe doesn’t reflect the covered loss or a payment reduced under a policy term. Record the amount or part of the claim in dispute, and keep the decision letter, relevant policy wording and supporting records together. If the complaint remains unresolved, the Australian Financial Complaints Authority (AFCA) is Australia’s external dispute resolution body for financial complaints, including insurance.
How to make an insurance complaint: prepare your case and follow the process
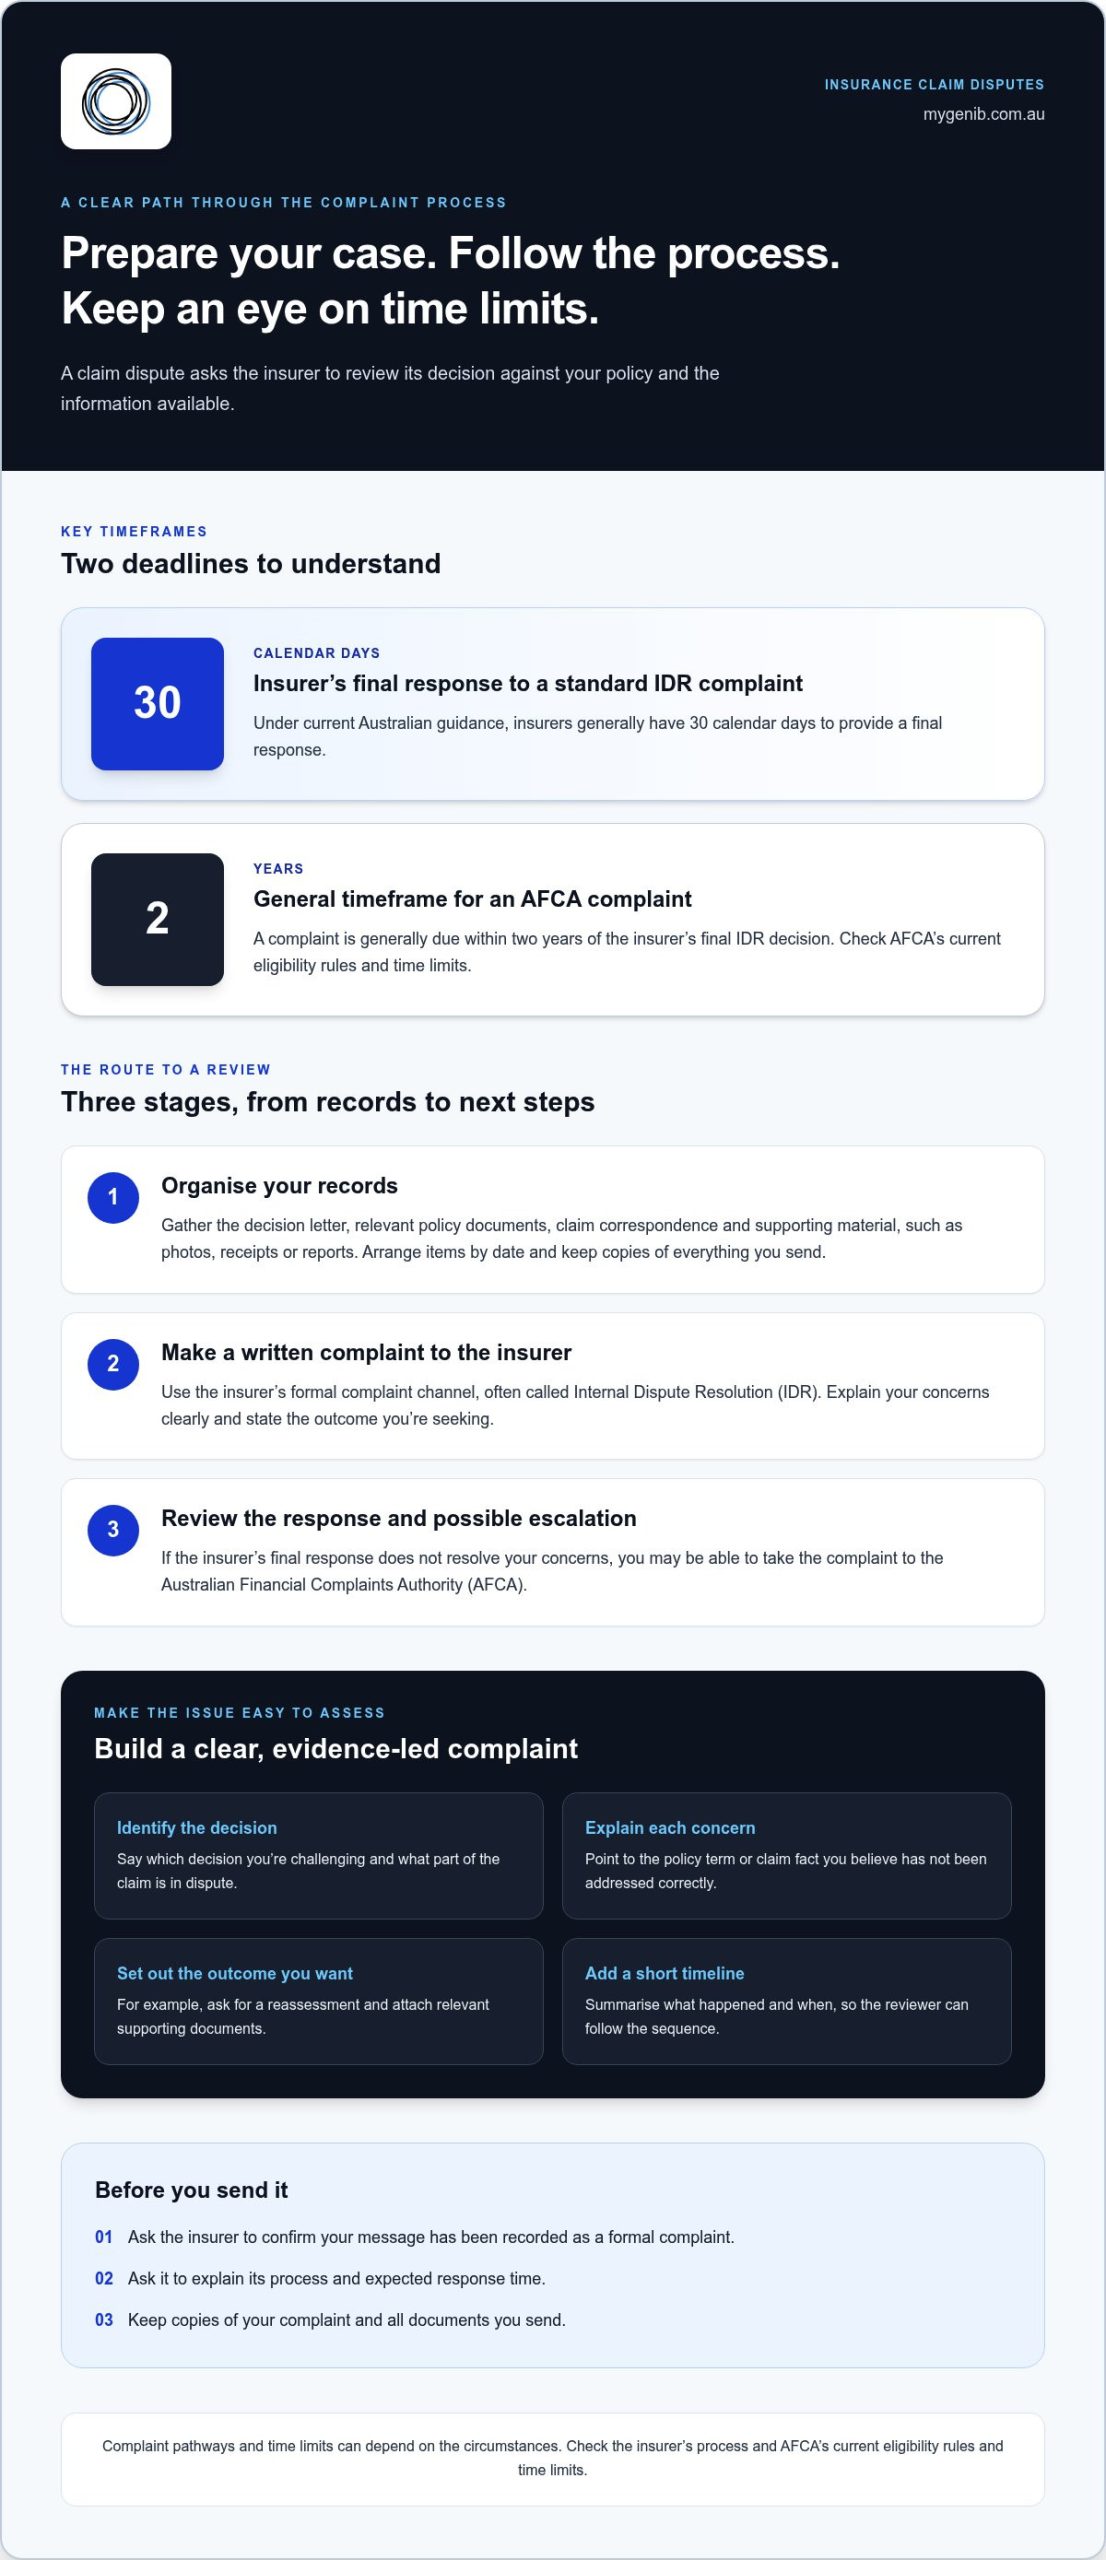
A complaint is easier to assess when the relevant records and questions are organised. To work out how to dispute an insurance claim decision, prepare your documents, complain to the insurer in writing, then consider external escalation if the response doesn’t resolve the issue.
- Organise your records. Gather the decision letter, relevant policy documents, claim correspondence and supporting material, such as photos, receipts or reports. Arrange them by date and keep copies of everything you send.
- Make a written complaint. Send it through the insurer’s formal complaint channel, often called Internal Dispute Resolution (IDR). Keep your message factual and state the outcome you’re seeking.
- Review the response and next step. If the insurer’s final response doesn’t resolve your concerns, you may be able to take the complaint to the Australian Financial Complaints Authority (AFCA).
How do you write a clear complaint to your insurer?
Identify the decision you’re challenging, then explain each concern separately. For example, point to a policy term or claim fact you believe the decision hasn’t addressed correctly. State the outcome you want, such as a reassessment, and attach relevant supporting documents. A short timeline helps the reviewer follow what happened without having to search through a long account.
Ask the insurer to confirm that it has recorded your message as a formal complaint and to explain its process and expected response time. Under current Australian guidance, insurers generally have 30 calendar days to provide a final response to a standard IDR complaint. If you’re considering AFCA, check its current eligibility rules and time limits. A complaint is generally due within two years of the insurer’s final IDR decision.
MyGen provides personalised advice and support through the policy period and claims process, including help understanding policy wording and claims discussions. Explore insurance advice and support. All services are subject to the company’s terms and conditions, viewable on its site.
What to do next: get help with an insurance claim dispute
Your next step depends on the insurer’s response, your policy wording and the complaint pathway that applies. If the insurer hasn’t resolved your concerns, read its final response and consider the relevant escalation options, including whether you can take the matter to the Australian Financial Complaints Authority (AFCA). Check AFCA’s current eligibility rules and time limits so you can make an informed decision.
A broker can help make policy wording and claims discussions easier to follow. MyGen Insurance Brokers provides personalised insurance advice and support through the policy period and claims process. We can help you understand relevant policy wording and prepare for discussions about your claim, but we can’t promise that a review will change the insurer’s decision.
What information should you have ready when seeking broker support?
Gather your policy schedule, the insurer’s decision letter and relevant correspondence. Prepare a concise timeline of what happened and when. Be ready to identify the part of the decision that concerns you, the reasons the insurer gave and the outcome you’re seeking. Having these details together helps keep the discussion focused on the issues that matter.
MyGen brings 20+ years of industry experience to its advice and support. It’s a member of the National Insurance Brokers Association (NIBA) and subscribes to the NIBA Code of Practice. To discuss your circumstances, speak with MyGen about insurance support. All services are subject to the company’s terms and conditions, viewable on its site.
Take your next step with confidence
Once you’ve decided what you want reviewed, keep the next conversation clear and purposeful. Be ready to explain what remains unresolved and what outcome you’re seeking. Knowing how to dispute an insurance claim decision can give you a steadier footing, even when the outcome is still uncertain.
MyGen Insurance Brokers offers personalised support through the policy period and claims process, backed by 20+ years of industry experience, NIBA membership and subscription to the NIBA Code of Practice. This support can help you understand your policy and navigate claims-related discussions, without promising a particular result. All services are subject to the company’s terms and conditions, viewable on its site.
Talk with MyGen about support through your insurance claim. A considered next step can help you move forward with greater clarity.
Frequently Asked Questions
Can I dispute an insurance claim decision if the insurer has only reduced the payout?
Yes. You can raise concerns about a partial settlement as well as a fully declined claim. For example, if the insurer’s payment calculation appears to leave out part of the damage, identify the amount or item in question and ask how it was assessed. Compare its explanation with your policy and claim information, then set out your concerns and the outcome you’re seeking. A complaint doesn’t guarantee the decision will change.
How long do I have to dispute an insurance claim decision in Australia?
Time limits can depend on your policy, the complaint stage and the rules that apply to your circumstances. Check the dates and instructions in the insurer’s decision correspondence, then promptly review the insurer’s current complaint information and AFCA’s guidance. Don’t assume a discussion with the insurer pauses any deadline. If you’re unsure which time limit applies, seek advice early rather than waiting.
Can I take an insurance claim complaint to AFCA?
You may be able to complain to AFCA, which considers eligible complaints about financial firms, including insurers. Acceptance depends on the details of your dispute and AFCA’s current rules, so not every claim complaint will qualify. Check AFCA’s current insurance complaint guidance and follow any applicable steps with your insurer first. Keep your policy details and complaint correspondence available when reviewing eligibility.
What if my insurer does not change its claim decision?
If the insurer maintains its position, read its final response carefully and note whether it explains any further review options. Depending on your circumstances and current rules, another complaint pathway may be available, including AFCA. Keep the final response and related correspondence together, and check authoritative guidance before deciding what to do. A court case isn’t automatically the next or only option.