
Could a policy that looks adequate on paper still leave uncertainty when a client challenges your advice? Professional indemnity for financial planners should reflect the advice you provide, your authorisation and how your practice operates, not just a headline limit. Allegations may involve unsuitable investment or superannuation recommendations, inaccurate advice, risks that were not clearly explained or administrative errors.
Policy wording can be difficult to compare, particularly when exclusions, excesses and claim limits differ. This guide outlines common financial-planning exposures and what to examine in your cover, including how claims-made wording can affect continuity. It also explains which details about your practice can help shape a focused review. MyGen Insurance Brokers takes a personalised approach to reviewing and sourcing Professional Indemnity Insurance, with recommendations shaped around your practice and its circumstances.
Key Takeaways
- Understand how allegations such as inadequate disclosure or an implementation error may raise professional liability concerns, subject to policy wording.
- Assess professional indemnity for financial planners against your advice areas, client types, business structure and authorisation arrangements.
- Look beyond the headline limit: compare covered services, exclusions, excesses and how defence costs are treated.
- Prepare for a tailored review by documenting your advice activities, noting practice changes and gathering your current policy information.
What Professional Indemnity for Financial Planners Covers
Professional indemnity (PI) insurance can cover specified claims alleging that a professional error or omission caused a client loss, subject to the policy wording, exclusions and circumstances. PI insurance may respond to allegations about the professional service provided, not simply to an investment performing poorly. It is not blanket protection, and an allegation does not automatically mean a claim is covered.
Professional indemnity insurance is a broad category of cover for claims connected with professional services. For financial planners, the practical question is whether the policy’s definition of insured services and its other terms align with the work the practice actually undertakes.
Which financial-planning activities can create professional exposure?
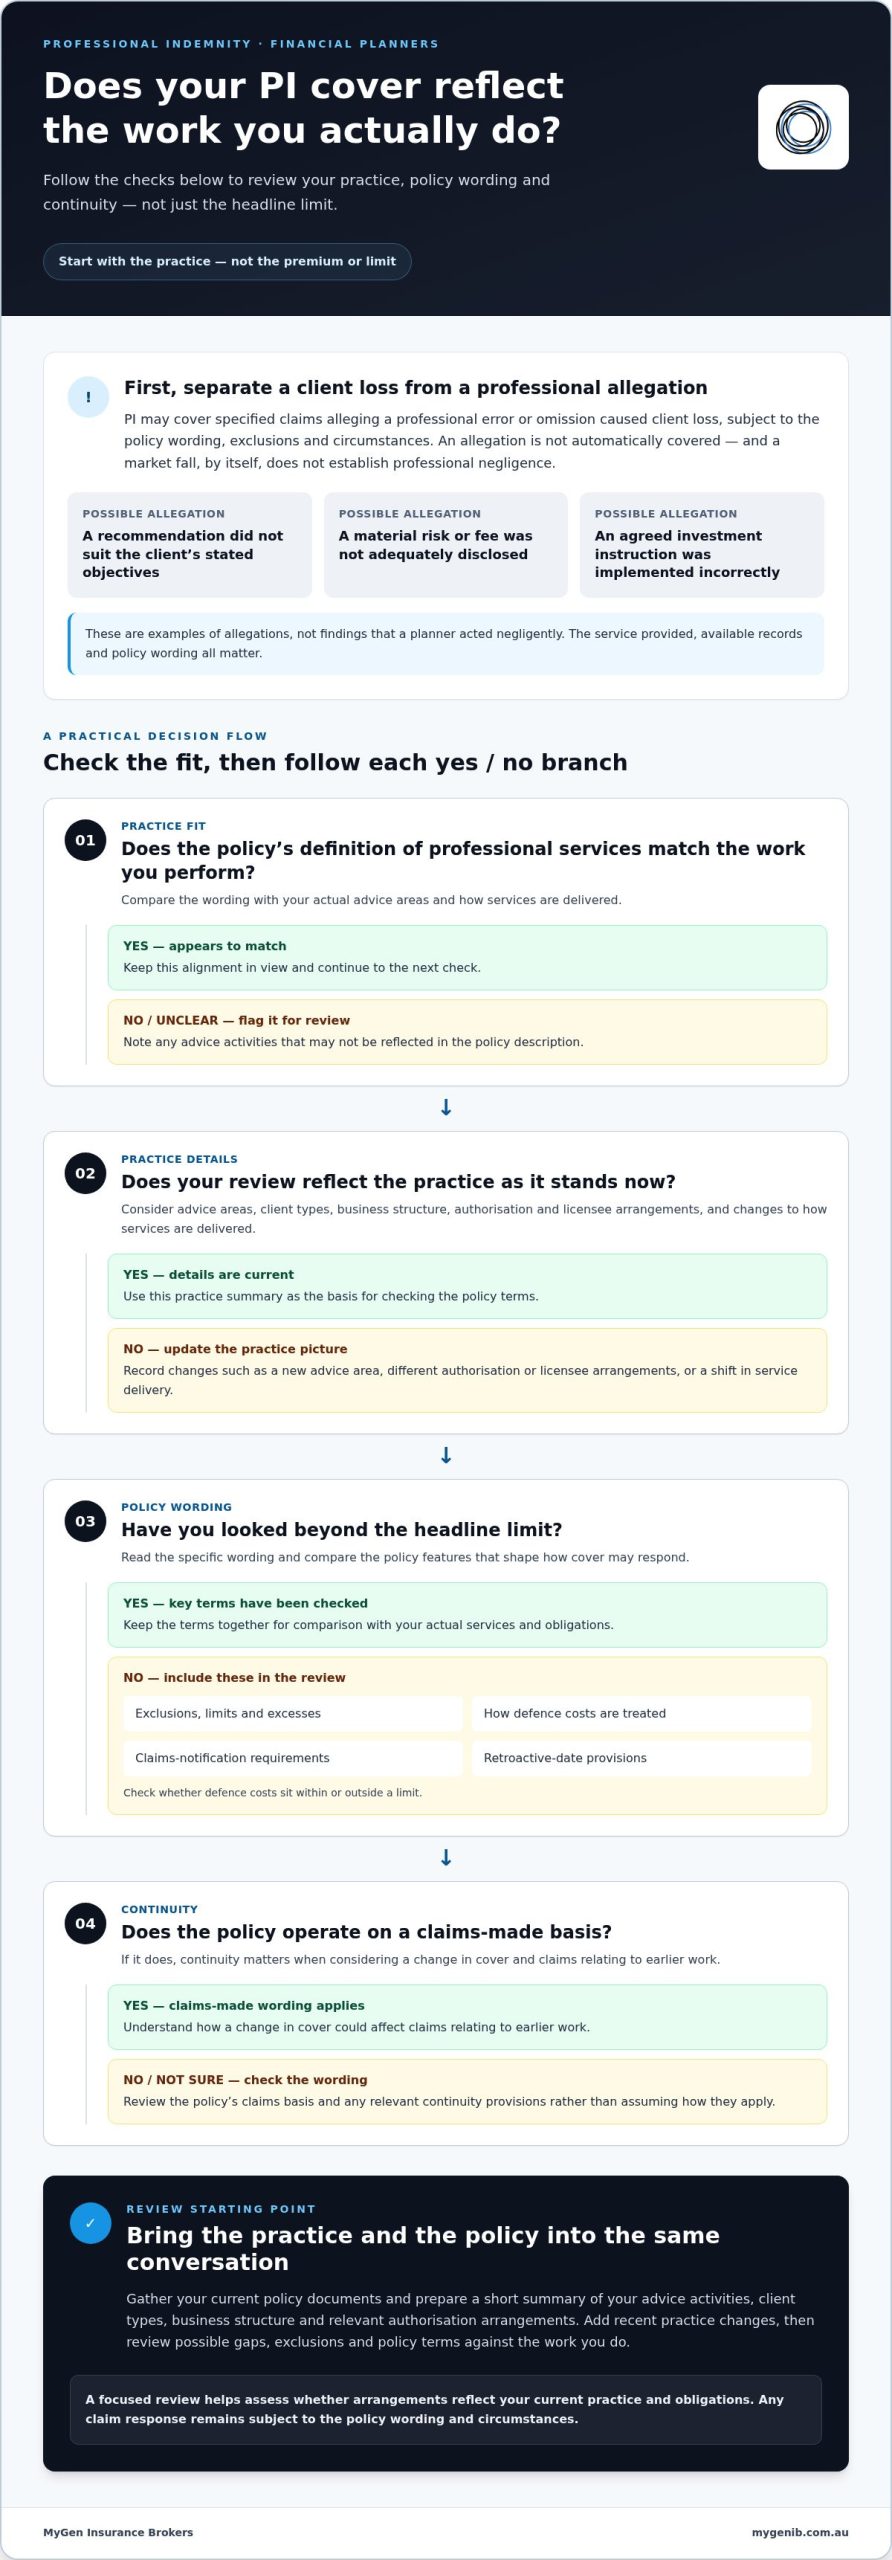
Exposure can arise at different points in the advice process. A client might allege that a recommendation did not suit their stated objectives, that a material risk or fee was not adequately disclosed, or that an agreed investment instruction was implemented incorrectly. These are examples of allegations, not findings that the planner acted negligently.
The circumstances matter. A client’s loss after a market fall, by itself, does not establish professional negligence or guarantee an insured claim. The service provided, the available records and the policy wording all affect whether cover may respond. Consider whether your advice, disclosures and implementation procedures fit the policy’s description of professional services.
For professional indemnity for financial planners, this distinction keeps the review focused on the alleged professional act or omission rather than treating every client loss as the same kind of risk. Examples can help identify questions to examine, but only the policy wording and the specific circumstances determine whether a particular claim is covered.
How to assess professional indemnity cover for your financial-planning practice
Start with the practice, not the premium or headline limit. Make a clear summary of the advice areas you work in, the types of clients you serve and how the business is structured. For instance, whether your practice focuses on local superannuation or broader wealth preservation frameworks like those discussed by advisory firms such as Zenith Wealth, detailing the exact scope of your recommendations is vital. Include relevant authorisation and licensee arrangements so the review can take account of the services you provide and your responsibilities. Note any changes, such as adding an advice area or changing how services are delivered.
A useful test is whether the policy fits your actual services, its wording reflects your practice, and the cover aligns with your current obligations. This gives you a more meaningful basis for assessing professional indemnity for financial planners than comparing limits alone.
What should you check in the policy wording and practice information?
Compare the policy’s description of professional services with the work you actually perform. Then review the exclusions, limits and excesses, as well as the provisions for defence costs. Check whether defence costs sit within or outside a limit, and read the claims-notification requirements and any retroactive-date provisions in the specific wording. If the policy operates on a claims-made basis, continuity matters: understand how a change in cover could affect claims relating to earlier work.
For a focused review, gather your current policy documents and summarise your advice activities, client types, business structure and relevant authorisation arrangements. Add any recent changes to the practice. This preparation makes it easier to identify questions about gaps, exclusions or policy terms. For a broader explanation of policy considerations, see our guide to professional indemnity insurance.
MyGen Insurance Brokers reviews business risks and sources Professional Indemnity Insurance as part of a personalised business-insurance review. The review considers your practice and circumstances, while any claim response remains subject to the policy wording. Explore Professional Indemnity Insurance support as you consider your next steps.
A clearer next step for financial planners reviewing PI insurance
A practical review starts with a clear picture of the practice. Set aside your current policy documents, then prepare a short summary of the advice activities you perform, the clients you serve and your business structure. Note changes since the last review, including new services, changes to your authorisation or licensee arrangements, or a shift in how advice is delivered. This gives the review a practice-specific starting point.
With those details in hand, you can assess whether your current arrangements still reflect the work you do. A focused review of professional indemnity for financial planners brings policy terms and practice risks into the same conversation, without assuming that an insurer will offer particular terms or accept a claim.
How a broker can help turn a policy review into a practical plan
MyGen Insurance Brokers takes a personalised approach. Brokers review your risks, identify possible blind spots, then use that understanding to design a customised insurance package and source cover. The review can consider PI alongside the wider needs of your business, as explained in this guide to business insurance in Australia. MyGen also supports clients through the policy period and assists with the claims process, with any claim response subject to the policy wording and circumstances.
MyGen is a member of the National Insurance Brokers Association (NIBA) and subscribes to the NIBA Code of Practice. Services are subject to MyGen’s terms and conditions, which are viewable on the site. If you’re ready to discuss a practice-specific review, talk with MyGen about Professional Indemnity Insurance.
Make your next review a confident step forward
Your practice can change over time, so it is worth revisiting your insurance arrangements as your work or circumstances evolve. A deliberate review helps keep the cover discussion connected to how you operate now and gives you a clearer basis for decisions. That is the value of a considered approach to professional indemnity for financial planners: not a promise of a particular outcome, but a more informed way to assess suitability.
MyGen Insurance Brokers brings 20+ years of industry experience to personalised risk reviews and claims assistance. As a NIBA member and subscriber to the NIBA Code of Practice, MyGen is committed to professional brokerage standards. Services are subject to terms and conditions viewable on the site.
Explore a tailored Professional Indemnity Insurance review with MyGen and discuss a practical next step for your practice.
Frequently Asked Questions
Is professional indemnity insurance compulsory for financial planners in Australia?
Not for everyone simply because they’re called a financial planner. Under ASIC Regulatory Guide 126, Australian Financial Services (AFS) licensees providing financial services to retail clients must maintain adequate compensation arrangements, typically PI insurance that meets applicable standards. Whether this applies to your practice and what arrangements are required depends on your licence and business structure.
Does professional indemnity insurance cover investment losses?
Generally, PI insurance is not protection against an investment falling in value simply because markets moved against it. A claim may raise a separate issue if a client alleges professional negligence, but the policy wording and circumstances determine whether cover may respond. For example, a documented market fall despite disclosed risks differs from an allegation that advice did not reflect agreed objectives. Neither situation alone determines the insurance outcome.
Can a financial planner rely on their licensee’s professional indemnity policy?
Not automatically. A licensee’s policy may cover authorised representatives in defined circumstances, but do not assume it includes your business entity, every service, or work after you leave. Review the relevant wording and schedule to understand who is insured, which activities are covered, how claims must be notified and what happens if your authorisation changes. Professional indemnity for financial planners depends on the specific policy and arrangement.