What if the damage your tenant left behind isn’t considered ‘malicious’ by your insurer, leaving you to foot a five-figure repair bill alone? We understand the quiet anxiety that comes with handing over the keys to your most significant asset, as you’ve likely spent years building your property portfolio. It’s a common frustration to feel that your malicious damage by tenant insurance cover might contain fine print that excludes the very events you fear most.
We’ll help you navigate the complex definitions that separate accidental mishaps from intentional harm, ensuring your investment is truly protected under Australian law. We’ll examine the distinction between wear and tear and malicious acts, providing a streamlined path to recovery if things go wrong. You’ll gain the clarity required to manage your property with professional confidence and genuine peace of mind.
Key Takeaways
- Define the critical difference between intentional harm and accidental mishaps to ensure your policy responds exactly when you need it.
- Master the documentation process by using comprehensive Entry Condition Reports and date-stamped photos to build an undeniable case for your insurer.
- Learn why a personalised approach to malicious damage by tenant insurance cover provides more robust protection than the standard gaps found in generic, automated policies.
- Discover how a dedicated broker acts as your advocate during the claims process, moving you from a state of uncertainty to one of calm and security.
Malicious Damage vs. Accidental Damage: Defining the Risk
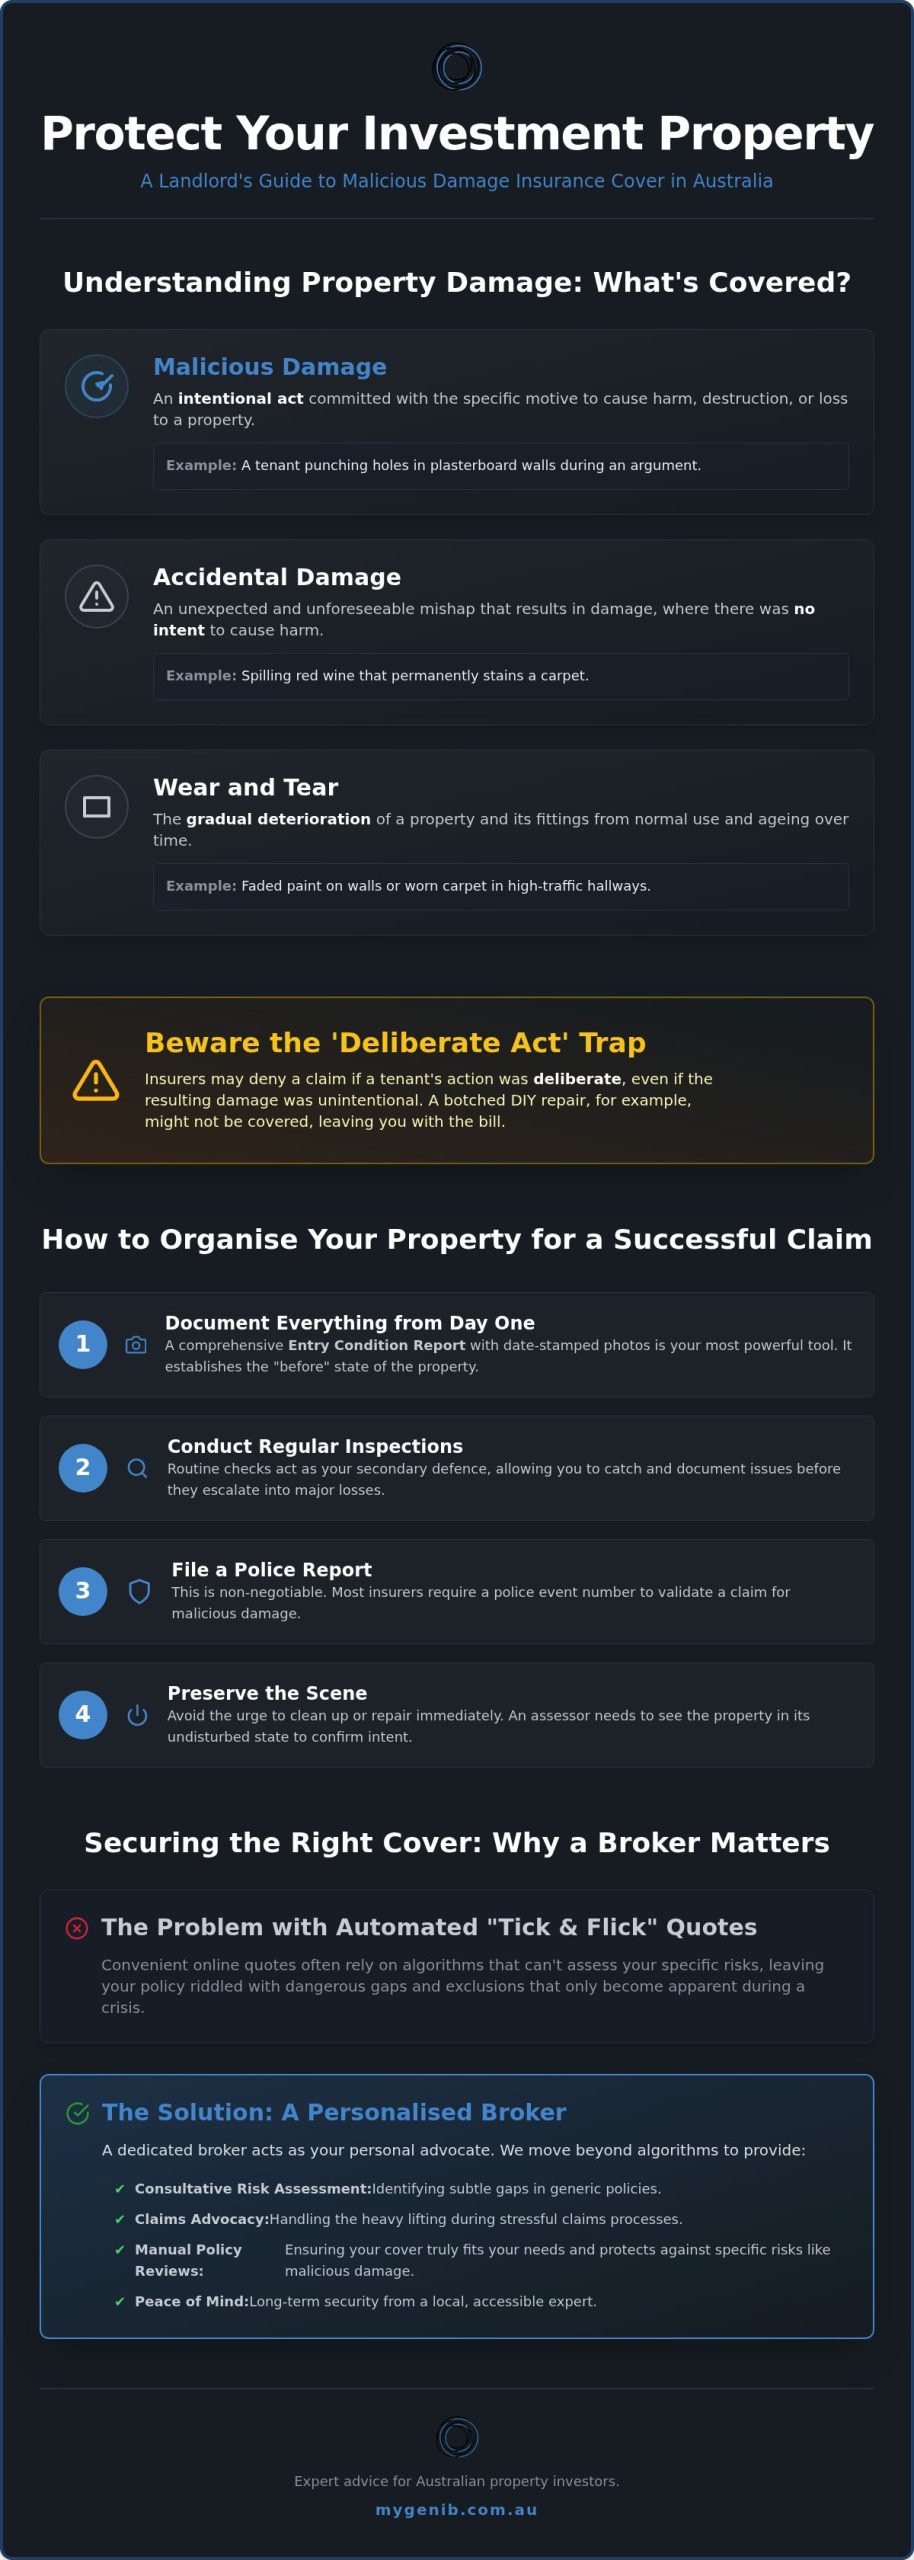
Understanding the nuances of your policy is the first step toward genuine protection. Malicious damage is an intentional act driven by a motive to cause harm or destruction. Think of a tenant punching holes in plasterboard during an argument. This differs sharply from accidental damage, which lacks intent, or the gradual wear and tear that occurs over years of occupancy.
In an insurance context, malicious damage is defined as an intentional act committed with the specific motive to cause harm, destruction, or loss to a property.
Landlords often fall into the deliberate act trap. This occurs when an insurer denies a claim because the tenant intended the action, but perhaps not the resulting damage. For example, if a tenant attempts a DIY repair that goes wrong, the act was deliberate, but the damage wasn’t necessarily malicious. Without the right malicious damage by tenant insurance cover, you might find yourself responsible for the full cost of professional repairs.
Why Policy Wording is Critical for Australian Landlords
Every insurer in Australia interprets these terms differently, impacting your out-of-pocket expenses. Some policies carry a higher excess for claims involving malicious damage by tenant insurance cover, while others have restrictive sub-limits hidden within standard building covers. We often see cheap policies that offer very little when a major event occurs. Securing comprehensive landlord insurance through a specialised broker ensures you aren’t caught out by these subtle wording variations. It’s about finding a policy that actually stands up when tested.
How to Organise Your Property for a Successful Claim
Discovering a trashed property is heartbreaking. We’ve seen landlords lose thousands because they lacked the paper trail required by their insurer. A comprehensive Entry Condition Report with date-stamped photos is your most powerful tool. It provides the “before” to the insurer’s “after,” removing any ambiguity about when the damage occurred. Regular routine inspections act as your secondary defence, catching issues before they escalate into catastrophic losses that could have been avoided.
When you suspect intentional harm, a police report is non-negotiable. Most insurers require a police event number to validate a claim under your malicious damage by tenant insurance cover. While the rental bond provides a small financial buffer, it rarely covers major structural repairs or specialised cleaning. This is where professional brokerage makes the difference, as we help you navigate these requirements to ensure your malicious damage by tenant insurance cover isn’t undermined by a technicality during the assessment phase.
The Role of Detailed Evidence and Reports
To meet the “intent” criteria, you must prove the damage wasn’t a simple accident. Avoid the urge to clean up or repair the site immediately. An assessor needs to see the property in its undisturbed state to confirm the nature of the act. If you’re unsure if your current documentation is sufficient, speaking with a broker can provide the clarity you need. We recommend maintaining a digital folder containing the following:
- Signed tenancy agreements and bond lodgement forms.
- Detailed logs of all routine inspections including high-resolution photos.
- Professional repair quotes from licensed Australian tradespeople.
- The original Entry Condition Report signed by both parties.
Securing the Right Cover: Why Personalised Brokerage Matters
We’ve seen many landlords opt for the convenience of a two-minute online quote, only to discover their policy is riddled with exclusions when a crisis hits. These “tick and flick” models rely on algorithms that can’t appreciate the specific risks of your property or the history of your tenancy. A consultative risk assessment looks beneath the surface, identifying the subtle gaps in cheap policies that often exclude the very events covered by robust malicious damage by tenant insurance cover. This thoroughness ensures your protection is built on a foundation of reality, not just a low-cost estimate.
Having an insurance broker means you have a dedicated advocate during what is often a highly stressful time. When you’re dealing with the emotional and financial fallout of a trashed investment, we step in to handle the heavy lifting. We navigate the complex Australian insurance market on your behalf, ensuring your claim is presented accurately and fairly to the insurer. This long-term relationship fosters a sense of security and local accessibility that a faceless call centre simply cannot provide. It turns a high-friction experience into one that feels managed and certain.
Moving Beyond Automated Quotes for Better Protection
It’s a common misconception that all policies are created equal, but automated quotes can leave your assets exposed when policy definitions are tight. At MyGen Insurance Brokers, we conduct manual reviews of every policy to ensure the malicious damage by tenant insurance cover actually fits your specific property needs. We encourage you to look past the initial premium price to find the true value of your protection. By choosing a partner who values depth over speed, you’re not just buying a piece of paper; you’re securing a simplified outcome where your investment is truly protected by experts who care about your long-term success.
Protecting Your Investment for the Long Term
We’ve explored how a deep understanding of policy wording and meticulous documentation can turn a potential financial disaster into a manageable recovery. It’s clear that relying on generic, automated quotes often leaves gaps that only become visible when it’s too late. By securing robust malicious damage by tenant insurance cover, you aren’t just buying a policy; you’re investing in the certainty that your property portfolio is truly shielded. We take a consultative approach to identify your specific risks and act as your expert advocate during the claims process, offering access to specialised policies you won’t find on standard comparison sites.
Speak with a MyGen broker for a personalised landlord risk assessment today. You’ve worked hard to build your legacy, and we’re here to help you protect it with the diligence it deserves.
Frequently Asked Questions
Does landlord insurance cover damage caused by a tenant’s guests?
Most comprehensive landlord policies extend coverage to damage caused by guests, provided they were on the premises with the tenant’s consent. If the damage is deemed intentional, it typically triggers the malicious damage by tenant insurance cover section of your policy. It’s important to verify whether your specific wording includes invitees, as some budget-friendly options might limit claims solely to the individuals listed on the tenancy agreement.
Is a police report always required for a malicious damage claim in Australia?
In Australia, a police report is a standard requirement for any claim involving malicious acts. Because malicious damage is technically a criminal offence, insurers rely on a police event number to validate the claim’s legitimacy. Providing this report helps prove that the damage was a result of a hostile act rather than simple neglect, which is a crucial step in moving your claim toward a successful resolution.
What is the difference between malicious damage and deliberate damage?
The distinction lies in the intent behind the action. Deliberate damage involves an intentional act, like painting a room without permission, where the motive isn’t necessarily to devalue the property. Malicious damage occurs when a tenant purposefully sets out to cause harm or destruction. Understanding this difference is vital, as many insurers use these specific definitions to decide which excess applies to your malicious damage by tenant insurance cover.
Can I claim for loss of rent if my property is uninhabitable due to malicious damage?
You can often claim for loss of rent if the damage is severe enough to make the property unliveable. This benefit provides a financial safety net while licensed tradespeople carry out necessary repairs. However, coverage limits vary significantly between insurers. We suggest reviewing your policy to confirm the maximum duration of rent replacement, ensuring you aren’t left out of pocket while your investment is being restored.