
The right insurance for allied health professionals isn’t a one-size-fits-all checklist. A practitioner treating clients in a clinic may face different exposures from someone providing home visits, telehealth or services as part of a larger practice. Professional indemnity and public liability are common considerations, while business and cyber cover may also be relevant to how you work.
To assess whether a policy suits your practice, compare its wording, limits and exclusions with the services you provide and the way you work. This guide outlines the main professional and business risks to consider, explains what to review in policy documents and gives you practical steps for comparing cover. A clear picture of your work can help you have a more focused discussion about suitable insurance options.
Key Takeaways
- Insurance for allied health professionals should reflect the services you provide and how your practice operates, rather than follow a generic checklist.
- Map your work settings and client interactions to identify exposures linked to advice, treatment, records, premises or mobile services.
- Assess professional indemnity and public liability as distinct types of cover, then compare policy wording, limits and exclusions against your risks.
- Review your services, business structure and work locations to clarify which business insurance options may suit your practice.
Insurance for allied health professionals: understand the risks behind your work
Clinical work, client contact and running a practice can each create different exposures. A practitioner giving exercise advice in a clinic may have different considerations from one providing hands-on treatment at a client’s home or managing appointments and records through telehealth. The broad range of allied health professions helps explain why a single checklist may not suit every practice.
Suitable cover depends on the services you provide and how your practice operates. Start by noting where you see clients, whether you use treatment equipment, how you store records and whether you travel between locations. These details help separate risks linked to your professional services from other risks involved in operating a business.
How allied health services can create different business risks
A complaint alleging that advice or treatment caused harm raises different considerations from an accident in which a client is injured on your premises or their property is damaged during a visit. Professional indemnity and public liability address different types of exposure, subject to each policy’s terms. Neither should be assumed to respond to every circumstance.
Your work arrangements also matter. A private practice may need to consider its premises and equipment. Shared rooms can involve common areas, while home visits bring you into another person’s environment. Telehealth changes how services are delivered and makes the handling of client information an important part of a risk review.
Before deciding what cover to consider, list your services, client interactions and work locations. Then verify any insurance requirements that apply to your profession, contracts or regulatory obligations with the relevant body. Requirements can vary, so don’t assume another practitioner’s arrangements will suit your work.
How to assess insurance for allied health professionals and compare cover
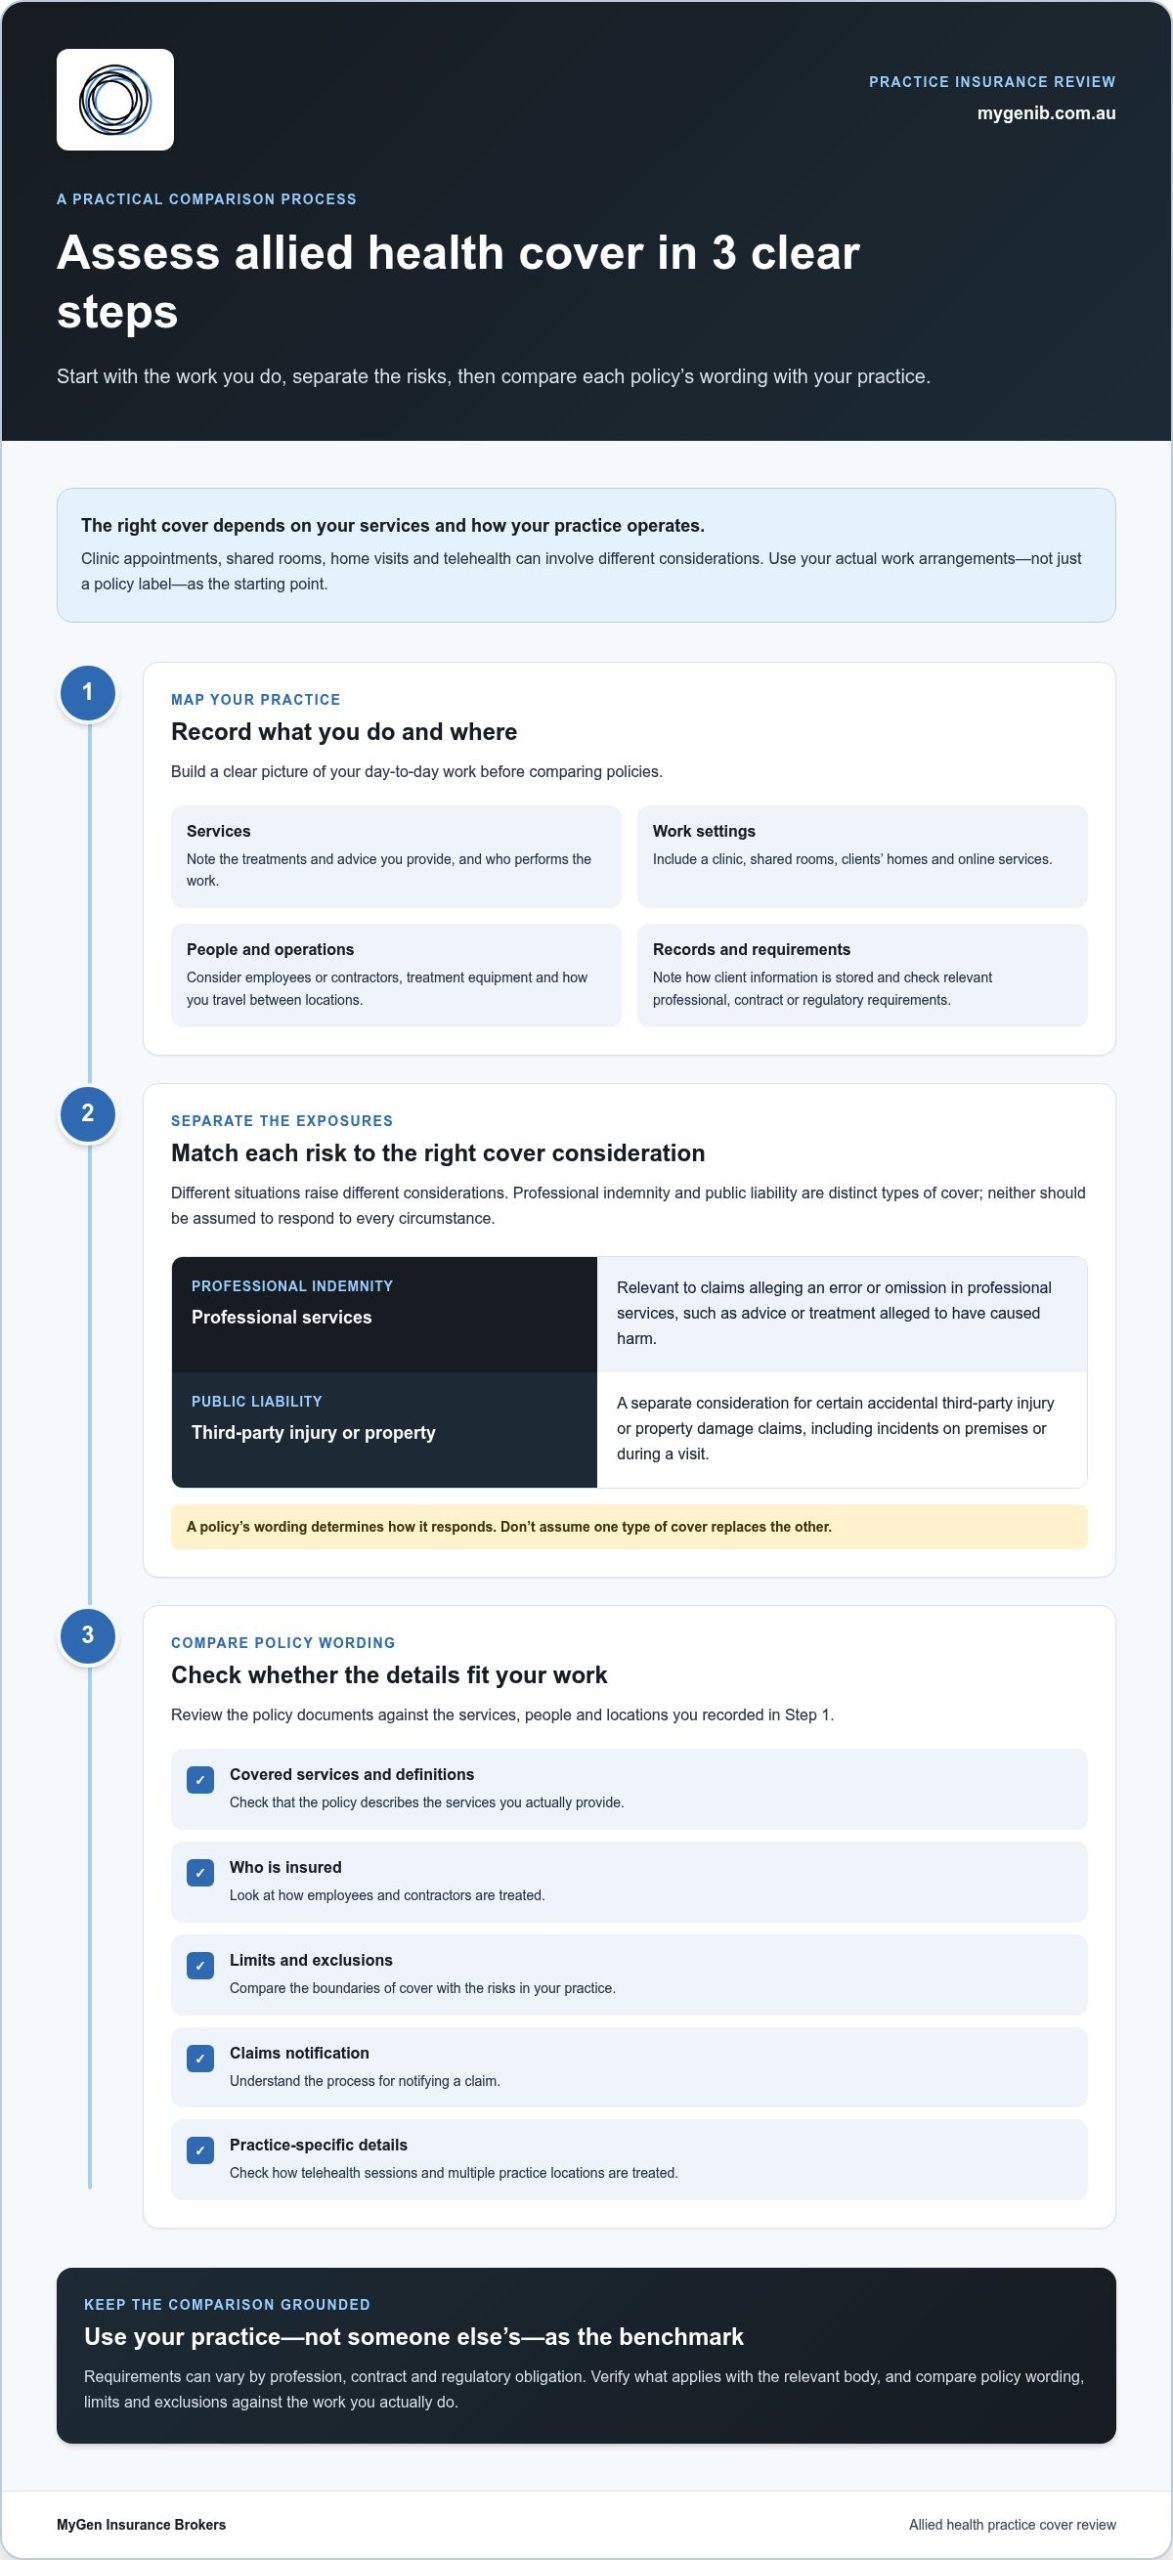
A useful comparison starts with your actual practice, not just the policy name. Work through these steps:
- Map your services and work settings. Note the treatments and advice you provide, who performs the work, and whether you operate from a clinic, shared rooms, clients’ homes or online.
- Identify the exposures. Consider allegations related to professional advice or treatment separately from accidental injury to a third party or damage to their property.
- Compare the wording. Check how each policy describes covered services, who is insured, the limits and exclusions, and the process for notifying a claim.
Professional indemnity insurance is relevant to claims alleging an error or omission in professional services. Public liability is a separate consideration for certain third-party injury or property damage claims. The policy wording determines how each responds, so don’t assume one replaces the other. For further context on the first cover type, see this professional indemnity insurance guide.
Compare policy limits, exclusions and definitions against the work you actually do, rather than relying on a policy label alone. Industry context from Allied Health Professions Australia (AHPA) can also help frame the range of allied health practice in Australia.
Which policy details deserve a closer look?
Check that the insured services reflect your work, then review key definitions, exclusions, limits and claims notification terms. Look specifically at how the policy treats contractors or employees, telehealth sessions and multiple practice locations. These details can differ between policies. Also consider operational exposures alongside professional risks. This Australian business insurance guide outlines broader considerations, including how business insurance can relate to your practice. MyGen Insurance Brokers takes a personalised approach to reviewing business risks and insurance options. To discuss your circumstances, talk with MyGen about your business insurance needs.
Get tailored insurance for allied health professionals with a considered review
A useful review begins with the details of your practice: the services you provide, your business structure, how clients interact with you and where the work takes place. A sole practitioner working across several locations may have different considerations from a clinic owner with staff or contractors. A broker can use this information to consider professional indemnity alongside relevant business insurance, without assuming every practice needs the same combination of cover.
MyGen takes a personalised approach to understanding business risks and arranging insurance solutions. The process connects your working arrangements with relevant policy options, then considers the wording and boundaries of that cover. For more on the value of a considered brokerage conversation, see this business insurance broker guide.
What to prepare for a business insurance discussion
A short overview can keep the conversation focused. List the services you provide, where you see clients and how staff or contractors contribute to the work. Include relevant contractual insurance requirements, and gather your current policy documents so your existing cover can be considered alongside your present arrangements.
It can also help to note questions about exclusions, limits or changes to your practice, such as adding a service or location. A clear overview of your risks helps make a policy discussion more focused and useful. This is particularly helpful when policy documents use terms that are difficult to relate to your day-to-day work.
You don’t need to have every answer before starting. To discuss insurance for allied health professionals in the context of your practice, talk with MyGen about your business risks and the cover options worth considering.
Keep your cover aligned as your practice evolves
Your work can change as you add services, adjust how clients access care or grow your team. Treat insurance for allied health professionals as an ongoing business decision. Review your cover when your practice changes rather than relying on assumptions made when you first arranged it.
MyGen’s personalised, consultative approach focuses on understanding your business risks and relating them to relevant insurance options. Anthony Simpson brings more than 20 years of industry experience to that process, helping make a complex review clearer and more considered.
A confident next step starts with a conversation grounded in the way you actually work. Start a tailored business insurance review with MyGen and take a considered approach to your practice’s next stage.
Frequently Asked Questions
Is insurance legally required for allied health professionals in Australia?
For practitioners registered with AHPRA, appropriate professional indemnity insurance arrangements are a registration requirement. Cover needs to be appropriate to the practitioner’s scope of practice, and some professional boards set specific requirements. Allied health roles aren’t all regulated in the same way, so check the relevant registration body, professional association and any applicable contract for requirements that apply to your work.
Does allied health insurance cover telehealth services?
It can, but don’t assume a policy covers every service delivered online. Check whether telehealth is included in the insured professional services and whether conditions apply to the type of advice or treatment provided. If you add video consultations to an in-person service, for example, make sure the policy reflects that change and review any relevant exclusions.
Are contractors covered by a clinic’s allied health insurance?
Not necessarily. A clinic policy may cover the business without covering every contractor’s professional work, or it may define who is insured in a specific way. Review the policy schedule and wording alongside each contractor’s agreement and responsibilities. A contractor should understand whether they need their own cover rather than relying on the clinic’s arrangements.
Can one insurance policy cover an allied health practice and its practitioners?
One insurance arrangement may include cover for a practice and specified practitioners, but the policy documents determine who is insured and for which activities. Check that the business entity and relevant people are identified, and that the insured services and limits suit the arrangement. Assess insurance for allied health professionals against the practice structure rather than assuming it applies to everyone automatically.