
For insurance for cafe and restaurant owners, the right starting point is understanding how your venue operates and what it relies on to keep trading. A customer injury, kitchen fire or failed fridge can disrupt service and put pressure on your venue’s finances.
It’s understandable to want a quick answer, but cover should reflect your venue’s activities, premises and equipment. A café with takeaway service, a full-service restaurant and a venue with outdoor dining can face different risks, so a generic checklist may miss important details. This guide explains the main risks to review and the business insurance areas you may want to discuss, from liability and property to equipment and business interruption. MyGen Insurance Brokers reviews business risks, designs and sources customised packages, and supports clients through the policy period and claims process. MyGen is a member of the National Insurance Brokers Association and a subscriber to its Code of Practice. All services are subject to the terms and conditions on MyGen’s website.
Key Takeaways
- Insurance for cafe and restaurant owners should reflect your venue’s operations, premises, equipment and potential interruptions, not just its business type.
- Map your key risks first, then consider relevant areas such as liability, asset protection and business interruption.
- MyGen reviews venue risks, designs and sources a tailored package, and provides support during the policy period and claims process.
- MyGen is a NIBA member and subscriber to the NIBA Code of Practice. All services are subject to the terms and conditions on its website.
Insurance for cafe and restaurant owners: understand the risks behind the cover
A busy venue brings several responsibilities together: serving customers, maintaining the premises, relying on equipment and keeping the business running. Insurance for cafe and restaurant owners is best considered against these actual exposures, rather than selected by business label alone. A takeaway café, a restaurant with table service and a venue offering outdoor dining may have different activities, assets and interruption concerns.
Three areas can help organise an initial review. Liability insurance relates to claims involving injury or property damage. Asset protection focuses on business property and general property, including tools of trade and equipment, as well as theft, glass and machinery. Business interruption insurance is another area to discuss when considering how an insured event could affect trading and ongoing expenses. These categories do not guarantee that a particular loss will be covered. Policy wording, limits, exclusions and conditions determine how a policy responds.
Which cafe and restaurant risks deserve an insurance review?
Start with the way the venue runs, then connect each part of the operation to a practical question:
- Customer-facing activities: What happens across dine-in, takeaway, delivery or outdoor service, and where could a liability claim arise?
- Premises: Which areas are leased or owned, and what property or fit-out does the business rely on?
- Equipment and assets: Which kitchen, refrigeration, payment or service equipment would be difficult to operate without?
- Trading disruption: If an insured event affected the premises, what costs could continue while the venue recovers?
These questions help identify where liability, asset protection and business interruption may warrant closer discussion. They also give a broker a clearer picture of the venue’s circumstances before considering policy options. For general background on the framework, see this overview of Australian insurance law. For decisions about a specific policy, refer to its applicable documents and terms rather than relying on a broad summary of insurance rules.
How to assess insurance needs for your cafe or restaurant
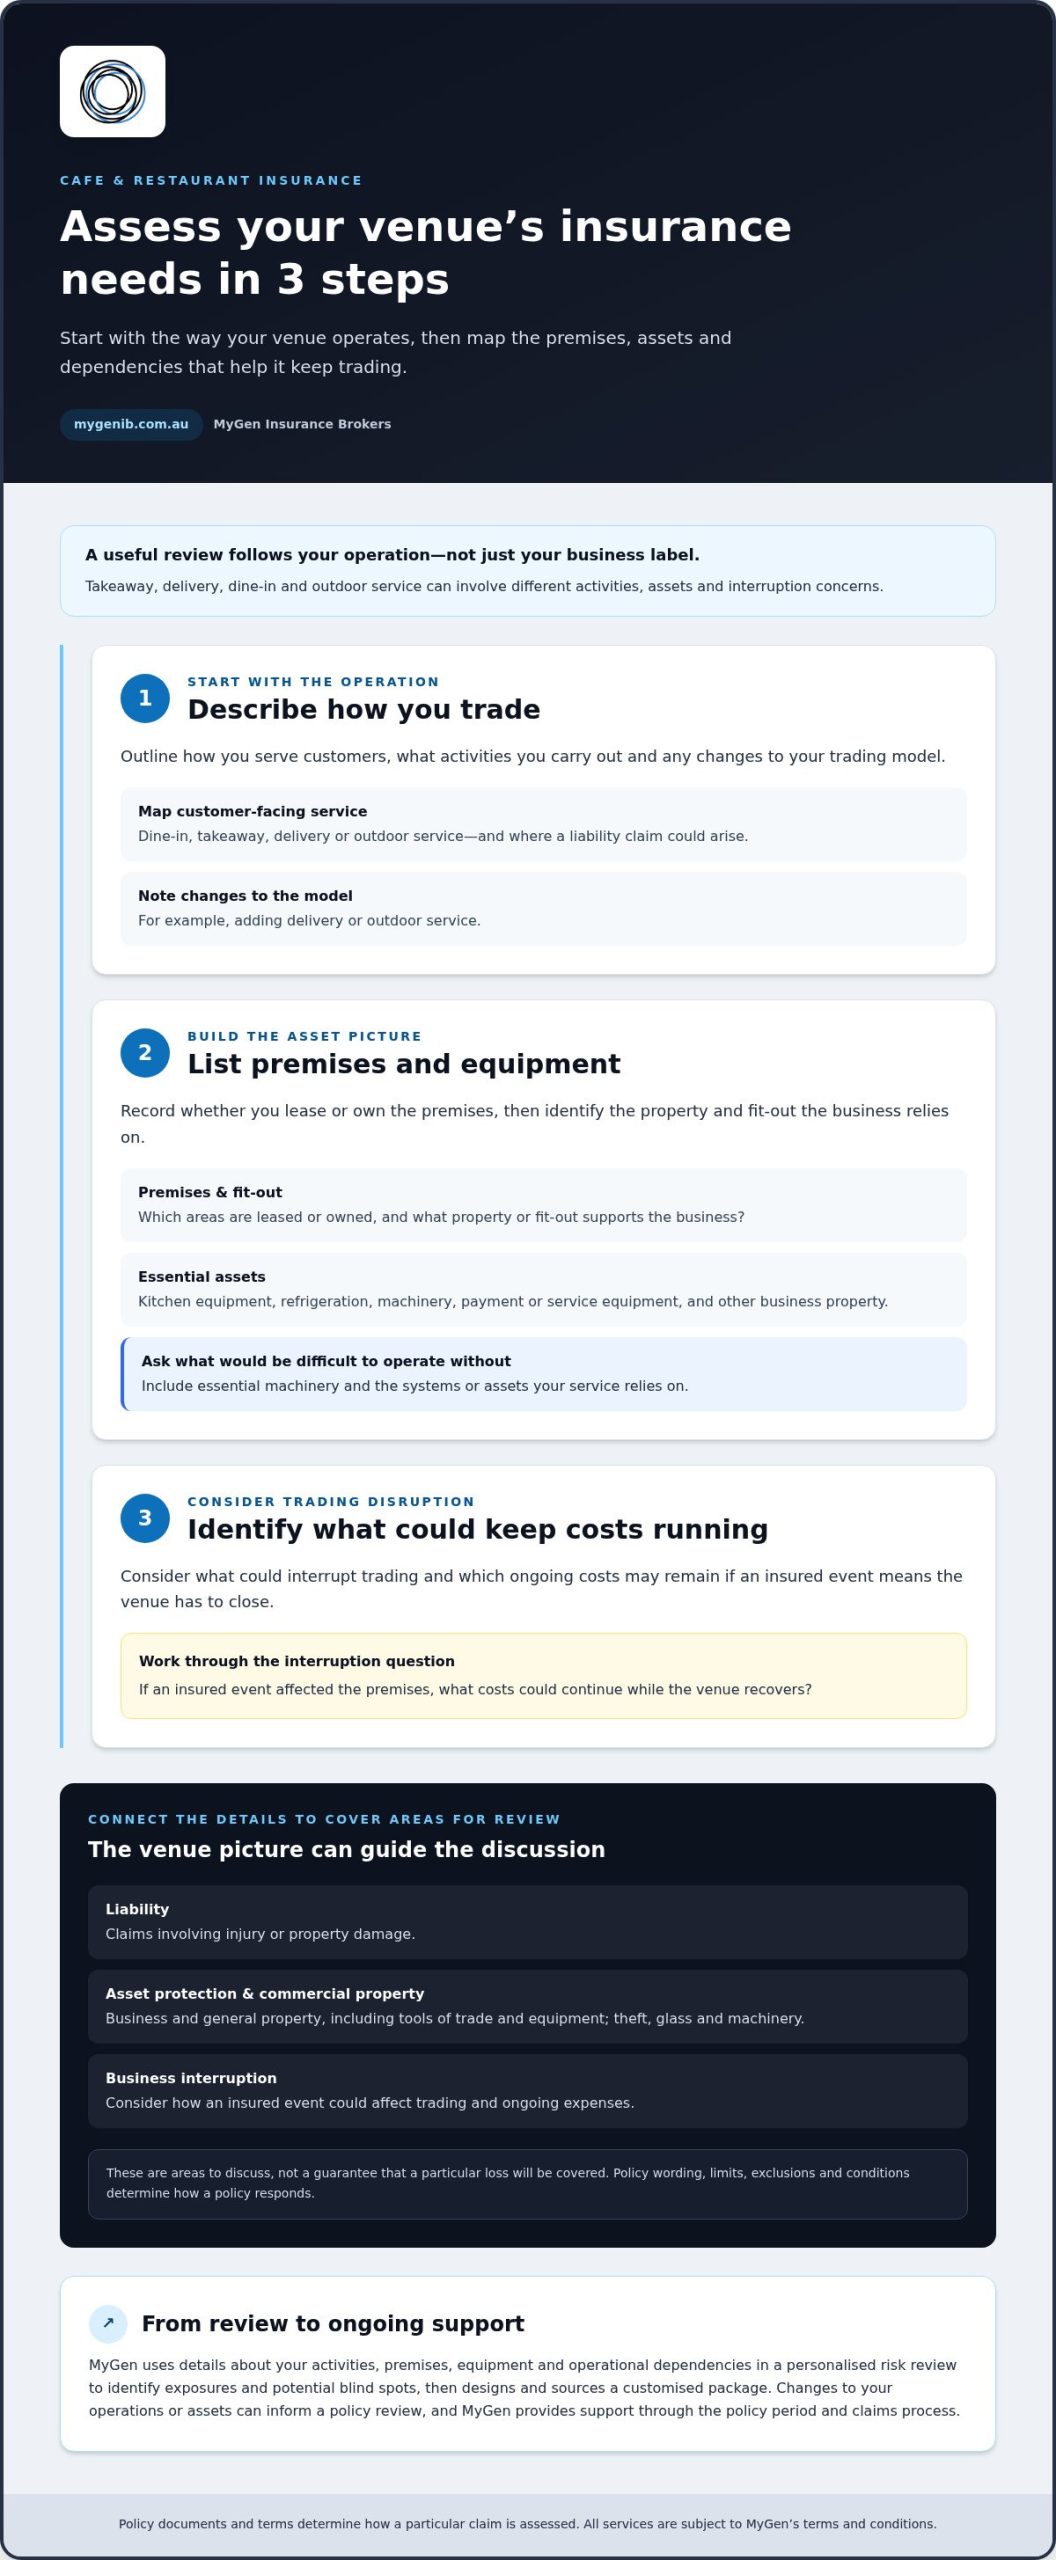
A practical review starts with the way your venue operates, then works outwards to the property, equipment and dependencies that keep it trading. This sequence gives you a clearer basis for discussing insurance for cafe and restaurant owners than choosing cover from a generic checklist.
- Describe your operations. Note how you serve customers, the activities you carry out and any changes to your trading model, such as adding delivery or outdoor service.
- List premises and assets. Record whether you lease or own the premises, along with the fit-out, kitchen equipment, refrigeration and other business property you rely on.
- Identify disruption concerns. Consider what could interrupt trading and which ongoing costs may remain if the venue has to close following an insured event.
These details help connect your venue’s circumstances with areas to review, including liability, asset protection, commercial property and business interruption. The relevant cover, limits, exclusions and conditions depend on the applicable policy documents, so a category name alone can’t establish how a claim will be handled.
What information helps build a more relevant insurance review?
Bring together a clear outline of your activities, premises, equipment and operational dependencies. Include details such as leased spaces, essential machinery and the systems or assets your service relies on. MyGen uses this information in a personalised risk review to identify exposures and potential blind spots before designing and sourcing a customised package.
For broader context on how business cover can be considered, explore the Australian business insurance guide. If you’d like a review shaped around your venue’s operations and assets, discuss a tailored business insurance review with MyGen. All services are subject to the terms and conditions available on its website.
From risk review to ongoing support: working with MyGen
A useful insurance review should continue beyond choosing a package. MyGen considers your venue’s operations, property and equipment, then uses that picture to identify relevant risks and design and source a customised package. This makes the discussion specific to your business, rather than relying on a quick quote alone.
Support can continue through the policy period and claims process. If your venue’s operations or assets change, that information can inform a policy review. If an incident leads to a claim, MyGen provides claims assistance to help you navigate the process. Policy wording and conditions determine how a particular claim is assessed.
What does a tailored broker relationship add?
Insurance discussions can raise detailed questions about activities, assets, limits and exclusions. An experienced broker can help you work through those points, explain relevant options and keep the review grounded in the way your venue operates. MyGen brings more than 20 years of industry experience to this work. Its approach to expert insurance broker guidance explores the value of individual advice alongside digital options.
MyGen is a member of the National Insurance Brokers Association (NIBA) and a subscriber to the NIBA Code of Practice. For insurance for cafe and restaurant owners, a considered review and ongoing assistance can make policy discussions clearer. You can speak with MyGen about your business insurance. All services are subject to the company’s terms and conditions, available on its website.
Make your next insurance review a considered one
A planned menu or service change, a new piece of equipment or an approaching renewal can be a useful prompt to revisit your cover. Keep a brief record of changes and questions as they arise. This gives your broker a clearer starting point for discussing insurance for cafe and restaurant owners without adding another daily task during a busy service period.
MyGen brings 20+ years of industry experience and provides ongoing support through the policy period and claims process. It’s a member of the National Insurance Brokers Association (NIBA) and a subscriber to the NIBA Code of Practice. Discuss a tailored insurance review with MyGen to consider your venue’s risks and insurance needs. All services are subject to the terms and conditions available on MyGen’s website.
Frequently Asked Questions
Does cafe insurance cover food spoilage after equipment breaks down?
Not automatically. Spoiled stock after a fridge or freezer failure is covered only if the relevant policy wording and circumstances provide for it. Review how the policy treats machinery failure and stock loss, including exclusions and conditions, rather than assuming one type of cover triggers another. MyGen can discuss this in a tailored business insurance review. All services are subject to the terms and conditions on its website.
Can a home-based catering business get insurance for its operations?
A home-based catering business can include its activities in a business insurance review. The relevant options depend on its operations, assets and applicable policy terms. Explain whether food is prepared at home, transported to events or served at customers’ premises, and identify the equipment used. MyGen can review relevant liability and asset protection options, with the applicable policy wording determining how cover responds.
What happens if my cafe’s operations change after I arrange insurance?
Discuss the change with your broker so your circumstances and insurance needs can be reviewed. Adding catering, delivery, outdoor seating or new equipment may affect the activities and assets considered. MyGen can review the updated information, but whether a policy responds to a claim depends on its wording, conditions and terms. All services are subject to the company’s terms and conditions, available on its website.
Can one business insurance package include property and liability cover?
Yes, a customised package may include both, depending on the business’s circumstances and the structure of the applicable policies. For insurance for cafe and restaurant owners, a review can consider the venue’s physical assets alongside its customer-facing risks. Read the relevant policy documents for applicable limits, exclusions and conditions, and don’t assume every business package combines cover in the same way.