
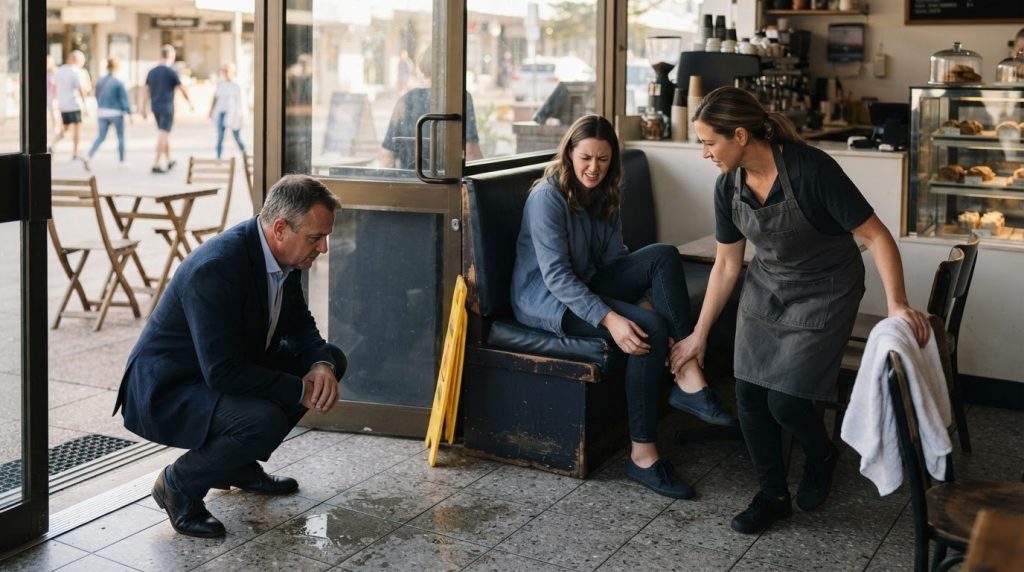
A business insurance package can include public liability, but that does not automatically make it suitable for a café or restaurant. Public liability for restaurants and cafes may cover claims alleging that business activities caused a third party’s injury or property damage, and may include legal expenses. The policy limits, exclusions and treatment of food-related claims all matter.It is easy to assume one package covers every risk under one roof. Look beyond the package label: public liability generally addresses claims from customers or suppliers, while employee injuries are handled separately through workers’ compensation. Lease conditions may also specify a minimum level of cover.This guide explains the difference between public and products liability, the incidents that may lead to a claim, and what to consider when assessing cover for your premises, food and service. It also clarifies where business insurance fits and which policy details to review. Key Takeaways Identify how your lease, outdoor dining arrangements and catering or delivery activities can affect the cover your business needs. Look beyond a business package label: policy limits, exclusions and food-related cover determine what protection may apply. Understand how public and products liability relate to customer injuries, property damage and claims involving food or services. Consider how your premises, menu and day-to-day operations shape the risks that matter when arranging business insurance. Table of Contents If I work in the catering industry, what insurance should I consider? Isn’t public liability insurance included in my business insurance package? Public and products liability for restaurants and cafes MyGen Insurance Brokers If I work in the catering industry, what insurance should I consider? Restaurants and caterers should consider liability insurance alongside cover for their premises, equipment, vehicles and income. The right combination depends on where food is served, how it reaches customers, and any lease or permit conditions.Cover for leased premises and catering Insurance for leased premises and catering should reflect both the fixed site and work carried out elsewhere. A lease may specify minimum public liability and glass cover, while delivery or off-site catering extends the business’s activities beyond its premises. A business package may also cover equipment breakdown, theft or interruption after an insured event such as fire. Commercial motor cover is a separate consideration for delivery vehicles.Legal and contractual insurance requirements Public liability insurance requirements can come from council permits, leases and commercial contracts, rather than one condition applying to every restaurant. For example, North Sydney Council’s outdoor dining requirements list at least A$10 million in public liability cover, or A$20 million for areas within State road areas. Landlords may also require a minimum level of liability or glass cover in … [Read more...] about Public Liability for Restaurants and Cafes: What’s Covered
Café & Restaurant Insurance: A Practical Australian Guide
For insurance for cafe and restaurant owners, the right starting point is understanding how your venue operates and what it relies on to keep trading. A customer injury, kitchen fire or failed fridge can disrupt service and put pressure on your venue’s finances.It’s understandable to want a quick answer, but cover should reflect your venue’s activities, premises and equipment. A café with takeaway service, a full-service restaurant and a venue with outdoor dining can face different risks, so a generic checklist may miss important details. This guide explains the main risks to review and the business insurance areas you may want to discuss, from liability and property to equipment and business interruption. MyGen Insurance Brokers reviews business risks, designs and sources customised packages, and supports clients through the policy period and claims process. MyGen is a member of the National Insurance Brokers Association and a subscriber to its Code of Practice. All services are subject to the terms and conditions on MyGen’s website. Key Takeaways Insurance for cafe and restaurant owners should reflect your venue’s operations, premises, equipment and potential interruptions, not just its business type. Map your key risks first, then consider relevant areas such as liability, asset protection and business interruption. MyGen reviews venue risks, designs and sources a tailored package, and provides support during the policy period and claims process. MyGen is a NIBA member and subscriber to the NIBA Code of Practice. All services are subject to the terms and conditions on its website. Table of Contents Insurance for cafe and restaurant owners: understand the risks behind the cover How to assess insurance needs for your cafe or restaurant From risk review to ongoing support: working with MyGen Insurance for cafe and restaurant owners: understand the risks behind the cover A busy venue brings several responsibilities together: serving customers, maintaining the premises, relying on equipment and keeping the business running. Insurance for cafe and restaurant owners is best considered against these actual exposures, rather than selected by business label alone. A takeaway café, a restaurant with table service and a venue offering outdoor dining may have different activities, assets and interruption concerns.Three areas can help organise an initial review. Liability insurance relates to claims involving injury or property damage. Asset protection focuses on business property and general property, including tools of trade and equipment, as well as theft, glass and machinery. Business interruption insurance is another area to discuss when considering how an insured event could affect trading and ongoing expenses. These categories do not guarantee that a particular loss will be covered. Policy wording, limits, exclusions and conditions determine how a policy responds.Which cafe and restaurant risks deserve an insurance review? Start with the way … [Read more...] about Café & Restaurant Insurance: A Practical Australian Guide

Business Insurance for the Hospitality Industry in Australia: Navigating Exclusions in 2026
What if the insurance policy you rely on to protect your restaurant is actually designed to stay silent when you need it most? You've likely spent hours squinting at dense Product Disclosure Statements, only to feel that these automated, generic policies don't truly understand the heat of your kitchen or the specific risks of your front-of-house team. It's a common frustration in our industry. You want to focus on your guests, yet the fear of a rejected claim during a crisis remains a heavy weight on your shoulders. We're here to help you find clarity and pull back the curtain on the critical exclusions within business insurance for hospitality industry australia for 2026. This guide will show you how to identify the hidden gaps in your coverage, from navigating evolving regulatory changes and rising operational costs across the sector to managing new biosecurity and public health risks. By the end of this article, you'll have a clear roadmap to move from policy confusion to absolute confidence, ensuring your cafe, bar, or restaurant is protected by more than just a standard template. Key Takeaways Understand why specific exclusions are built into your policy to keep premiums manageable while still protecting your venue from catastrophic losses. Learn to distinguish between sudden, accidental damage and standard wear and tear so you can manage your kitchen maintenance and insurance claims effectively. Discover how the right business insurance for hospitality industry australia can be tailored to cover gaps that generic, automated policies often overlook. Identify the universal exclusions around staff negligence and intentional acts to better protect your restaurant or bar from internal risks. Explore the vital role of a specialist broker in negotiating "write-backs" to restore essential coverage that is typically removed in standard contracts. Table of Contents Understanding Hospitality Insurance Exclusions in the Australian Market The Most Common Exclusions in Hospitality Policy Types Bridging the Hospitality Coverage Gap with a Consultative Broker Understanding Hospitality Insurance Exclusions in the Australian Market In the Australian hospitality sector, an insurance exclusion is a specific provision within your policy that removes coverage for certain hazards. While it might feel like a "gotcha" moment when a claim is denied, these boundaries actually serve a practical purpose. By removing high-frequency, uninsurable risks, insurers can keep premiums manageable for small cafes and family-run restaurants. Without these limits, the cost of business insurance for hospitality industry australia would likely be out of reach for many local operators. Understanding how Insurance in Australia is regulated helps clarify why the Product Disclosure Statement (PDS) is so vital. This document isn't just paperwork; it's a legal requirement that outlines exactly where your protection starts and ends. You also have a "Duty of Disclosure," which … [Read more...] about Business Insurance for the Hospitality Industry in Australia: Navigating Exclusions in 2026