
A business insurance package can include public liability, but that does not automatically make it suitable for a café or restaurant. Public liability for restaurants and cafes may cover claims alleging that business activities caused a third party’s injury or property damage, and may include legal expenses. The policy limits, exclusions and treatment of food-related claims all matter.
It is easy to assume one package covers every risk under one roof. Look beyond the package label: public liability generally addresses claims from customers or suppliers, while employee injuries are handled separately through workers’ compensation. Lease conditions may also specify a minimum level of cover.
This guide explains the difference between public and products liability, the incidents that may lead to a claim, and what to consider when assessing cover for your premises, food and service. It also clarifies where business insurance fits and which policy details to review.
Key Takeaways
- Identify how your lease, outdoor dining arrangements and catering or delivery activities can affect the cover your business needs.
- Look beyond a business package label: policy limits, exclusions and food-related cover determine what protection may apply.
- Understand how public and products liability relate to customer injuries, property damage and claims involving food or services.
- Consider how your premises, menu and day-to-day operations shape the risks that matter when arranging business insurance.
If I work in the catering industry, what insurance should I consider?
Restaurants and caterers should consider liability insurance alongside cover for their premises, equipment, vehicles and income. The right combination depends on where food is served, how it reaches customers, and any lease or permit conditions.
Cover for leased premises and catering
Insurance for leased premises and catering should reflect both the fixed site and work carried out elsewhere. A lease may specify minimum public liability and glass cover, while delivery or off-site catering extends the business’s activities beyond its premises. A business package may also cover equipment breakdown, theft or interruption after an insured event such as fire. Commercial motor cover is a separate consideration for delivery vehicles.
Legal and contractual insurance requirements
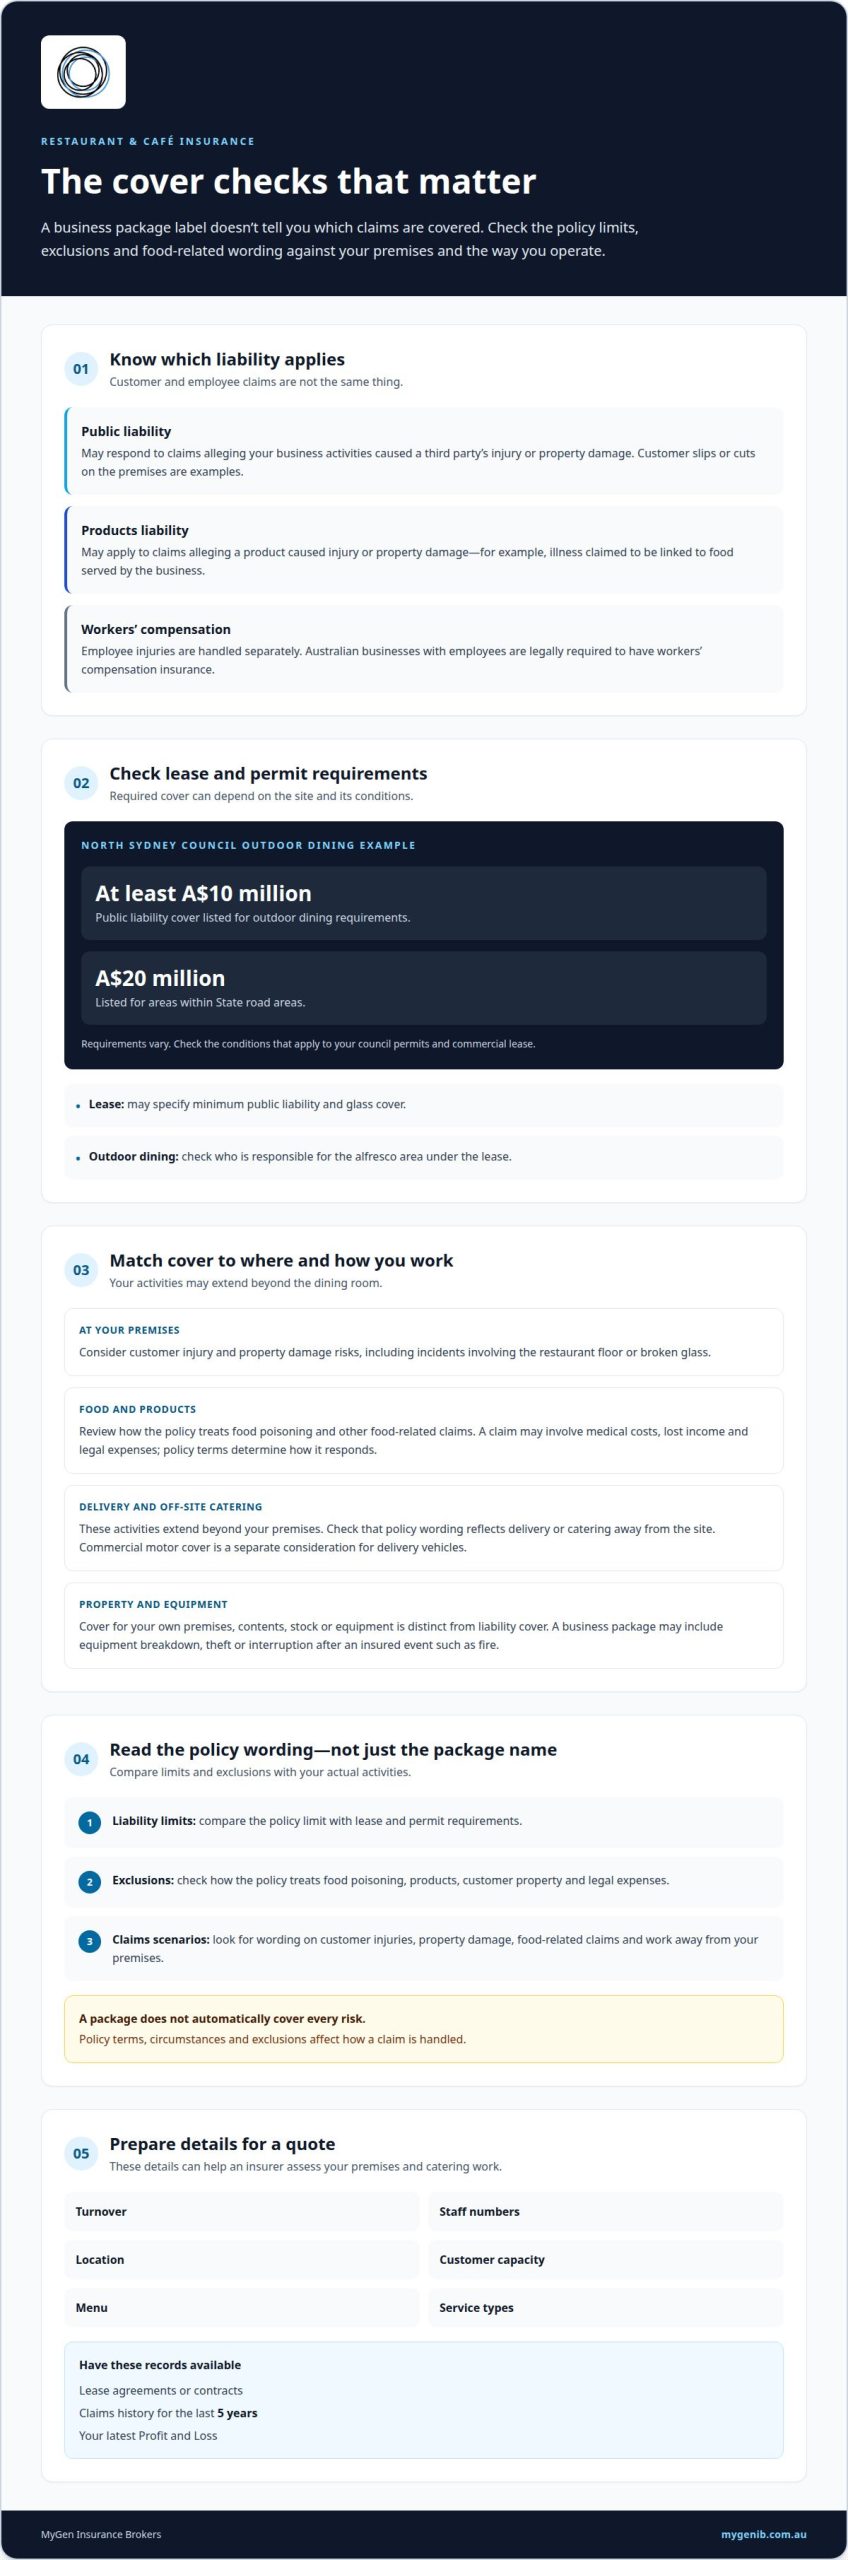
Public liability insurance requirements can come from council permits, leases and commercial contracts, rather than one condition applying to every restaurant. For example, North Sydney Council’s outdoor dining requirements list at least A$10 million in public liability cover, or A$20 million for areas within State road areas. Landlords may also require a minimum level of liability or glass cover in the lease. Employees’ injuries are a separate matter: Australian businesses with employees are legally required to have workers’ compensation insurance.
Comparing public liability policies
Compare policies by checking their liability limits and exclusions against your lease, permits and actual activities. Look for wording on food-related claims, customer injuries, property damage, and delivery or catering away from your premises. If your café has an alfresco area, consider who is responsible for it under the lease. These details reveal differences that a policy label alone cannot.
Getting a public liability quote
For a quote, prepare details of your turnover, staff numbers, location, customer capacity, menu and service types. These factors can affect premiums, alongside the minimum cover required by a lease. Keep lease agreements or contracts, claims history for the last 5 years, and your latest Profit and Loss available. Clear records help an insurer assess the risks of your particular premises and catering work.
Isn’t public liability insurance included in my business insurance package?
Some business insurance packages include basic liability cover, but the package name does not tell you which claims are covered or what limits apply. For a restaurant, review the liability wording alongside cover for property and equipment.
Public and products liability cover
Public and products liability can respond to claims alleging that business activities or products caused injury or property damage. A customer might claim illness after food poisoning, for example, or a supplier might claim damage to their property. Some packages include basic liability insurance, but limits and food-related exclusions vary. Read the policy wording to understand which claims are covered and how liability fits with your other insurance.
Cover for customer injury claims
A customer injury claim might follow a slip on the restaurant floor, a cut from broken glass or illness linked to food. Public liability insurance may cover compensation costs and legal expenses if the business faces a claim. It does not cover every incident automatically: the policy terms, circumstances and exclusions affect how a claim is handled. Employee injuries are addressed separately through workers’ compensation.
Choosing an appropriate cover limit
There is no single public liability limit that suits every Australian café or restaurant. The amount may depend on turnover, staff numbers, location and the minimum cover required by a commercial lease or permit. A business with outdoor dining, for instance, may need to meet council permit conditions as well as its landlord’s lease requirements. Compare the required limit with the policy limit, then check that the wording reflects your operations and customer exposure.
Policy exclusions for food businesses
Exclusions are policy-specific, so don’t assume every food-related claim is covered. Review the wording for how it treats food poisoning, products, customer property and legal expenses. A business pack may separately cover premises and contents against events such as fire, storm or accidental damage, and may include equipment breakdown cover. That property protection is distinct from liability cover. An insurance review can help clarify how the sections fit together.
Public and products liability for restaurants and cafes
Public and products liability is designed to address claims alleging that a business’s negligent actions or products caused personal injury or property damage. Public liability for restaurants and cafes can therefore involve different situations: a customer might allege an injury at the venue or illness caused by food served there. The policy wording defines the scope of cover, including applicable limits and exclusions.
A claim can involve more than compensation. An allegation of food poisoning, for example, may involve medical costs, lost income and legal expenses. Public liability for restaurants and cafes may help with the cost of defending a claim, but the policy terms and circumstances determine how it responds. A café and takeaway operated by the same legal entity can generally be covered under the same policy.
- Customer injury: A slip or cut on the premises could lead to a personal injury claim.
- Products: A claim may arise if food served by the business is alleged to have caused illness.
- Property damage: A customer’s or supplier’s property may be damaged through business activities.
This cover is distinct from protection for the restaurant’s own contents, stock or equipment. Employee injuries are also handled separately through workers’ compensation, not public liability. Review the wording for limits, exclusions and how it treats claims involving food, services and property damage. If your venue also operates a takeaway under the same legal entity, make sure both activities are accurately described.
For cover that reflects your hospitality operations, discuss business insurance options suited to your circumstances.
MyGen Insurance Brokers
MyGen Insurance Brokers helps hospitality operators understand how insurance may respond to their business risks. If your café serves food on-site, caters elsewhere, delivers orders or operates under a commercial lease, those details can shape the cover you need.
Through Business Insurance, MyGen takes a consultative approach to understanding your operations and identifying relevant risks. This can help clarify how liability fits alongside other business needs, rather than relying on a package label alone. It is a useful step when arranging cover, renewing a policy or changing how your restaurant operates.
Contact MyGen Insurance Brokers to discuss your restaurant or café’s insurance needs.
Make your next business change with cover in mind
A new menu, catering arrangement or delivery service can change the risks attached to your operations. Include insurance in your planning so discussions about cover reflect how the business actually works. Choosing public liability for restaurants and cafes is one part of that wider review.
MyGen Insurance Brokers takes a consultative approach to understanding business risks and recommending suitable insurance solutions. Its offerings include Business Insurance, Professional Indemnity Insurance and Commercial Motor Insurance, which may address different aspects of your operations. Start with a clear conversation about what your business does and where its risks lie.
For a considered next step, contact MyGen Insurance Brokers to discuss your business insurance needs. A clearer picture of your risks can help you move forward with greater confidence.
Frequently Asked Questions
What is restaurant insurance?
Restaurant insurance combines policies selected for a hospitality business’s risks. Public liability for restaurants and cafes may be one part, alongside cover for business property, contents, stock or equipment. A venue that owns kitchen machinery, for example, may consider equipment protection, while one using a delivery van faces different vehicle risks. Policy wording determines what each section covers.
What is Covered?
Cover depends on the policy, but public and products liability can address claims involving third-party injury or property damage linked to business activities or products. A business package may separately protect the venue’s own contents or equipment against insured events. Damage to a customer’s belongings and damage to a café’s furniture, for example, involve different types of cover.
Am I covered if the incident happens outside my premises, like in the car park or alfresco area?
Cover for a car park or alfresco area depends on whether your business is responsible for that space or it forms part of your lease. A customer’s fall in an outdoor dining area, for example, may raise questions about who controls and maintains it. The policy wording and lease help establish how the area relates to your insured business activities.
Can cafes and takeaway shops use the same insurance?
A café and takeaway shop operated by the same legal entity can generally be covered under the same public liability policy. If one company runs dine-in and takeaway services as part of the same operation, both activities can be considered together. The key detail is which legal entity operates each activity, not simply whether the businesses share a trading name.
What are the key risks in the café and restaurant sector?
Key risks include customer slips and falls, food poisoning, foreign objects in food and damage to customer property. Public liability for restaurants and cafes can relate to claims arising from these incidents, while damage to kitchen machinery or theft of stock creates different operational risks. Liability and property protection address distinct exposures, so consider how each applies to your venue.