
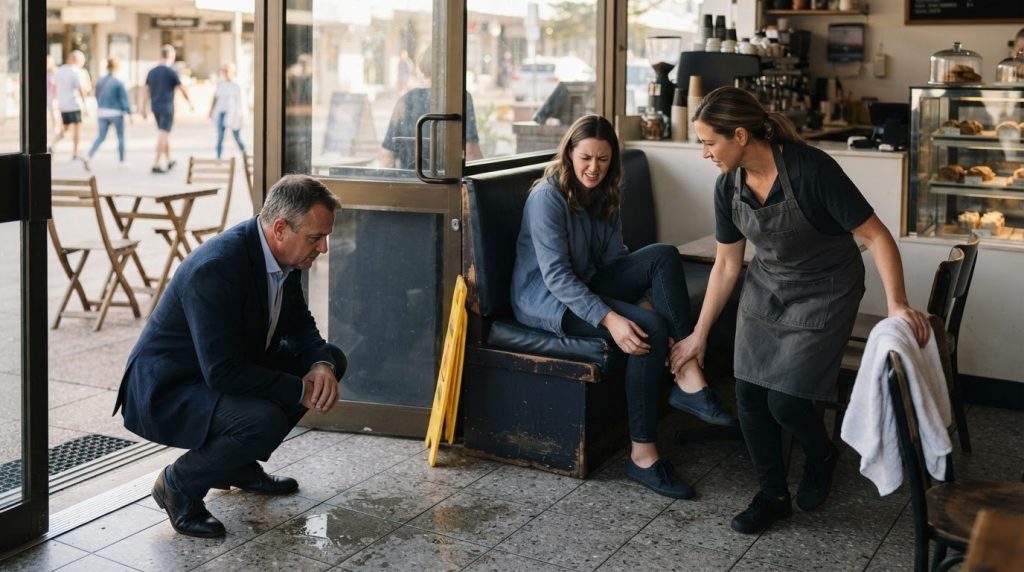
A business insurance package can include public liability, but that does not automatically make it suitable for a café or restaurant. Public liability for restaurants and cafes may cover claims alleging that business activities caused a third party’s injury or property damage, and may include legal expenses. The policy limits, exclusions and treatment of food-related claims all matter.It is easy to assume one package covers every risk under one roof. Look beyond the package label: public liability generally addresses claims from customers or suppliers, while employee injuries are handled separately through workers’ compensation. Lease conditions may also specify a minimum level of cover.This guide explains the difference between public and products liability, the incidents that may lead to a claim, and what to consider when assessing cover for your premises, food and service. It also clarifies where business insurance fits and which policy details to review. Key Takeaways Identify how your lease, outdoor dining arrangements and catering or delivery activities can affect the cover your business needs. Look beyond a business package label: policy limits, exclusions and food-related cover determine what protection may apply. Understand how public and products liability relate to customer injuries, property damage and claims involving food or services. Consider how your premises, menu and day-to-day operations shape the risks that matter when arranging business insurance. Table of Contents If I work in the catering industry, what insurance should I consider? Isn’t public liability insurance included in my business insurance package? Public and products liability for restaurants and cafes MyGen Insurance Brokers If I work in the catering industry, what insurance should I consider? Restaurants and caterers should consider liability insurance alongside cover for their premises, equipment, vehicles and income. The right combination depends on where food is served, how it reaches customers, and any lease or permit conditions.Cover for leased premises and catering Insurance for leased premises and catering should reflect both the fixed site and work carried out elsewhere. A lease may specify minimum public liability and glass cover, while delivery or off-site catering extends the business’s activities beyond its premises. A business package may also cover equipment breakdown, theft or interruption after an insured event such as fire. Commercial motor cover is a separate consideration for delivery vehicles.Legal and contractual insurance requirements Public liability insurance requirements can come from council permits, leases and commercial contracts, rather than one condition applying to every restaurant. For example, North Sydney Council’s outdoor dining requirements list at least A$10 million in public liability cover, or A$20 million for areas within State road areas. Landlords may also require a minimum level of liability or glass cover in … [Read more...] about Public Liability for Restaurants and Cafes: What’s Covered