
An allegation that your professional advice caused a loss can lead to a claim, even when there is no physical damage. In Australia, insurance for management consultants may include Professional Indemnity Insurance for legal costs and damages arising from claims of negligence. Public liability generally addresses specified claims involving personal injury or property damage. Cyber cover is not automatically included in every professional indemnity policy, so check the policy wording.
Choosing cover is easier when you know what risks to consider, especially if your work spans strategic planning, project management or recruitment. This guide explains how the main covers may respond, how claims-made policies affect notification, and what to do if a claim arises. It also shows how your services, client interactions, business property and digital risks can shape your insurance needs.
Key Takeaways
- Match cover to the advice and services you provide, and distinguish professional advice claims from injury or property damage claims.
- Understand how a claims-made policy’s notification period and retroactive date can affect whether a claim may be covered.
- When a claim arises, promptly follow the policy’s notification requirements and keep relevant records of the work and communications.
- Consider how client visits, business equipment, employees and digital operations may shape the insurance your consultancy needs.
Making a claim
A claim against a management consultant may concern professional advice, documents, public liability or other business circumstances. The policy wording explains which cover may respond and how to notify a claim.
For context on structuring liability cover and handling claims, watch this video:
Defamation and intellectual property claims
A client might allege that a consultant’s report harmed their reputation, raising a defamation claim. An allegation of unauthorised use of protected material or branding may involve intellectual property liability. Neither is automatically covered. Check the policy schedule and wording for relevant cover, exclusions and notification conditions. A broker can explain how the policy treats these allegations.
Claims-made policies and cover periods
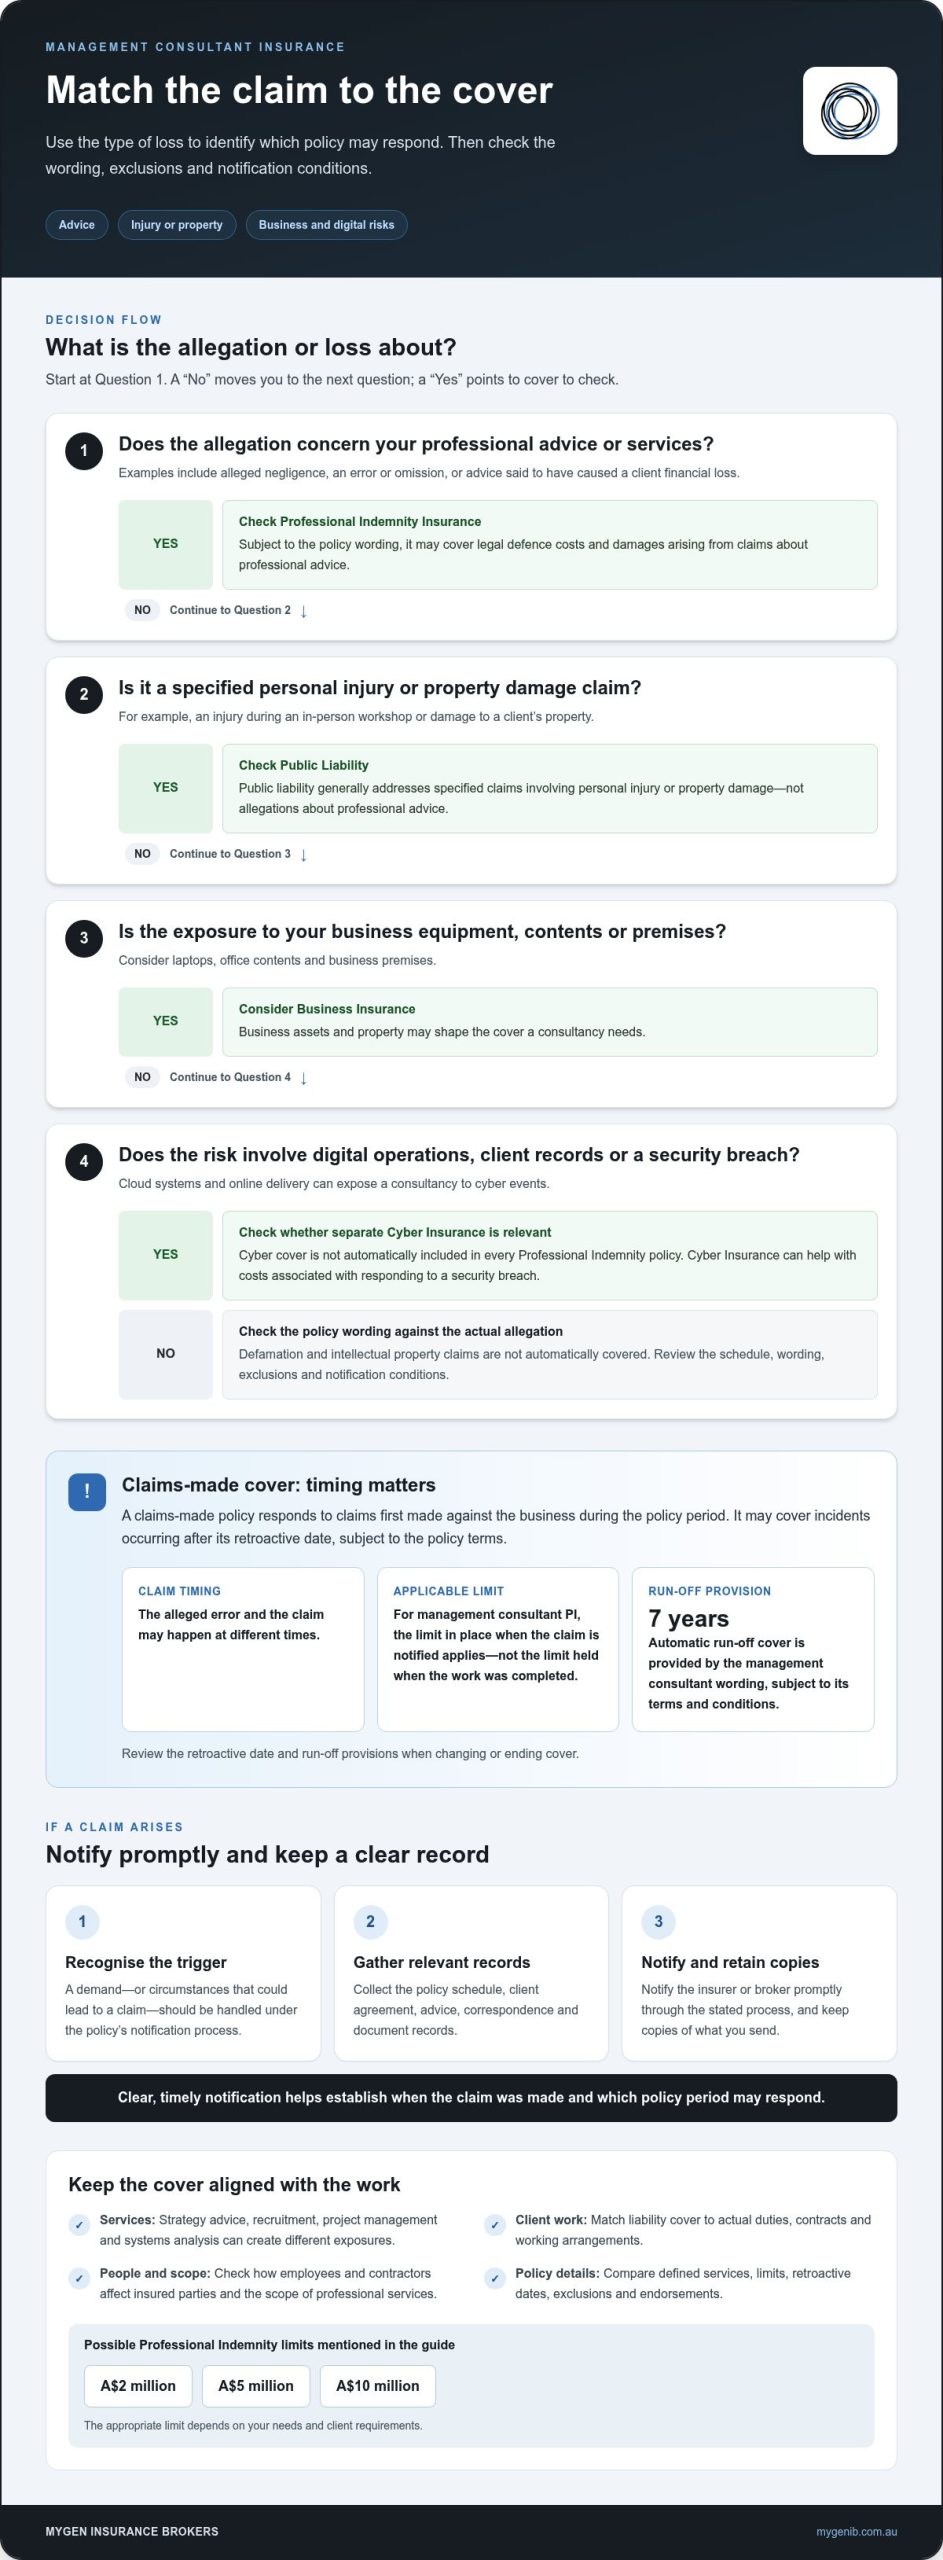
A claims-made policy responds to claims first made against a business during the policy period. It may cover incidents occurring after the policy’s retroactive date, subject to its terms. The alleged error and the claim may occur at different times. For management consultant Professional Indemnity Insurance, the limit in place when the claim is notified applies, not the limit held when the work was completed. The management consultant wording provides seven years of automatic run-off cover, subject to its terms and conditions. Review the retroactive date and run-off provisions when changing or ending cover.
Claims examples and notification process
For example, a client could allege that flawed project advice caused financial loss. Another claim might concern lost or damaged third-party documents. Public liability generally relates to specified injury or property damage claims, rather than allegations about professional advice.
If you receive a demand or become aware of circumstances that could lead to a claim, follow the policy’s notification process promptly. Gather the relevant policy schedule, client agreement, advice, correspondence and document records. Notify the insurer or broker through the stated process, and keep copies of what you send. Clear, timely notification helps establish when the claim was made and which policy period may respond.
What does management consultant insurance cover?
Professional Indemnity Insurance may respond to claims alleging negligence, errors or omissions in professional advice. Subject to the policy terms, it may cover legal defence costs and damages awarded. For example, a client could allege that a consultant’s recommendation breached a professional duty and caused financial loss.
Australian consultants may choose limits such as A$2 million, A$5 million or A$10 million, depending on their needs and client requirements.
What does professional indemnity insurance cover for Australian management consultants? Subject to the policy wording, it may cover legal costs and damages arising from alleged negligent acts, errors or omissions in professional services.
Is professional indemnity insurance legally required for management consultants in Australia? The stated mandatory requirement applies to barristers, with conditions and amounts varying by state. Consultants should distinguish legal obligations from insurance requirements in client contracts.
Do management consultants need cyber insurance or business insurance? Consultants with premises, equipment or other business assets may need Business Insurance. Cyber cover is not automatically included in every professional indemnity arrangement, and digital operations may make separate Cyber Insurance relevant.
How do Australian insurers compare on cover and exclusions? Compare policy schedules and wording, including defined professional services, limits, retroactive dates, exclusions and endorsements. Public liability generally addresses specified injury or property damage claims, not claims about professional advice.
What exclusions and risks should consultants check? Review exclusions relating to your advice, defamation, intellectual property, data breaches and cyber events. Check that the policy describes the services you actually perform.
How can consultants get an insurance quote in Australia? Give a broker details of your services, revenue, company size and client requirements. These factors may influence Professional Indemnity Insurance premiums. A broker can help you assess policy terms that suit your circumstances.
For tailored professional indemnity insurance, consider how your client obligations and services shape the cover you need.
Industry-specific insurance for management consultants
A management consultant’s risk profile depends on the services they deliver and how they work. Strategy advice, recruitment, project management and systems analysis create different exposures. Match liability cover to your actual duties, client contracts and working arrangements, not just your business title.
Consider where a loss could arise. Advice that a client says caused financial harm is different from an injury during an in-person workshop or damage to a client’s property. Public liability may address specified injury and property damage claims, while Professional Indemnity Insurance relates to claims about professional advice. Check each policy’s wording against your activities and client obligations.
- Client-facing work: Consultants meeting clients at home or other premises should consider injury and property damage exposures, including public liability.
- Business equipment: Laptops, office contents and business premises can create property risks. Business insurance may suit consultants with these assets.
- Digital consulting: Client records, cloud systems and online delivery expose a consultancy to cyber events. Cyber insurance can help with costs associated with responding to a security breach.
- Employees and contractors: Check how your arrangements affect the policy’s insured parties and scope of professional services.
Cyber cover varies by policy schedule, wording and endorsements. The Australian Energy Regulator notes that insurers may apply higher retentions and narrower cyber coverage terms. Compare how a policy responds to incident costs, data recovery and legal expenses, then review its exclusions and conditions. A home-based consultant with a digital footprint may also consider Cyber Insurance.
For a more considered fit, map each service, client setting, asset and digital exposure to the relevant cover. Discuss business insurance options for the risks associated with your consultancy.
MyGen Insurance Brokers: Business Insurance
MyGen Insurance Brokers helps Australian consultants assess business risks and consider suitable insurance options. Its consultative approach considers your professional services, client agreements and business circumstances, then recommends relevant cover. This can help clarify whether Professional Indemnity Insurance for advice-related claims or broader Business Insurance suits your needs.
If your work involves different services, business assets or changing client requirements, a review can help align your cover with your circumstances. MyGen Insurance Brokers also offers Commercial Motor Insurance and Home Insurance alongside its business options.
For a considered discussion about cover for your consultancy, contact MyGen Insurance Brokers.
Set up your next review with confidence
Your consultancy may change as you take on different projects, broaden your advice, bring in staff or acquire equipment. Make each review practical: compare your current services and client contract requirements with the activities and assets your insurance is intended to protect. This keeps your insurance decisions connected to how your business operates.
Insurance for management consultants should reflect how you work. MyGen Insurance Brokers offers Professional Indemnity Insurance for professional advice risks, Business Insurance for business exposures, and Commercial Motor Insurance for vehicles used in business. A discussion with a broker can help relate these options to your work and clarify where policy wording matters.
Take the next step at a pace that suits your business. Discuss your consultancy’s insurance needs with MyGen Insurance Brokers and move forward with a clearer view of your cover.
Frequently Asked Questions
How much can professional indemnity insurance cost?
The cost of insurance for management consultants depends on the work insured and the business’s risk profile. Insurers may consider your professional services, company size and revenue when assessing premiums. For example, a consultant providing strategic planning may present different risks from one who also handles recruitment or systems analysis. The price depends on your circumstances and is provided after a quote request.
What is a claims-made policy?
A claims-made policy focuses on when a claim is made and notified, not only when the work occurred. For example, a client could raise an allegation this year about advice delivered earlier. The policy’s retroactive date and terms matter, so keep your policy records and note which insurer covered you when the claim is made.
How much can I cover my business for?
When arranging insurance for management consultants, Australian businesses may select professional indemnity limits such as A$2 million, A$5 million or A$10 million. Consider client contract requirements, the potential financial impact of your advice and the scale of your projects. A contract’s specified limit can guide your decision, alongside your broader exposure and the policy terms.
What is the difference between Public Liability and Professional Indemnity?
Public liability generally addresses specified claims involving personal injury or property damage, while professional indemnity relates to allegations about your advice or professional work. For example, a visitor injured during a workshop may raise a different liability issue from a client alleging that your recommendations caused financial loss. The policy wording determines which circumstances are covered.
Can I bundle multiple types of cover into one policy?
Some insurers offer a business owners policy that combines multiple covers for business needs. A consultant might consider this alongside separate professional indemnity, property or cyber protection. Bundling does not make every risk identical: read each cover’s limits, exclusions and conditions in the policy documents, then consider whether the combined protection fits your activities and business assets.