
A broken shopfront may need urgent attention before you know whether insurance will cover the damage. Glass breakage insurance for shopfronts can cover the repair or replacement of insured glazing, including labour, but coverage depends on the policy, the cause of the breakage and any exclusions. A standard business property policy may limit glass cover or exclude it altogether.
It’s understandable to focus first on the shattered pane and the risk to customers, staff and stock. Make the area safe, document the damage and notify your insurer promptly. Arrange urgent help if the opening is hazardous or unsecured.
This article explains what plate glass insurance may cover, what to do after breakage and when emergency repairs are needed. It also explains how temporary boarding-up can make a site safer without completing the permanent replacement.
Key Takeaways
- Check whether your policy specifically includes the damaged glass and what excess applies before deciding whether to claim.
- If life is in immediate danger, call Triple Zero (000) first, as advised by the Australian Communications and Media Authority.
- Urgent repair may be needed when glass is unstable, public access is at risk or the shop cannot be secured safely.
- Clarify whether emergency make-safe work includes permanent replacement, and keep repair details with your claim records.
What is Plate Glass Insurance?
Shopfront Glass Claim Scenarios
Plate glass insurance covers fixed glass when the policy includes the damaged item and the cause is covered. Possible claim scenarios include a vehicle striking an entry door, vandalism breaking a display window or hail damaging external glazing. For customer-facing venues—from local retailers to grooming establishments like Straight 8 Barbers—policies may also cover internal partitions, wall mirrors, signs, lettering or stock damaged by shards. Check which items are insured before an incident occurs.
Exclusions and Insurance Limits
Exclusions specify damage or circumstances a policy does not cover, while limits cap the amount payable. Scratches or chips that do not amount to breakage, glass defects, wear and tear, or breakage during installation or alteration may be excluded. Gradual deterioration or poor maintenance may also be treated differently from sudden accidental breakage. Check that the policy specifically lists or clearly includes the glass element.
Replacement glazing may need to meet current safety requirements, rather than simply match the broken pane. This may apply to doors, low-level glazing and side panels near doors. Because the required replacement type can affect repair decisions, record the glass specifications.
Premiums depend on factors such as the total glass value, glass type, location and claims history. Compare the repair quote with the applicable excess, including any separate glass excess, before deciding whether to claim.
What should I do if glass breaks at my business?
To make a shopfront glass claim in Australia, contact your insurer as soon as possible. Provide photos, details of the incident and records of any emergency work.
Documenting Damage and Emergency Work
Keep a clear record of the damage, make-safe work and replacement glazing. If it is safe, photograph the window, frame, surrounding area and visible damage from a safe distance before work begins. Keep invoices and ask the glazier to describe the work and glass installed. These records help explain what was done and support the insurer’s assessment.
Sudden and Accidental Damage Claims
Sudden, accidental breakage means unexpected damage rather than deterioration over time. Record when and how the incident happened, and keep the insurer’s claim reference with your repair documents. If you suspect malicious damage, report it to police and retain the event number. Photos of the glazing and likely cause can help document what happened.
Protect people first. If life is in immediate danger, call Triple Zero (000) first, according to the Australian Communications and Media Authority. Keep customers and staff outside an exclusion zone that accounts for glass falling inward, outward or across an access route. Temporary signs alone aren’t enough where the public could approach the damaged area.
Broken glazing can also damage retail stock or other contents; glass cover may include this loss, subject to policy limits. Keep affected items and document the damage. For a wider business cover review, consider how glass and contents risks fit together.
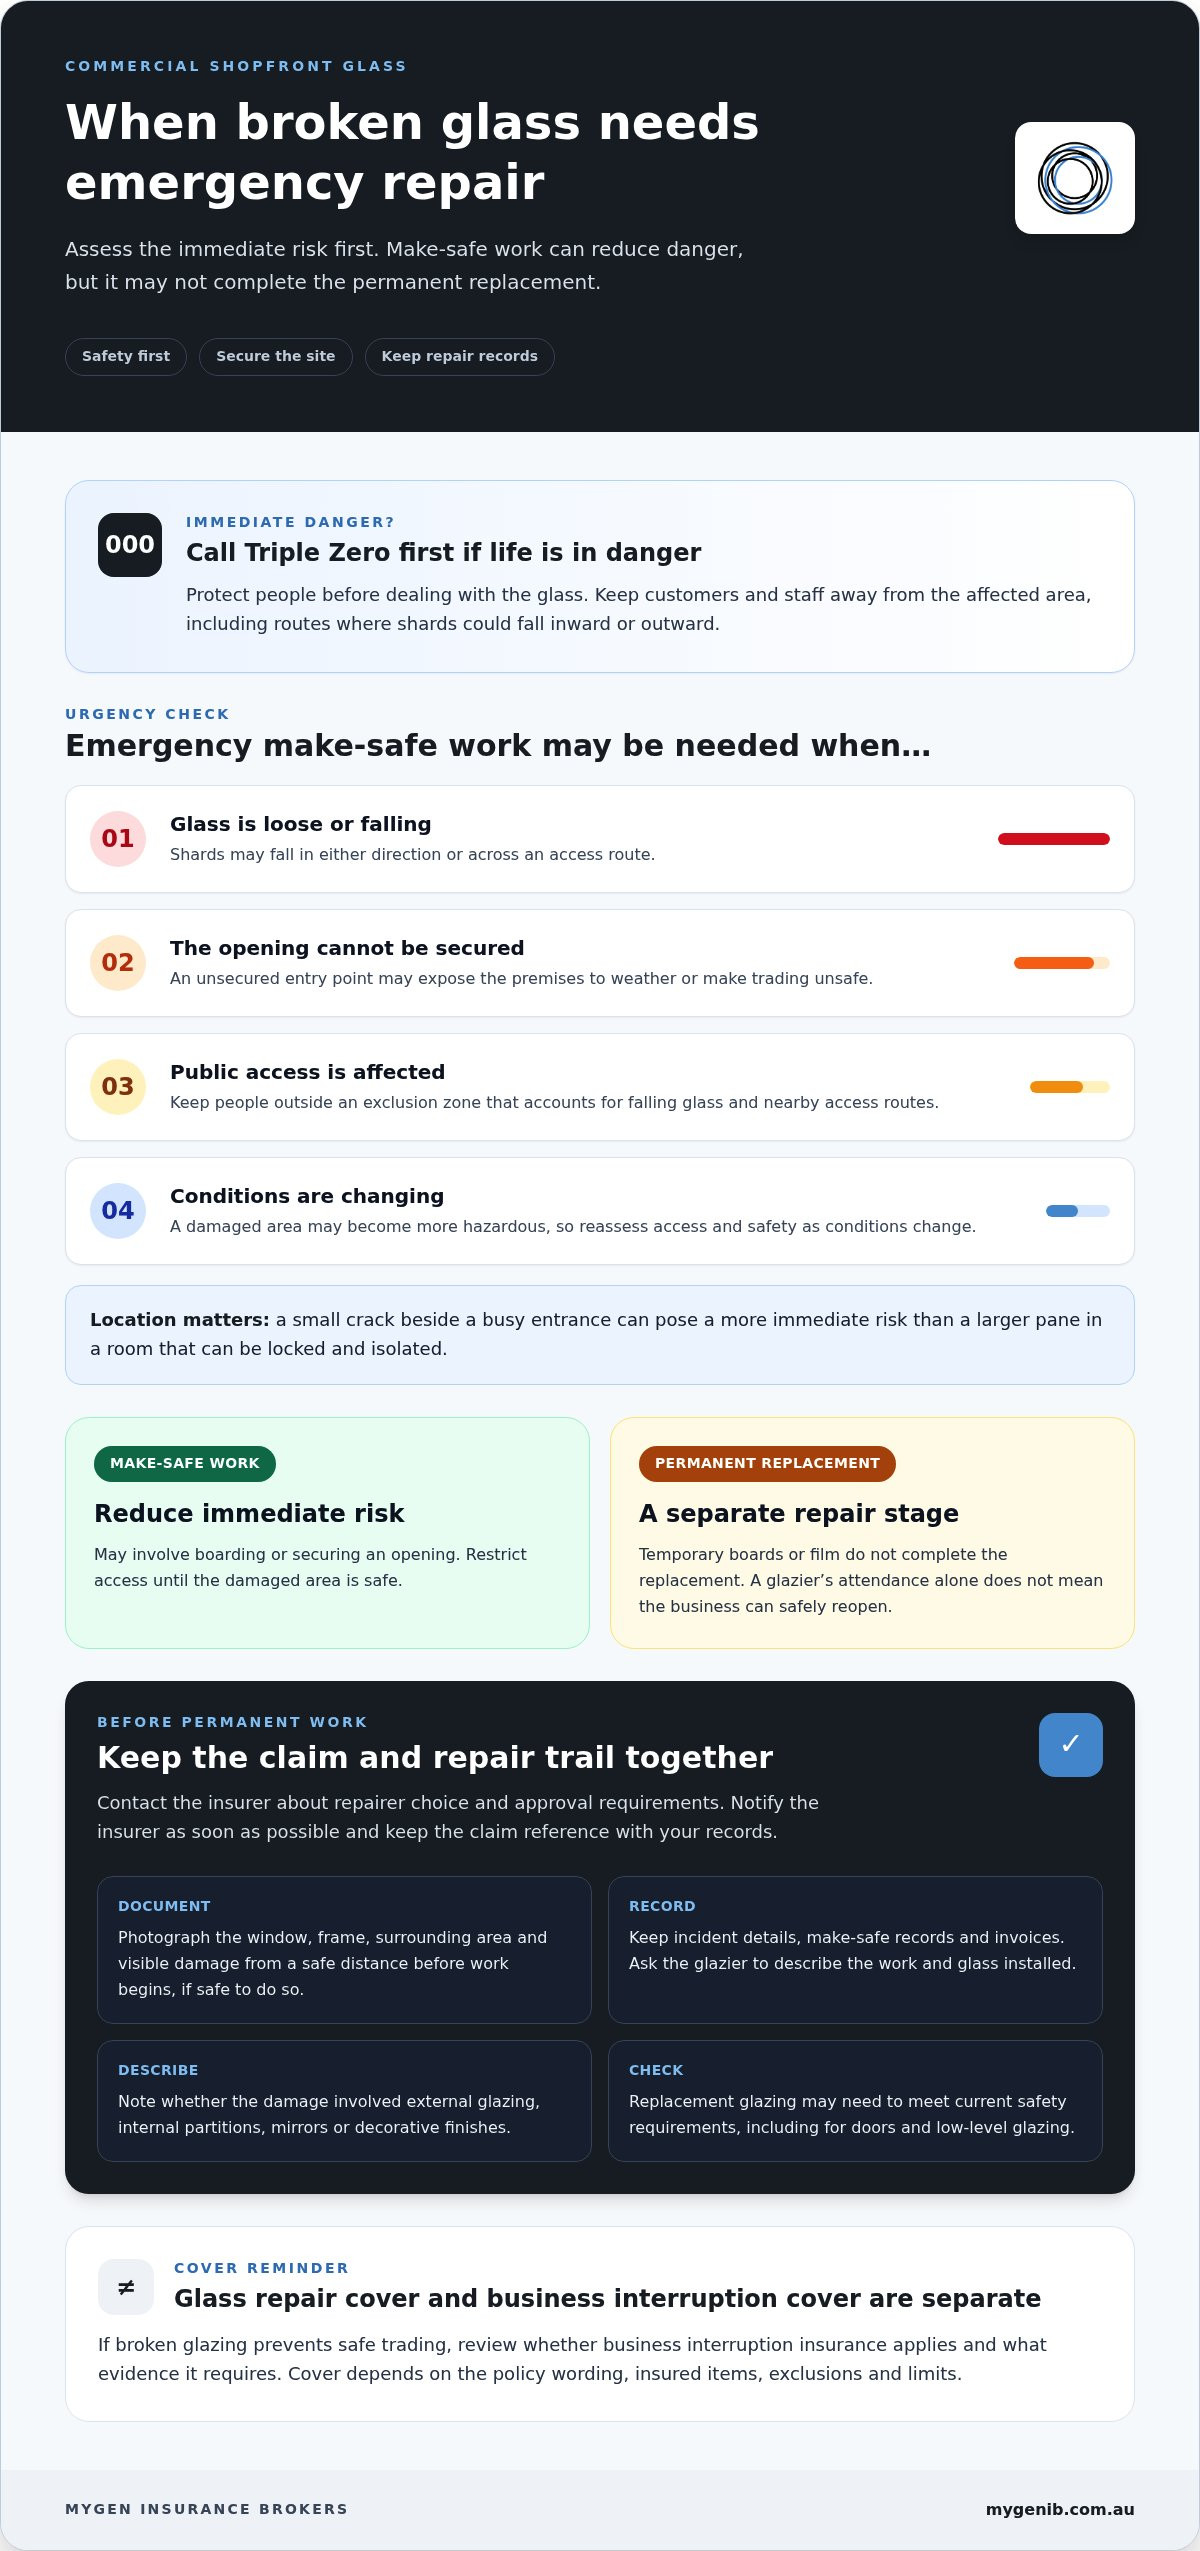
When broken commercial glass needs emergency repair
Emergency repairs are needed when broken glass is loose or falling, an opening cannot be secured, public access is affected or conditions are changing. A small crack beside a busy entrance can pose a more immediate risk than a larger pane in a room that can be locked and isolated.
Keep customers and staff away from the affected area, including routes where shards could fall in either direction. If the external shopfront leaves an entry point unsecured, exposes the premises to weather or makes trading unsafe, urgent make-safe work can reduce immediate risk.
Make-safe work may involve boarding or securing an opening, but it does not necessarily include permanent replacement. Temporary boards or film do not complete the glass replacement, and a glazier’s attendance alone does not mean the business can safely reopen. Restrict access until the damaged area is safe.
Before permanent work begins, contact the insurer about repairer choice and approval requirements. Keep the claim reference, incident details, photographs and invoices with the repair record. Describe whether the damage involved external glazing, internal partitions, mirrors or decorative finishes, as insured items and policy limits affect what a claim can include.
Replacement glazing may need to meet current safety requirements, rather than simply match the broken pane. This may apply to doors, low-level glazing and side panels near doors. Ask the glazier to record the replacement glass and work completed, especially if a compliant option differs from the original.
Glass repair cover and business interruption cover are separate. If broken glazing prevents safe trading, review whether business interruption insurance applies and what evidence it requires. For a considered business insurance review, organise your policy details, claim records and repair documents.
MyGen Insurance Brokers: Business Insurance
MyGen Insurance Brokers helps Australian businesses assess risks and consider suitable Business Insurance. If a damaged shopfront has revealed gaps in your cover, or you’re reviewing your insurance after a claim, a broker can help you assess how your business risks and policy arrangements fit together.
Gather details about the affected glass, how the incident happened, any lease responsibilities, and records of repairs or temporary make-safe work. These details can inform a tailored discussion about your business insurance needs. Cover depends on the policy wording, insured items, exclusions and limits, so understanding them matters before another incident occurs.
For a considered review of your business insurance needs, visit mygenib.com.au.
Make your next insurance review more deliberate
A shopfront claim can prompt a broader review of how your business manages risk. Consider whether your cover reflects your premises, operations and responsibilities, rather than treating each policy as an isolated decision. Glass breakage insurance for shopfronts is one part of the picture, alongside other risks your business may need to address.
MyGen Insurance Brokers offers Business Insurance, Professional Indemnity Insurance and Commercial Motor Insurance. A tailored discussion can help you consider which insurance arrangements suit your circumstances and where a further review may be useful.
Take the next step at a pace that feels right for your business. Contact MyGen Insurance Brokers to discuss your insurance needs and move forward with greater clarity.
Frequently Asked Questions
What’s Covered?
Plate glass insurance can cover insured fixed glazing, with the exact scope set by the policy. For a shop, this might include a display panel or glass entry door; some policies also cover lettering or decorative finishes attached to the glass. Read the insured-items description alongside the exclusions and limits rather than assuming every pane is included.
Are broken windows covered by insurance?
Broken windows may be covered when the glass is insured and the damage results from a covered event. For example, a storm-damaged window may be treated differently from glass that has deteriorated over time. In a leased shop, the lease can help identify whether the tenant or landlord is responsible for insuring the window.
Can I get cover for custom or specialty glass installations?
Custom or specialty glazing can be insured when the policy clearly includes the specific glass and reflects its replacement requirements. This matters for oversized panes, unusual finishes or bespoke decorative glass, which may not be interchangeable with standard glazing. Keep specifications and installation records, and ensure the insured description reflects the glass type and quality.
How do I know I’m getting the right level of cover at the right price?
Compare the insured glass value, policy limits, excess and exclusions with your premises and glazing. Premiums are influenced by factors such as glass type, location, total value and claims history. A lower premium may come with a higher excess or narrower cover, so weigh the likely out-of-pocket claim cost against the protection provided.
How do you get started?
Gather your business details, glazing specifications, lease responsibilities and current policy documents, then contact MyGen Insurance Brokers to discuss your insurance needs. MyGen offers Business Insurance and takes a tailored approach to assessing business risks and suitable cover. Contact MyGen to discuss a review and quote. Services are subject to the company’s terms and conditions.