
There’s no single set premium for insurance for security companies in Australia: costs vary with the work, staffing and cover required. Public liability limits commonly range from A$5 million to A$20 million, so the right figure can also depend on what a client contract demands.
It’s understandable to want a clear cost before committing, especially when insurance needs differ between guarding, patrols and consultancy. This guide explains the cover security businesses may need, the factors that influence premiums, and how to compare policy limits with contract requirements.
You’ll learn what public liability and professional indemnity may cover, how staffing and operational risks affect insurance needs, and what to consider when setting limits. The aim is to help you assess your business’s requirements with greater confidence.
Key Takeaways
- Match your public liability limit to each client contract, as commercial and government work may set minimum requirements.
- Consider professional indemnity cover if your security work involves advice, design or supervision, where financial loss may be a concern.
- Compare indicative premiums by looking at the work you perform, staffing, use of force and the cover your operations require.
- Build a practical insurance program around your business activities, including workers compensation where you employ security staff and commercial motor cover for patrol vehicles.
Choosing policy limits for client contracts
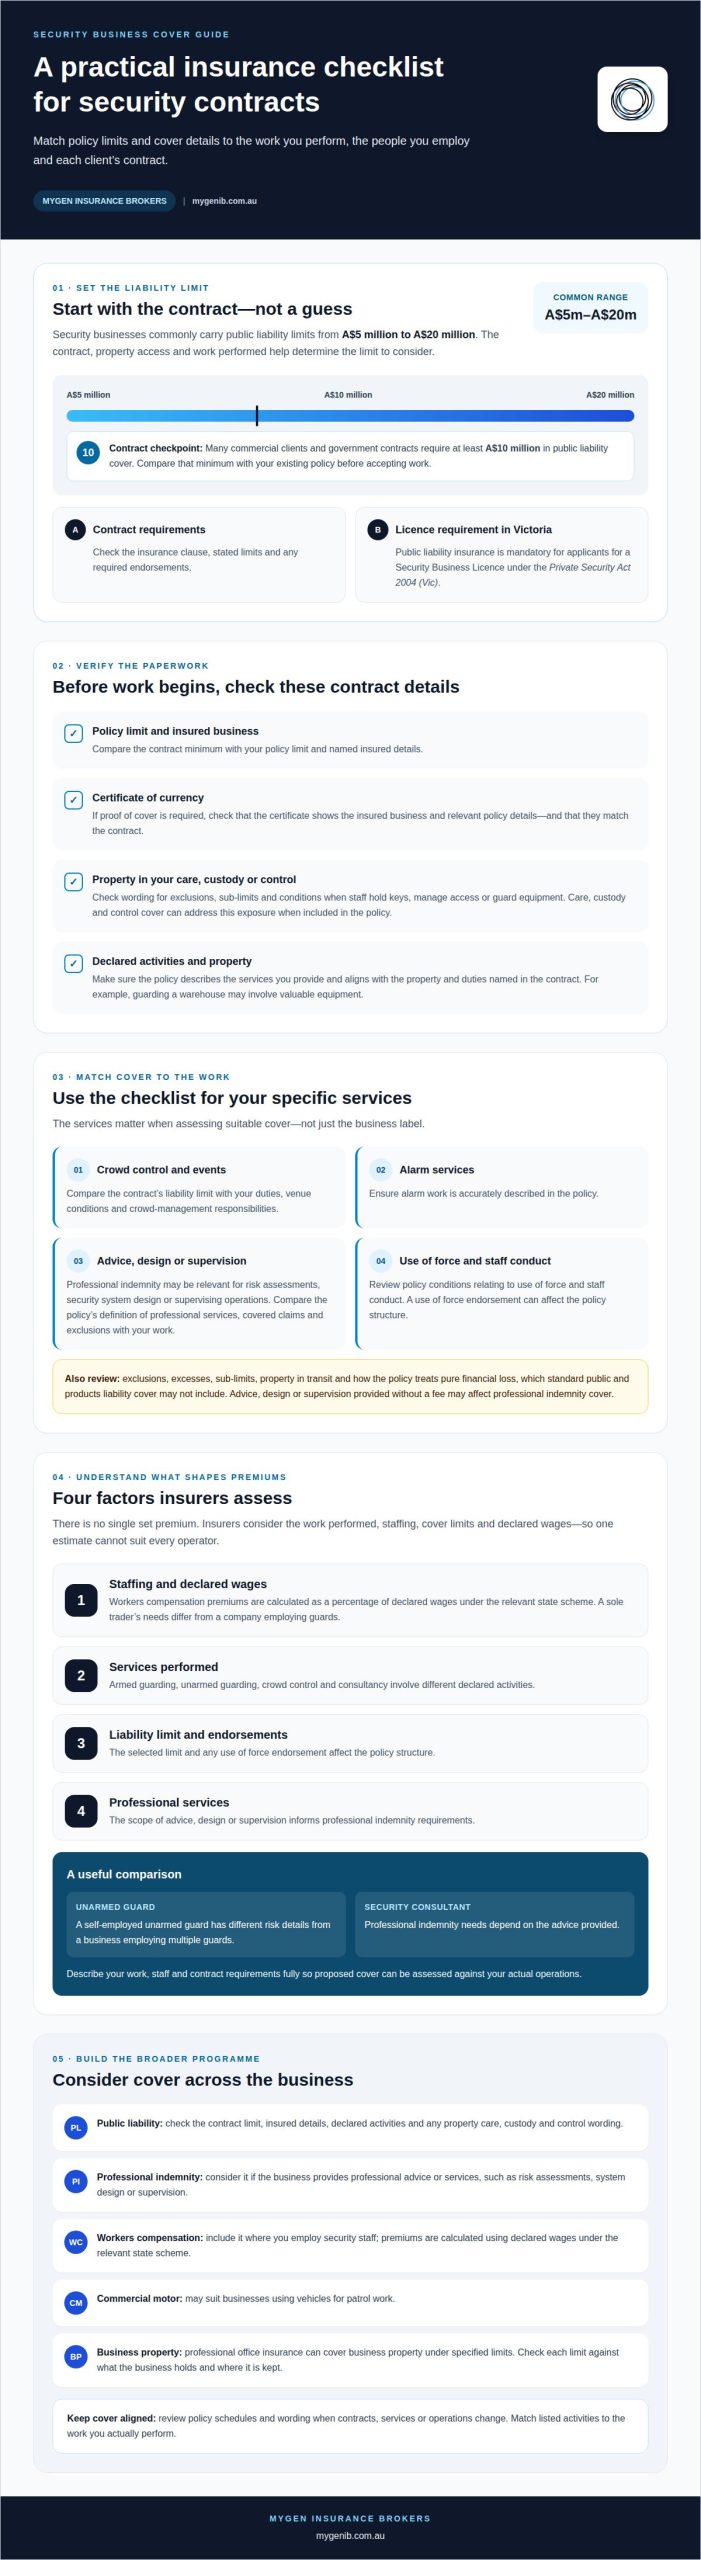
Security businesses commonly carry public liability limits from A$5 million to A$20 million. Contract terms, property access and the work performed shape the limit to consider.
Matching limits to client contracts
Start with each contract’s insurance clause. Many commercial clients and government contracts require at least A$10 million in public liability coverage. Compare that minimum with your existing policy limit, named insured details and any required endorsements before accepting work. In Victoria, public liability insurance is mandatory for applicants for a Security Business Licence under the Private Security Act 2004 (Vic).
Clients may require proof of cover, such as a certificate of currency showing the insured business and relevant policy details. Compare the certificate with the contract’s stated limits and coverage requirements.
Property in care, custody and control
Public liability policies may treat property in your care, custody and control differently from other third-party property. Check the wording for exclusions, sub-limits and conditions that apply when staff hold keys, manage access or guard equipment. For example, guarding a client’s warehouse may involve exposure to claims involving valuable equipment, so consider this when reviewing contract terms.
Care, custody and control cover can address this exposure when included in the policy. Check that the declared activities and property align with the contract.
For crowd control and event security, compare the contract’s liability limit with your duties, venue conditions and crowd-management responsibilities. If your work includes alarm services, ensure that activity is accurately described in the policy. The specific services matter when assessing suitable cover, not just the business label.
What does security industry insurance cover?
Insurance for security businesses can address liability, professional advice and business property. The appropriate mix depends on your duties and the policy wording.
Professional indemnity cover
Professional indemnity insurance may respond to claims alleging errors in professional advice or services. It may be relevant if your security company provides risk assessments, designs security systems or supervises operations. Compare the policy’s definition of professional services, covered claims and exclusions with the work you perform. Advice, design or supervision provided without a fee may affect cover.
Policy exclusions and risks
Before buying, compare policy schedules and wording. Match the listed activities to your services, then review exclusions, excesses and sub-limits. Check how the policy treats pure financial loss, which standard public and products liability cover may not include. Also review conditions relating to use of force, alarm services, staff conduct and property in transit. These details can determine whether a specific incident is covered.
Professional office insurance can cover business property under specified limits. Check each limit against the property your business holds and where it is kept. For a tailored review of business risks, explore professional indemnity insurance.
Indicative security insurance costs
Australian insurers assess applications by examining the security industry work performed, staffing, cover limits and declared wages. A sole trader’s needs differ from a company employing guards, providing armed services or offering security advice.
Premiums reflect the activities and exposures included in the proposed cover. These details help explain why one estimate cannot suit every operator:
- Staffing: Workers compensation premiums are calculated as a percentage of declared wages under the relevant state scheme.
- Services: Armed guarding, unarmed guarding, crowd control and consultancy involve different declared activities.
- Liability cover: The selected limit and any use of force endorsement affect the policy structure.
- Professional services: The scope of advice, design or supervision informs professional indemnity requirements.
For example, a self-employed unarmed guard has different risk details from a business employing multiple guards. A security consultant’s professional indemnity needs also depend on the advice provided. When preparing an application, describe your work, staff and contract requirements fully so the proposed cover can be assessed against your actual operations.
To understand your business insurance options, discuss cover for your security business and the activities your policy needs to reflect.
MyGen Insurance Brokers: Business Insurance
MyGen Insurance Brokers helps Australian businesses review risks and consider insurance suited to their operations. If your security company is reviewing policy wording, contract requirements or changes to its work, a personalised discussion can help identify which exposures to consider.
Business Insurance can address broader business risks, while Professional Indemnity Insurance is relevant to security businesses providing professional advice or services. Commercial Motor Insurance may suit businesses using vehicles for patrol work. MyGen takes a personalised approach, considering your activities and the cover that may suit them rather than relying on a generic package.
If your security operations or contracts have changed, contact MyGen Insurance Brokers to discuss your insurance needs, or visit mygenib.com.au.
Make your next insurance review count
As your security work changes, include an insurance review when planning new contracts, services or operational changes. A clear account of your activities and priorities can make conversations about suitable protection more focused. Choosing insurance for security companies in Australia is not just an annual renewal task; it is an opportunity to keep cover aligned with how your business operates.
MyGen Insurance Brokers offers Business Insurance, Professional Indemnity Insurance and Commercial Motor Insurance. If you’re reviewing cover for security work or considering your business risks, contact the team to discuss your needs and the options that may suit your circumstances.
Contact MyGen Insurance Brokers to take the next step towards a clearer insurance plan. With a considered review, you can move forward with greater confidence.
Frequently Asked Questions
How Much Does Security Guard Insurance Cost in Australia?
Insurance for security companies in Australia does not have one standard premium for every guard. Costs depend on whether you work independently, provide armed or unarmed services, and need public liability or professional indemnity cover. Staffing and business activities also shape the insurance program. Treat indicative market costs as a starting point, then compare cover and limits with your duties and contracts.
What insurance is legally required for security companies in Australia?
Requirements depend on the state, licence and business circumstances. In Victoria, applicants for a Security Business Licence must hold public liability insurance under the Private Security Act 2004 (Vic). Security workers and businesses in Victoria should check which licences apply to their roles and operations. Employers with security staff must also have workers compensation insurance.
What types of insurance should Australian security companies consider?
Consider public liability for third-party injury or property damage, and professional indemnity if your work involves security advice or supervision. Businesses employing guards also need to consider workers compensation, while operators using patrol vehicles may need commercial vehicle cover. For example, a firm offering consulting and mobile patrols should assess each activity separately rather than assume one policy addresses every exposure.
How much does security company insurance cost in Australia?
For insurance for security companies in Australia, costs vary with the work performed, workforce, wages, cover limits and policy features. A small unarmed guarding operation has different risk details from a larger firm offering armed services or consultancy. Workers compensation premiums are calculated as a percentage of declared wages under the relevant state scheme. Compare each policy’s cover with your activities and contract obligations.
Does workers compensation insurance vary by Australian state and territory for security companies?
Yes. Workers compensation premiums are calculated as a percentage of declared wages under the relevant state scheme, so the scheme applying to your business matters. Employers should identify where their security staff work and which wages they declare when reviewing this cover. For example, a business operating across state borders should account for workforce locations when reviewing its workers compensation arrangements.