
A professional indemnity claim can arise when a client alleges that an agent’s advice or services caused financial loss. Professional indemnity for real estate agents may cover claims alleging negligence, including legal defence and settlement costs, subject to the policy terms. Because this is generally claims-made cover, when a claim is made and whether retroactive cover applies can matter.
It’s understandable to want clarity when everyday work, from giving advice to coordinating property maintenance, could lead to a dispute. The key is understanding which professional risks may be covered and how the policy’s timing affects a claim.
This article outlines common exposures for agents, property managers and strata managers, how cover may respond to allegations of negligence, and what can affect eligibility, including disclosure and changes to your business.
Key Takeaways
- Promptly notify the insurer about claims or circumstances that could lead to one, and keep clear records of incidents, maintenance and relevant correspondence.
- Cover may respond to allegations that professional advice or services caused financial loss, including legal defence and settlement costs, subject to policy terms.
- Eligibility can depend on the agency’s activities, claims history, business changes and the information disclosed during underwriting.
- In New South Wales, holding a property licence is conditional on being insured under a professional indemnity policy; tailored advice can help align cover with your business risks.
What are the Professional Indemnity Risk Exposures?
Real estate work can create exposures through advice, property management and communications. A client may allege that an agent’s advice or service caused financial loss. Depending on the policy wording, professional indemnity may also respond to claims involving defamation or misleading conduct. Both the agency’s work and the allegation matter when assessing liability.
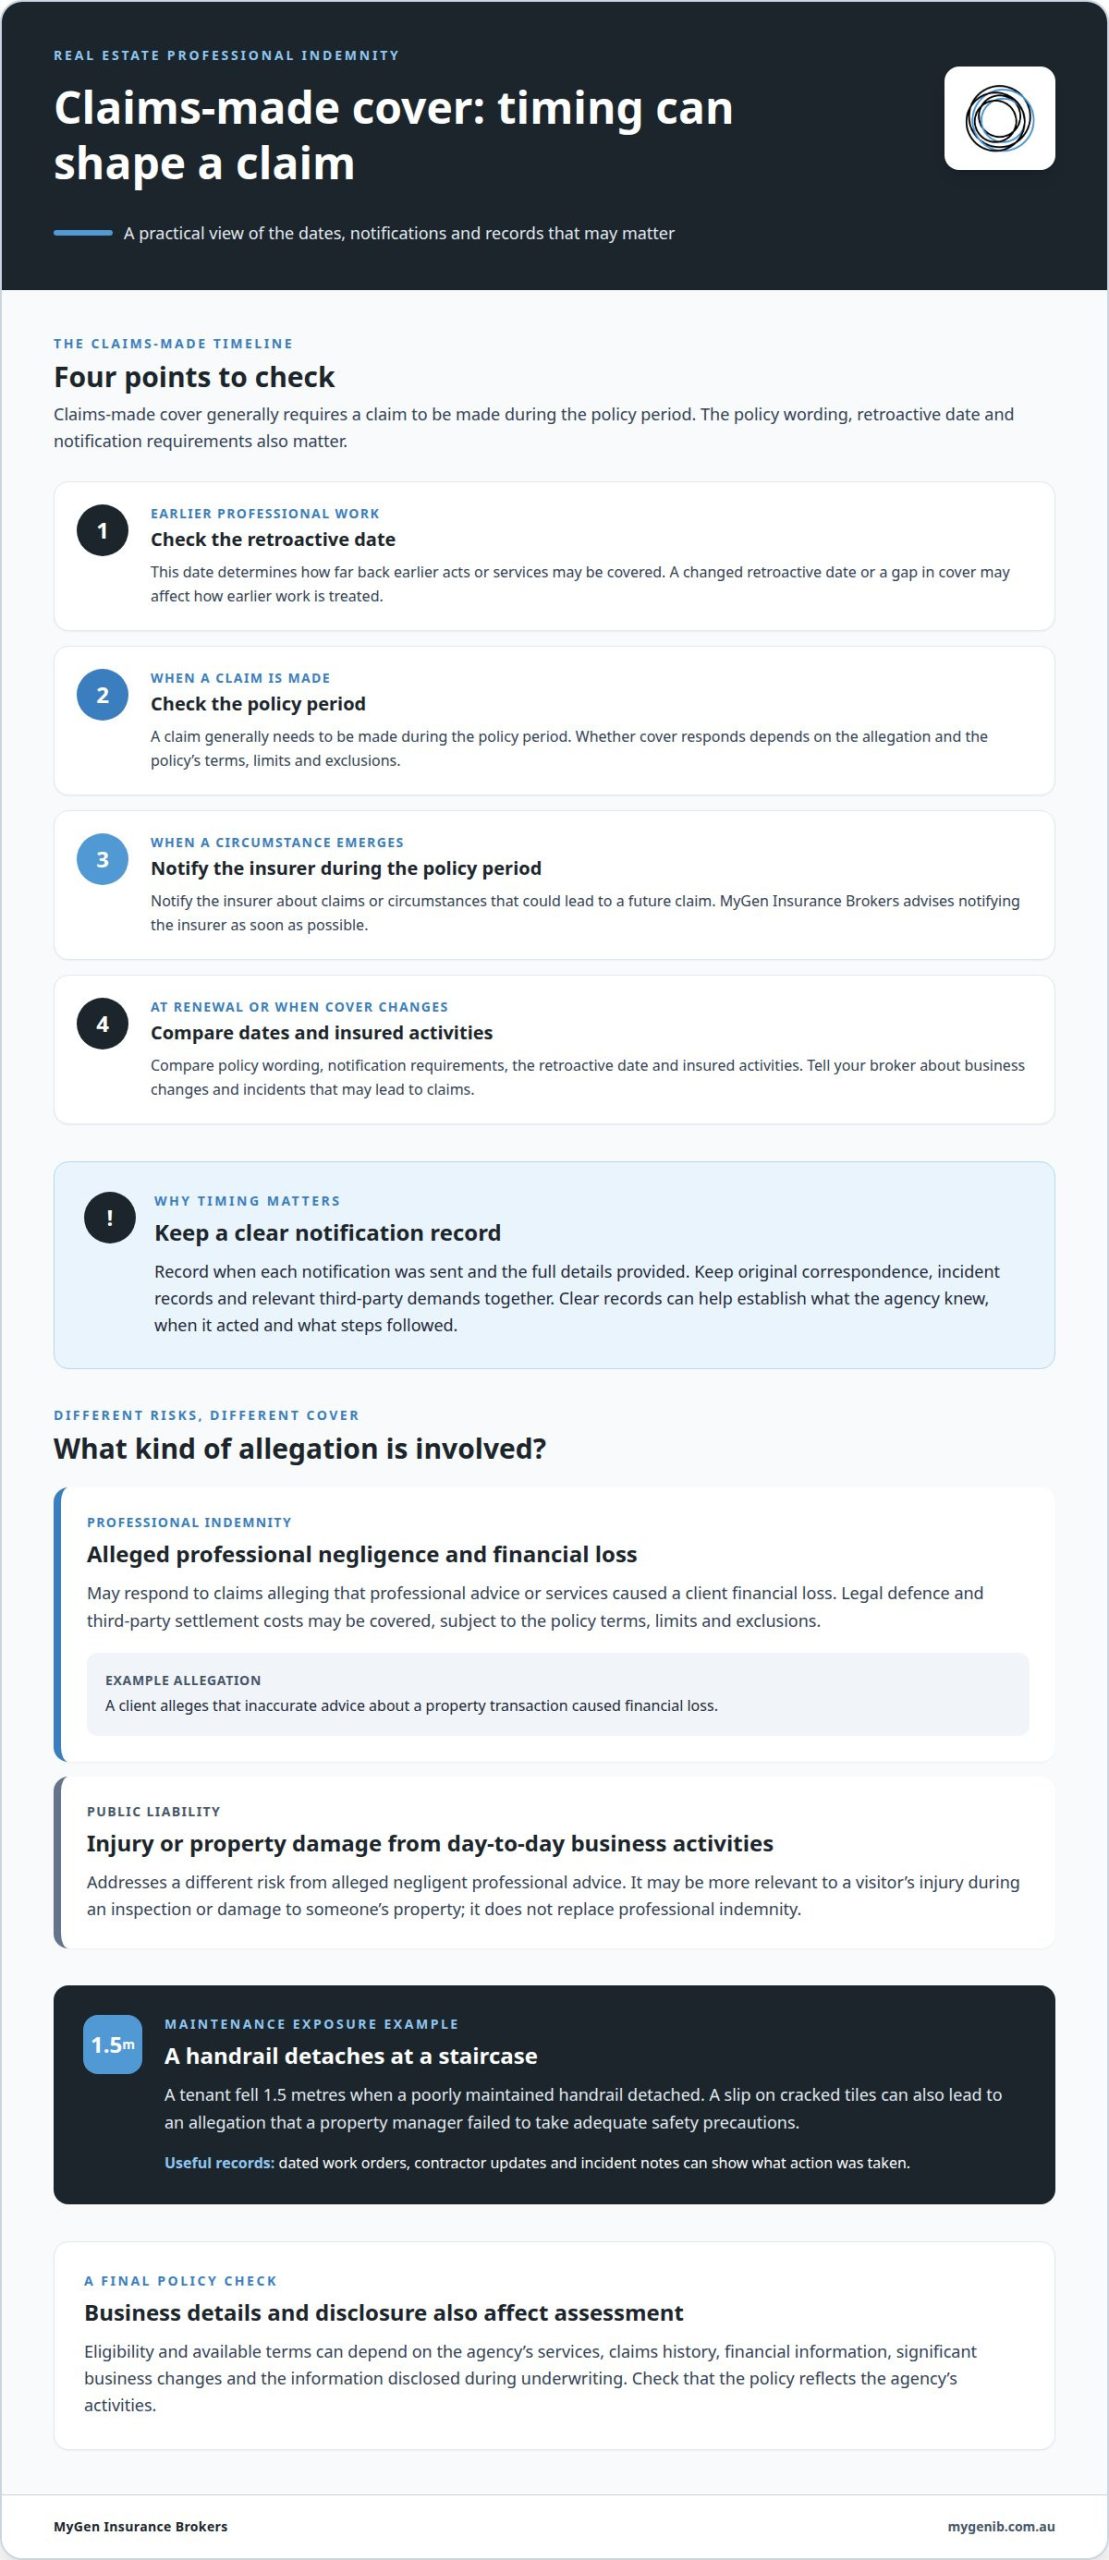
Maintenance can create separate injury and property damage risks. For example, a tenant fell 1.5 metres when a poorly maintained handrail detached at a staircase. A slip on cracked tiles can also prompt an allegation that a property manager failed to take adequate safety precautions. Timely maintenance and follow-up help reduce these risks; dated work orders, contractor updates and incident notes can show what action was taken.
Claims-made cover makes timing important. A claim generally needs to be made during the policy period, while the retroactive date determines how far back earlier acts or services may be covered. Notify the insurer during the policy period about circumstances that could lead to a future claim. MyGen Insurance Brokers advises notifying the insurer as soon as possible about claims or potential claim circumstances. Keep the original correspondence, incident records and relevant third-party demands together.
When renewing or changing cover, compare the policy wording, retroactive date, notification requirements and insured activities. Tell your broker about business changes and incidents that may lead to claims, so your cover can stay up to date. Check that the new policy dates preserve continuity, as a gap or changed retroactive date may affect how earlier work is treated.
Keep a clear record of each notification, including when it was sent and the full details provided. Treat emails and other communications as potentially discoverable if a dispute develops. Clear records help establish what the agency knew, when it acted and what steps followed.
Professional indemnity cover for alleged professional negligence
Professional indemnity for real estate agents may respond to claims alleging that an agent’s professional services caused a client financial loss. Public liability addresses a different risk: injury or property damage arising from day-to-day business activities.
Cover for alleged financial loss
Professional indemnity may cover legal defence and third-party settlement costs when a claim alleges negligence, subject to the policy’s terms, limits and exclusions. For example, a client might allege that inaccurate advice about a property transaction caused financial loss. Property and strata managers may also face claims about their management services, including advice or decisions made while managing a property or coordinating body corporate affairs. The allegation and policy wording determine how cover responds.
Choosing a cover amount
The appropriate limit depends on the agency’s services, client contracts and the potential scale of claims. New South Wales, Victoria and Queensland have state-specific minimum requirements for real estate professionals. For example, active Victorian agencies such as eliteagents.net.au that balance residential sales with ongoing property management must align their policy limits with their overall scope of operations. When choosing professional indemnity for real estate agents, consider the applicable state requirement alongside contractual obligations and the agency’s exposures.
To apply, provide the insurer with details of the agency’s activities and relevant risk information, including claims or circumstances that may lead to a claim. Cover starts only after written acceptance and payment, or agreement to pay, the premium, unless temporary cover is confirmed in writing. A broker can help assess professional indemnity cover against the agency’s work.
Whether an agency policy covers employees, contractors and property managers depends on its definitions and wording. Employees may be included if the policy covers agency staff, but some policies exclude contractors, who may need separate insurance. Public liability is more relevant to a visitor’s injury during an inspection or damage to someone’s property. It does not replace professional indemnity for alleged negligent advice.
Business eligibility and underwriting appetite
Underwriting considers the agency’s professional services and the information provided about its business. Complete, accurate disclosure helps insurers assess the risks and set policy terms.
Insurers offering professional indemnity
Insurers offering professional indemnity assess real estate risks according to their underwriting appetite. The options available depend on the agency’s services, history and disclosures, so no single insurer suits every business. An insurance broker can present the agency’s risk details to insurers to arrange cover. The assessment may include claims history, financial information and significant business changes.
Whether insurance is mandatory
Professional indemnity insurance is mandatory for property licence holders in New South Wales, where holding a licence is conditional on being insured under a policy. Aon also says real estate professionals in some Australian states may be required to hold this cover. The requirement matters because a licence condition can affect whether an agency or individual can carry out regulated work.
State and territory requirements
New South Wales, Victoria and Queensland have state-specific minimum professional indemnity limits for real estate professionals. The applicable limit depends on the state’s requirements, so the agency’s location matters. Requirements in South Australia, Western Australia, Tasmania, the Australian Capital Territory and the Northern Territory must be considered under each jurisdiction’s licensing rules. Don’t assume one state’s limit applies nationally.
Under the Insurance Contracts Act 1984, applicants must disclose matters known, or reasonably expected to be relevant to an insurer’s decision. An insurer may reduce claim liability or cancel a contract for non-disclosure; fraudulent non-disclosure may allow it to avoid the contract from its beginning. A proposal may ask about acquisitions during the last six years and the agency’s financial situation. Discuss your agency’s insurance needs to consider how its professional services, reputation and business changes affect the application.
MyGen Insurance Brokers: Professional Indemnity Insurance
MyGen Insurance Brokers helps Australian real estate professionals consider Professional Indemnity Insurance in light of their work and business risks. This can help when arranging or renewing cover, or changing an agency’s services. Understanding your professional activities and potential exposures is an important part of choosing suitable policy wording.
MyGen Insurance Brokers takes a personalised, consultative approach to identifying business risks and recommending insurance solutions. Professional Indemnity Insurance can address claims relating to professional services, while Business Insurance may form part of a broader risk management approach. The aim is to consider your circumstances carefully, rather than assume every agency has the same needs.
For help reviewing your agency’s insurance needs, contact MyGen Insurance Brokers.
Keep your agency’s protection aligned
Your agency’s work can change as its services, contracts and responsibilities evolve. Make insurance review part of business planning, so cover remains aligned with the work you undertake and the risks your agency accepts. Professional indemnity for real estate agents is one part of that picture. Consider how it fits alongside broader business protection, rather than viewing each policy in isolation.
MyGen Insurance Brokers offers Professional Indemnity Insurance, Business Insurance and Commercial Motor Insurance. A considered discussion can help identify the business information and exposures relevant to your insurance needs, without assuming every agency requires the same arrangement. If a review is timely, contact MyGen Insurance Brokers to discuss your agency’s insurance needs. A measured next step can help you approach those decisions with greater clarity and confidence.
Frequently Asked Questions
What isn’t covered?
Exclusions depend on the policy wording and the circumstances behind a claim. For example, Aon says professional indemnity policies generally don’t cover commission disputes with contractors because these are commercial losses. A contractor may also fall outside the policy’s insured parties. Review the exclusions and definitions of insured persons to understand which disputes, services and people are outside cover.
How do I lodge a claim?
Notify the insurer promptly and provide the demand or relevant third-party correspondence, together with a clear account of what happened. Aon advises notifying the insurer as soon as possible about a claim or circumstances that could lead to one. Include dates, the people involved, relevant file notes and supporting documents, such as the management agreement or client communications, to help the insurer assess the matter.
What does Professional Indemnity Insurance typically cover?
Professional Indemnity Insurance may respond to claims alleging that professional services caused a client financial loss. Depending on the policy, cover may include legal defence and settlement costs and may extend to allegations involving defamation or misleading conduct. For example, a client might claim that advice or an agency service led to financial loss. The policy’s terms, limits and exclusions determine how it responds.
Are costs inside the limit?
Whether legal defence costs reduce the available limit depends on the policy wording. Check whether defence costs are included within the limit or payable in addition to it, and whether the limit applies per claim or across claims. This affects how much remains available for a settlement after legal costs are incurred, so review the relevant limit clauses together.
Does the wording address common Real Estate exposures?
Professional indemnity can address real estate exposures when the insured activities and relevant risks fit the policy wording. Review how the policy describes sales, property management or strata management, along with any exclusions affecting contractors. For example, a policy may treat professional advice differently from physical injury during an inspection. Clear definitions help establish whether your agency’s work falls within the insured professional services.