
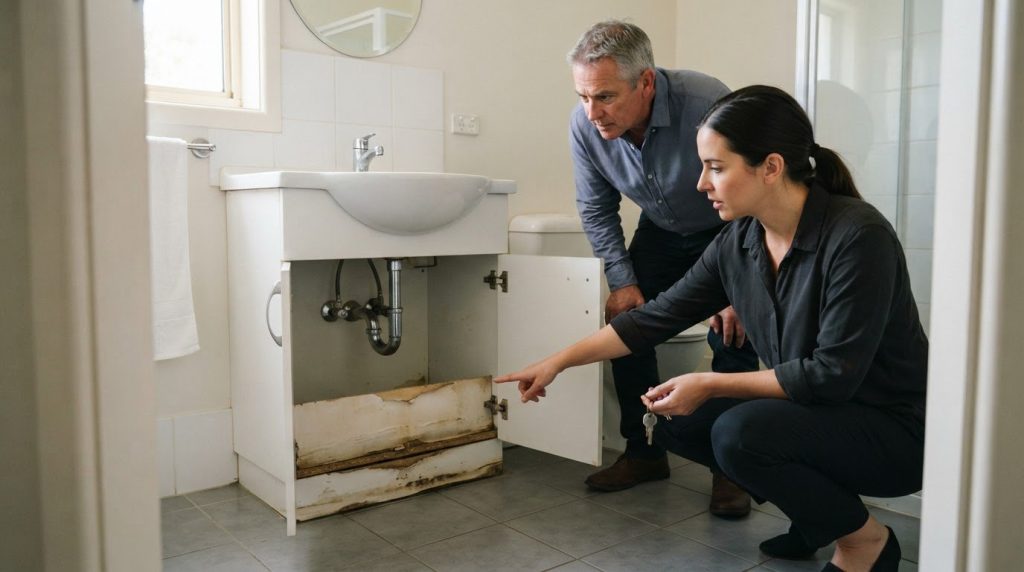
A professional indemnity claim can arise when a client alleges that an agent’s advice or services caused financial loss. Professional indemnity for real estate agents may cover claims alleging negligence, including legal defence and settlement costs, subject to the policy terms. Because this is generally claims-made cover, when a claim is made and whether retroactive cover applies can matter.It’s understandable to want clarity when everyday work, from giving advice to coordinating property maintenance, could lead to a dispute. The key is understanding which professional risks may be covered and how the policy’s timing affects a claim.This article outlines common exposures for agents, property managers and strata managers, how cover may respond to allegations of negligence, and what can affect eligibility, including disclosure and changes to your business. Key Takeaways Promptly notify the insurer about claims or circumstances that could lead to one, and keep clear records of incidents, maintenance and relevant correspondence. Cover may respond to allegations that professional advice or services caused financial loss, including legal defence and settlement costs, subject to policy terms. Eligibility can depend on the agency’s activities, claims history, business changes and the information disclosed during underwriting. In New South Wales, holding a property licence is conditional on being insured under a professional indemnity policy; tailored advice can help align cover with your business risks. Table of Contents What are the Professional Indemnity Risk Exposures? Professional indemnity cover for alleged professional negligence Business eligibility and underwriting appetite MyGen Insurance Brokers: Professional Indemnity Insurance What are the Professional Indemnity Risk Exposures? Real estate work can create exposures through advice, property management and communications. A client may allege that an agent’s advice or service caused financial loss. Depending on the policy wording, professional indemnity may also respond to claims involving defamation or misleading conduct. Both the agency’s work and the allegation matter when assessing liability.Maintenance can create separate injury and property damage risks. For example, a tenant fell 1.5 metres when a poorly maintained handrail detached at a staircase. A slip on cracked tiles can also prompt an allegation that a property manager failed to take adequate safety precautions. Timely maintenance and follow-up help reduce these risks; dated work orders, contractor updates and incident notes can show what action was taken.Claims-made cover makes timing important. A claim generally needs to be made during the policy period, while the retroactive date determines how far back earlier acts or services may be covered. Notify the insurer during the policy period about circumstances that could lead to a future claim. MyGen Insurance Brokers advises notifying the insurer as soon as possible about … [Read more...] about Professional indemnity for real estate agents and their key risks