
A sale isn’t the only time valuable artwork is exposed to loss or damage. In Australia, art and collectibles insurance may include fine art and specie cover, with agreed values setting a pre-agreed insured amount for listed items. For dealers, protection may also need to account for commercial stock while it is stored, handled or in transit, subject to the policy terms.
It’s understandable to expect home and contents insurance to protect valuable art, but sub-limits and exclusions can leave gaps, especially when an item is moved between locations. An agreed value can make the basis of cover clearer if a loss occurs.
This guide explains how fine art and specie cover works, why valuations and agreed values matter, and what to consider when insuring a collection or a dealer’s stock. It also outlines how business insurance can fit in when your work involves valuable commercial property.
Key Takeaways
- An agreed value can clarify the insured amount for a listed artwork or collectible, making accurate valuations an important part of arranging cover.
- Review how cover responds to theft, accidental damage and periods when an item is on loan or in transit.
- For dealers, consider how stock is protected during storage, handling and transport, including the risks of poor packing.
- Business Insurance may help address a dealer’s wider commercial risks, while the right cover depends on the business and its stock.
What is agreed value insurance and why does it matter for valuables?
Agreed-value cover sets an insured amount for a specific artwork or collectible, based on its valuation and the policy terms. Fine art cover may address risks such as theft, accidental damage and transit, while exclusions and limits define the protection.
Agreed-value cover for valuables
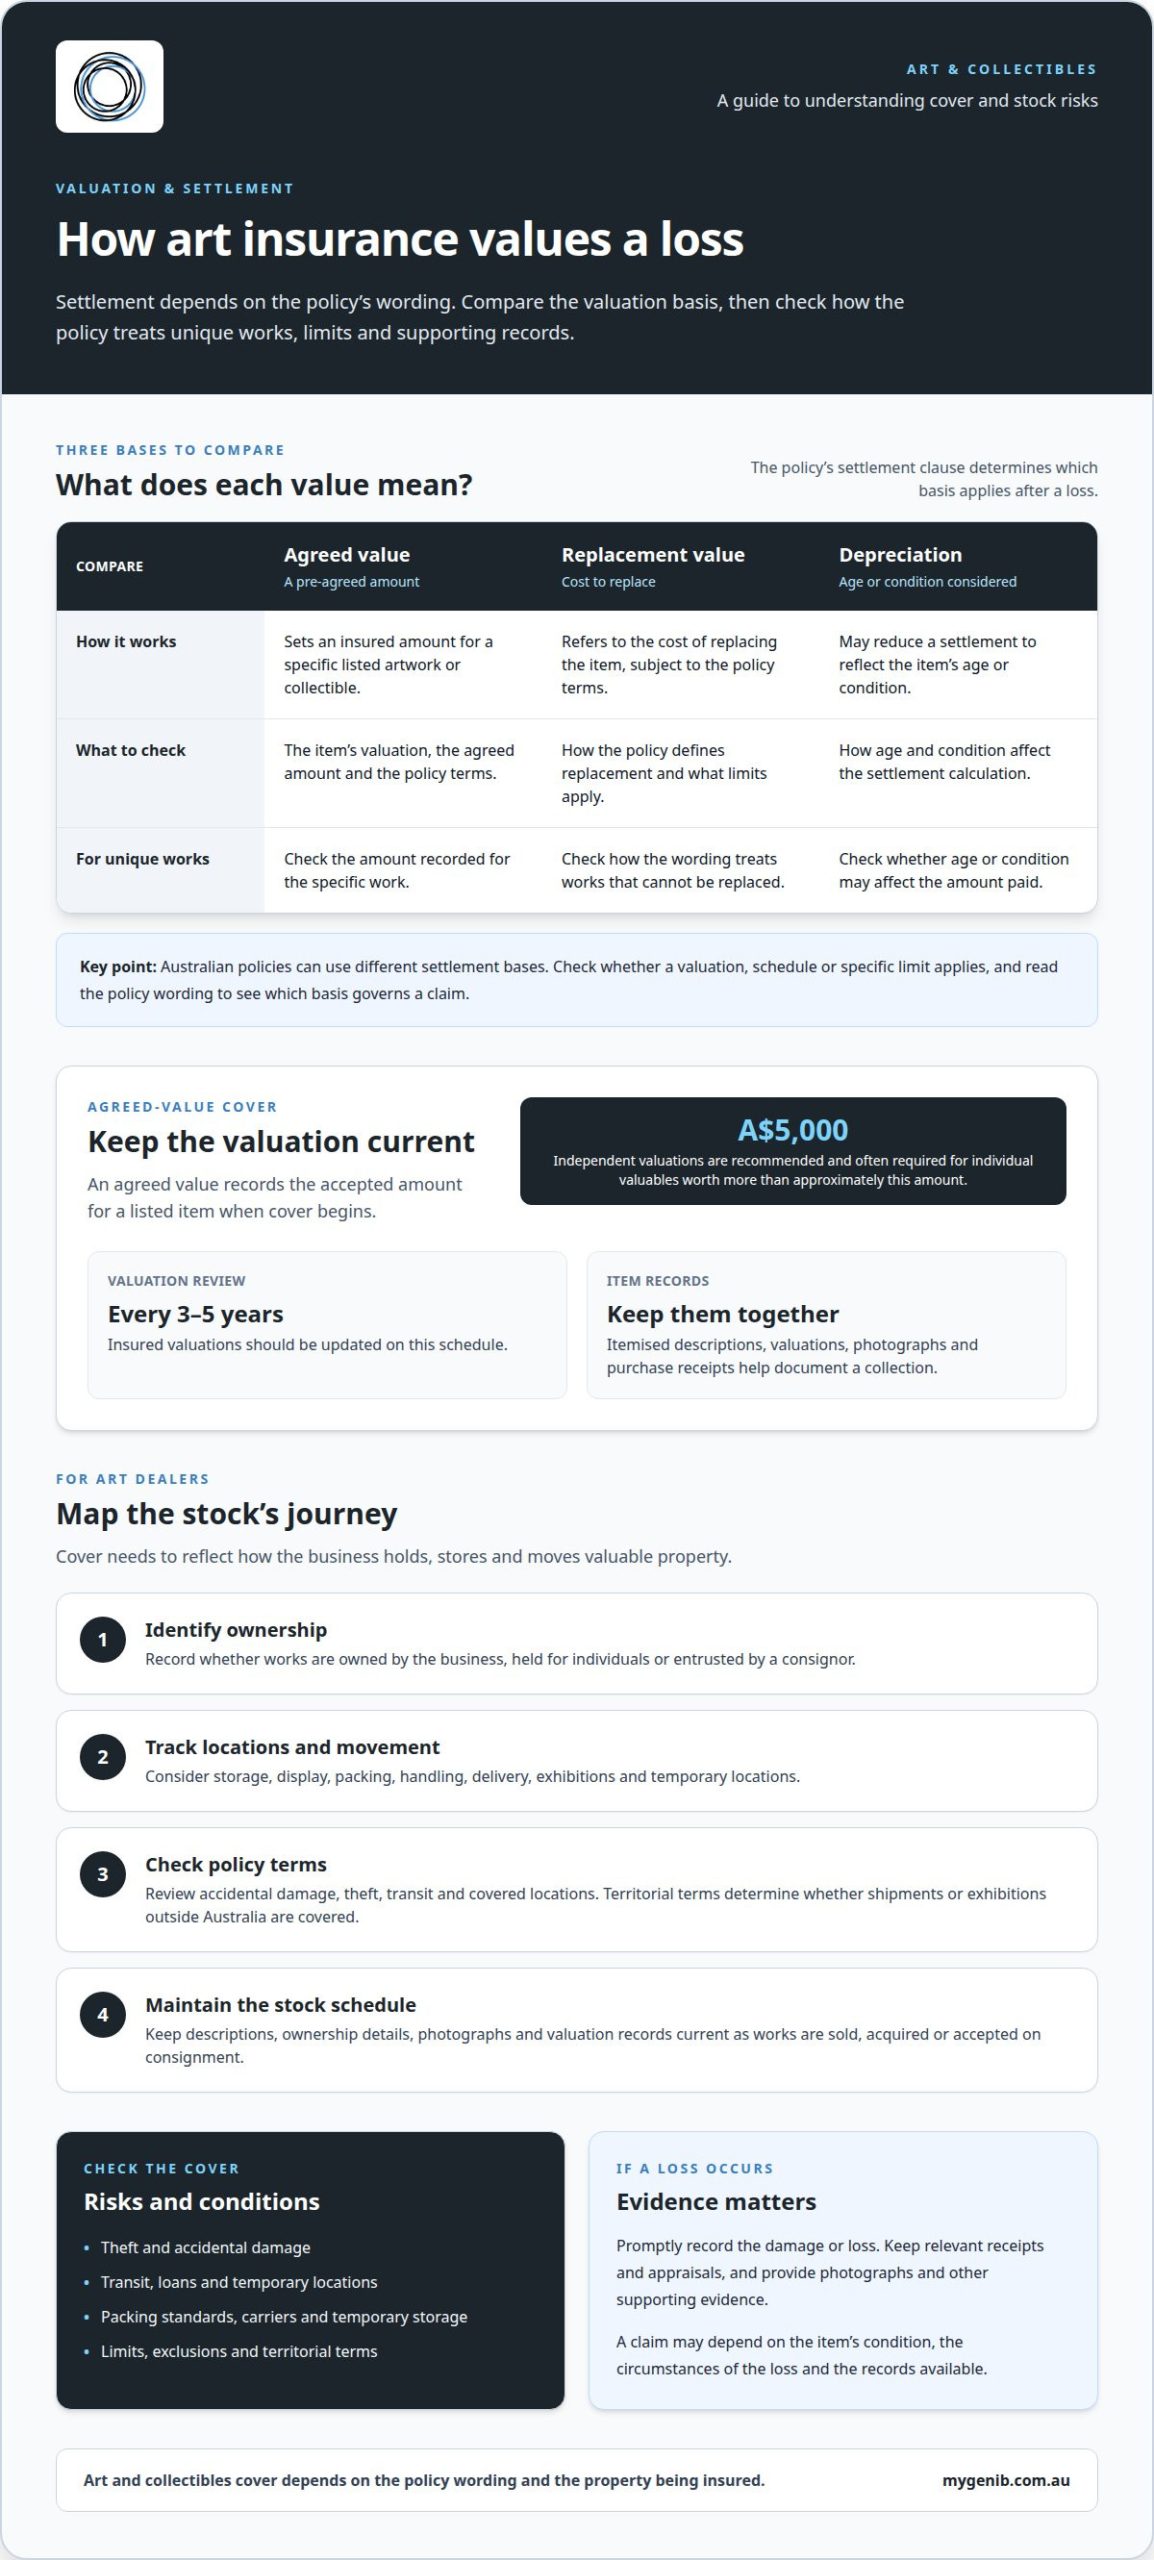
For art, antiques, sculptures and ornaments, an agreed value records the amount accepted for a listed item when cover begins. Independent valuations are recommended and often required for individual valuables worth more than approximately A$5,000; insured valuations should be updated every three to five years. Galleries, museums and auction houses may also need cover for artworks they own or hold for collectors, including during exhibitions, loans and transit. Jewellers’ Block and commercial specie cover are specialist considerations for businesses handling valuable jewellery or other high-value property; the relevant risks depend on the policy wording.
Comparing replacement value and depreciation
Australian policies can use different settlement bases, so compare how each defines the insured value. Agreed value sets an amount for the item; replacement value refers to the cost of replacing it under the policy terms, while depreciation may reduce a settlement to reflect age or condition. Check how the wording treats unique works that cannot be replaced, and whether a valuation, schedule or specific limit applies. The policy’s settlement clause determines which basis applies after a loss.
Home and contents cover for collectibles
Home and contents insurance may cover valuable art, but limits vary. To arrange cover, prepare an itemised list with valuations, photographs and purchase receipts. If you need to make a claim, promptly record the damage or loss, keep relevant receipts and appraisals, and provide photographs and other supporting evidence. Fine art insurance may also address damage while a work is on loan or temporarily housed elsewhere.
Insurance for art dealers and commercial stock
For art dealers, stock passes through several risk points: storage, display, packing, handling and delivery. A painting, for example, may be damaged in transit if it is packed or handled improperly. Fine art insurance can be tailored for galleries, dealers, artists and collectors, but the policy needs to reflect how the business holds and moves valuable property.
Start by mapping the stock’s journey. Record whether works are owned by the business, held for individuals or entrusted by a consignor. Then consider where antiques, sculptures and other items are stored, how they travel, and whether they are displayed at exhibitions or temporarily held elsewhere. These details help define the property and activities the policy is intended to cover.
Read the wording for accidental damage, theft, transit and the locations where cover applies. Don’t assume worldwide protection: the policy’s territorial terms determine whether a shipment or exhibition outside Australia is covered. Check how the policy treats packing standards, carriers, temporary storage and stock belonging to others. A claim for a damaged artwork may depend on its condition, the circumstances of the loss and the supporting records.
Keep a current stock schedule with descriptions, ownership details, photographs and valuation records. Update it as pieces are sold, acquired or accepted on consignment. This helps distinguish business stock from personal collections and gives a clearer account of what was affected after an incident. For a dealer reviewing broader commercial risks, consider your business risk arrangements alongside the specific protection needed for art stock.
Which Australian insurers offer specialist art and collectibles insurance?
Australian art cover is tailored to the collection and the risks being insured. The available research identifies specialist cover for galleries, museums, collectors and artists, but doesn’t establish a reliable list of insurer names. Focus on the policy wording and the insurer’s ability to address the collection’s ownership, display, storage, loans and transit.
For private collectors, the key question is whether cover applies only at home or also while a work is temporarily elsewhere. Galleries and museums may need to account for both artworks they own and pieces entrusted by private collectors. Art dealers should also describe their commercial stock and its movement between premises, exhibitions and customers.
Compare policies by checking the insured property, valuation basis, limits, exclusions and settlement terms. Look for clear treatment of accidental damage, theft and transit, then consider whether cover applies at every relevant location. A professional appraisal can help support the declared value of high-value works. Keep photographs, purchase records and valuations together to help substantiate the schedule and any future claim.
Ask how the policy handles changing collections. A gallery may sell one painting and accept another on consignment, while a museum may arrange a loan. The policy should reflect those changes and explain how newly acquired or entrusted works are treated. To discuss broader business risks alongside specialist art cover, review your business insurance needs.
MyGen Insurance Brokers
MyGen Insurance Brokers helps Australian businesses and individuals assess their risks and consider suitable insurance arrangements. For an art dealer, Business Insurance may address wider commercial risks, while Home Insurance may suit a private collector’s household needs. The right approach depends on what you own or handle, where it is kept and how it is used.
Bring details that shape your situation, such as whether artworks are personal possessions, business stock or held for others. MyGen takes a considered, consultative approach to your broader insurance needs and can explain where offerings such as Professional Indemnity Insurance or Commercial Motor Insurance may fit. Contact MyGen Insurance Brokers to discuss your insurance needs.
Make your next insurance decision with clarity
A collection rarely stays still. New acquisitions, sales, loans and changes in display can alter the risks around valuable property, so revisit your insurance arrangements when the collection or its use changes. For art and collectibles insurance in Australia, focus on how the cover responds to your particular circumstances, rather than relying on a policy label alone.
MyGen Insurance Brokers takes a consultative approach to assessing risks and considering suitable insurance solutions. The right approach depends on your circumstances and the risks you need to address. If you’d like to discuss your broader insurance needs, contact MyGen Insurance Brokers. A considered conversation can help you identify the next step with greater confidence.
Frequently Asked Questions
How much does art insurance cost?
The premium depends on the collection, the insured values and the risks covered. Insurers may consider the artworks’ materials, storage and security, as well as whether cover includes exhibitions, loans or transit. A collection kept securely at one address presents different underwriting details from a dealer’s stock moving between locations. The insurer provides a price after assessing the information in a quote request.
What are my art insurance options?
Options include relying on home and contents cover, arranging specialist fine art cover, or considering commercial cover for business stock. Some policies can be tailored for galleries, museums, collectors and artists. A collector who lends works may need cover that applies away from home, while a dealer should consider how stock is protected during storage and transit.
What type of insurance do I need for my artwork?
The suitable type of cover depends on who owns the work and how it is used. A private owner might consider home and contents cover or specialist fine art insurance. A dealer managing stock, or an organisation holding works on loan, needs to consider its business activities and property entrusted to it. The policy should match the artwork’s location and movements.
What does art and collectibles insurance cover in Australia?
Art and collectibles insurance in Australia may cover listed works against risks such as theft, accidental damage and loss, subject to the policy wording. Specialist cover may extend to artworks held for private collectors during exhibitions, loans and transit. Check whether the policy addresses the specific event, location and item involved, as exclusions and limits affect what a claim may recover.
How is fine art and collectible insurance valued in Australia?
Professional appraisals and item-specific records can support insured values. An appraisal can document an artwork’s description, condition and valuation basis; provenance, purchase invoices and clear photographs provide useful context. For a unique piece, keep records that distinguish it from similar works. The policy schedule and settlement terms determine how the declared value is treated if a loss occurs.