
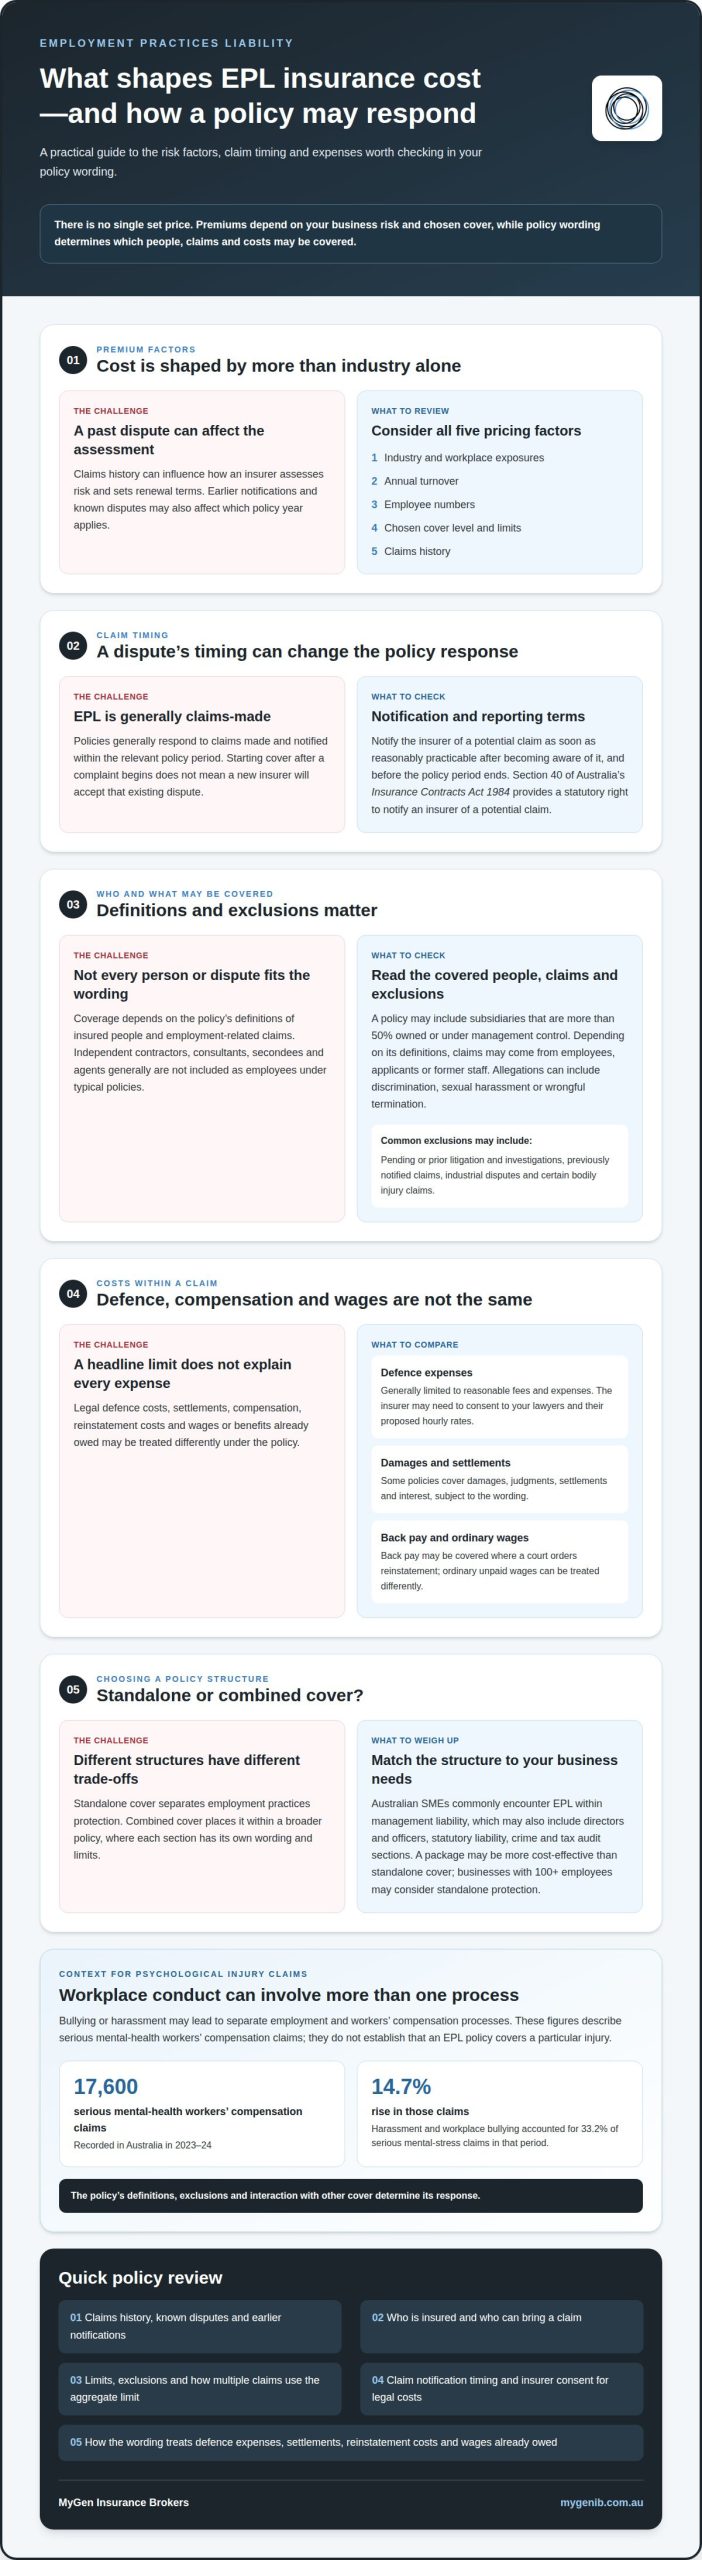
A past employment dispute can affect both your premium and how a policy responds to a later claim. Employment practices liability insurance cost depends on factors such as your industry, cover level, annual turnover, employee numbers and claims history, not a single set price. In Australia, this cover may be included in a management liability policy. Claims-made terms also mean the timing of a claim and its notification matters.
It’s understandable to want a clear figure and certainty about what a policy will pay. A useful assessment also looks closely at the wording: employment-related claims may involve allegations such as discrimination, harassment or wrongful termination, while defence costs, compensation and wages already owed may be treated differently. This article explains what the cover may address, how claims history can affect cost and which expenses may fall outside the policy, helping you assess the protection you’re considering.
Key Takeaways
- Review your claims history alongside your industry, turnover, employee numbers and chosen cover level to understand what may influence the premium.
- Check how the policy defines covered people and employment-related claims, and how its limits apply to each section.
- Separate legal defence costs from compensation and wages already owed, as the policy may treat these expenses differently.
- Pay close attention to claim notification terms and insurer consent requirements, as these can affect how a claim is handled.
Claims history
Claims history can influence an insurer’s assessment of an employer’s risk and renewal terms. Past disputes matter because employment practices liability policies generally respond to claims made and notified within the relevant policy period.
Policy wording defines which entities and people are insured, and who can bring a claim. A policy may include subsidiaries that are more than 50% owned or under management control. It may cover allegations from employees, applicants or former staff, depending on its definitions. Independent contractors, consultants, secondees and agents generally aren’t included as employees under typical policies. Known disputes, earlier notifications and the policy’s reporting provisions can affect which annual period applies.
Notify the insurer of a potential claim as soon as reasonably practicable after becoming aware of it, and before the policy period ends. Under section 40 of Australia’s Insurance Contracts Act 1984, an insured has a statutory right to notify an insurer of a potential claim. Starting cover after a complaint begins doesn’t mean a new insurer will accept that existing dispute.
Claim settlements and legal expenses
Claim settlements resolve employment disputes, while legal expenses arise from defending them. Both can affect a business’s financial exposure and claims record.
These examples show why the type of claim and defence costs matter, not just settlement payments.
Mental health and psychological injury claims
Psychological injury claims involve mental harm linked to workplace events, including bullying or harassment. They matter because the same conduct may lead to separate employment and workers’ compensation processes.
Australia recorded 17,600 serious mental-health workers’ compensation claims in 2023-24, a rise of 14.7%. Harassment and workplace bullying accounted for 33.2% of serious mental-stress claims in that period. These figures don’t establish that an employment practices policy covers a particular injury. The policy’s definitions, exclusions and interaction with other cover determine its response.
What is Employment Practices Liability insurance?
Employment Practices Liability insurance may cover defined claims arising from employment-related wrongful acts, subject to the policy wording. It isn’t required by Australian state law in the same way workers’ compensation is.
Policy features, limits and exclusions
Policy features define covered claims, insured people, exclusions and the maximum payment available. The aggregate limit usually applies across the policy’s one-year period, so multiple claims may draw on the same pool.
Cover may address allegations such as discrimination, sexual harassment or wrongful termination, including dismissal disputes, subject to policy definitions. Policies commonly exclude pending or prior litigation and investigations, previously notified claims, industrial disputes and certain bodily injury claims. Workplace policies and employee training can help manage conduct risks, but they don’t replace a careful review of exclusions and limits.
Standalone and combined EPL policies
Standalone cover separates employment practices protection, while combined cover places it within a broader policy. Australian SMEs commonly encounter EPL within management liability, which may also include directors and officers, statutory liability, crime and tax audit sections. A package may be more cost-effective than standalone cover, while businesses with 100+ employees may consider standalone protection.
Policy limits also vary across management liability options, and each section responds according to its own wording. For a wider view of business risks and cover types, explore business insurance options.
Defence costs, compensation and wage exclusions
EPL insurance costs reflect industry risks, turnover, employee numbers, cover level and claims history. Defence expenses, settlements and compensation can also affect the protection a business needs.
Policy wording distinguishes legal defence costs from compensation, reinstatement costs and wages or benefits already owed. Some policies cover damages, judgments, settlements, interest and defence costs. Back pay may be covered where a court orders reinstatement, but ordinary unpaid wages can be treated differently. Defence costs are generally limited to reasonable fees and expenses. The insurer may need to consent to your chosen lawyers and their proposed hourly rates.
Industry affects risk assessment because workplace exposures differ. A business facing regular harassment complaints or complex termination disputes may present different risks from one with fewer employment-related exposures. Insurers also consider annual turnover, workforce size, chosen limits and prior claims. These factors shape employment practices liability insurance cost, rather than industry alone determining the premium.
To manage risk, seek employment advice before a major dismissal or other significant decision, and preserve investigation records. Clear workplace procedures and documented actions can help explain how a dispute was handled. When comparing insurance cover, look beyond the headline limit: check how the policy treats defence expenses, wage payments and settlements, and whether it requires consent for legal representation.
For a broader review of business risks, explore Business Insurance options alongside your employment cover considerations.
MyGen Insurance Brokers
MyGen Insurance Brokers can help you consider how employment-related risks fit within your wider business insurance needs. When weighing policy options, focus on what the protection is intended to cover, how its limits work and which exclusions could matter to your business.
Our brokers can discuss your business circumstances and help you understand the insurance considerations involved. This can be useful when reviewing existing arrangements, assessing changing workforce needs or considering how employment-related exposures sit alongside other business risks. The policy wording remains central: it sets out covered claims, conditions and exclusions. Reviewing it carefully can clarify the scope of protection.
Contact MyGen Insurance Brokers to discuss your business insurance needs.
Make your next insurance decision with clarity
Use your workplace risk profile to guide the next conversation, rather than focusing on the premium alone. Understanding employment practices liability insurance cost can help you assess how employment-related risks fit alongside your wider business protection needs.
MyGen Insurance Brokers offers Business Insurance, Professional Indemnity Insurance and Commercial Motor Insurance. Each addresses different business risks. Consider which exposures matter to your operations and whether your existing arrangements reflect them.
For a considered discussion about your insurance needs, get in touch with MyGen Insurance Brokers. A thoughtful review can help you take your next step with greater confidence.
Frequently Asked Questions
How can you save money on EPLI?
Reduce avoidable workplace risks with consistent recruitment, performance management and complaint-handling processes. For example, keep clear records of decisions and apply the same procedures in comparable situations. These practices can help limit disputes and support a stronger risk profile, but they don’t guarantee a lower premium. Insurers also weigh factors such as your business activities, workforce and previous claims.
Should you get standalone EPLI or Management Liability insurance?
Choose whether you need employment cover alone or alongside other management risks. A business seeking broader protection may consider a Management Liability package, while standalone cover focuses on employment-related claims. Compare how each option defines insured people, handles legal costs and sets EPL limits. The suitable structure depends on your exposures and the wording available for your business.
Can I choose which components to include?
The components available often depend on the insurer and policy structure. A Management Liability package may combine cover for directors and officers, employment practices, statutory liability, crime and tax audit risks. Before selecting sections, identify the risks you want addressed and review each component’s limits, exclusions and conditions. A section’s inclusion in a package doesn’t mean it applies to every dispute.
How much does EPLI cost in Australia?
Employment practices liability insurance cost varies with a business’s industry, turnover, employee numbers, claims history and selected limits. Policies may be standalone or part of Management Liability, so the premium also reflects the structure and components selected. There isn’t one rate for every Australian employer. Your business’s risk profile and the policy terms are central to pricing.
Is it possible to take out an EPL policy as part of other liability insurance policies?
Yes. In Australia, employment practices cover may be included in a Management Liability policy, offered as an extension to Professional Indemnity or directors and officers liability cover, or available as standalone insurance. These arrangements aren’t interchangeable. Review how the employment section defines claims and insured parties, and how its limits operate within the wider policy.