
Your workshop’s insurance may not protect tools you own. Tools of trade insurance for apprentices can cover portable equipment against loss, theft or accidental damage in transit or onsite, subject to the policy limits and security conditions.
It’s easy to assume that tools kept at work are covered by the workshop’s policy. In Australia, these policies generally cover business-owned equipment, not staff-owned tools unless they’re specifically included. This guide explains what portable equipment cover may protect, why theft claims can depend on how tools were secured, and where a workshop policy may leave a gap. You’ll also learn how apprentices and new sole traders can arrange cover for their own equipment and decide which option suits the way they work.
Key Takeaways
- Understand how storage and security conditions affect theft cover, particularly when tools stay in a vehicle overnight.
- See why high-value equipment, hired tools and permanently fixed items can need careful attention in a workshop policy.
- Explore the different cover arrangements available to apprentices and new sole traders, including standalone portable equipment insurance.
- Keep receipts, photos and serial numbers for valuable tools to help establish ownership if you need to make a claim.
What does portable equipment insurance cover?
Portable equipment insurance can cover business equipment such as tools of trade and stock. For apprentices, the key question is whether personally owned tools are insured through an employer’s policy or covered individually.
Cover for personally owned tools
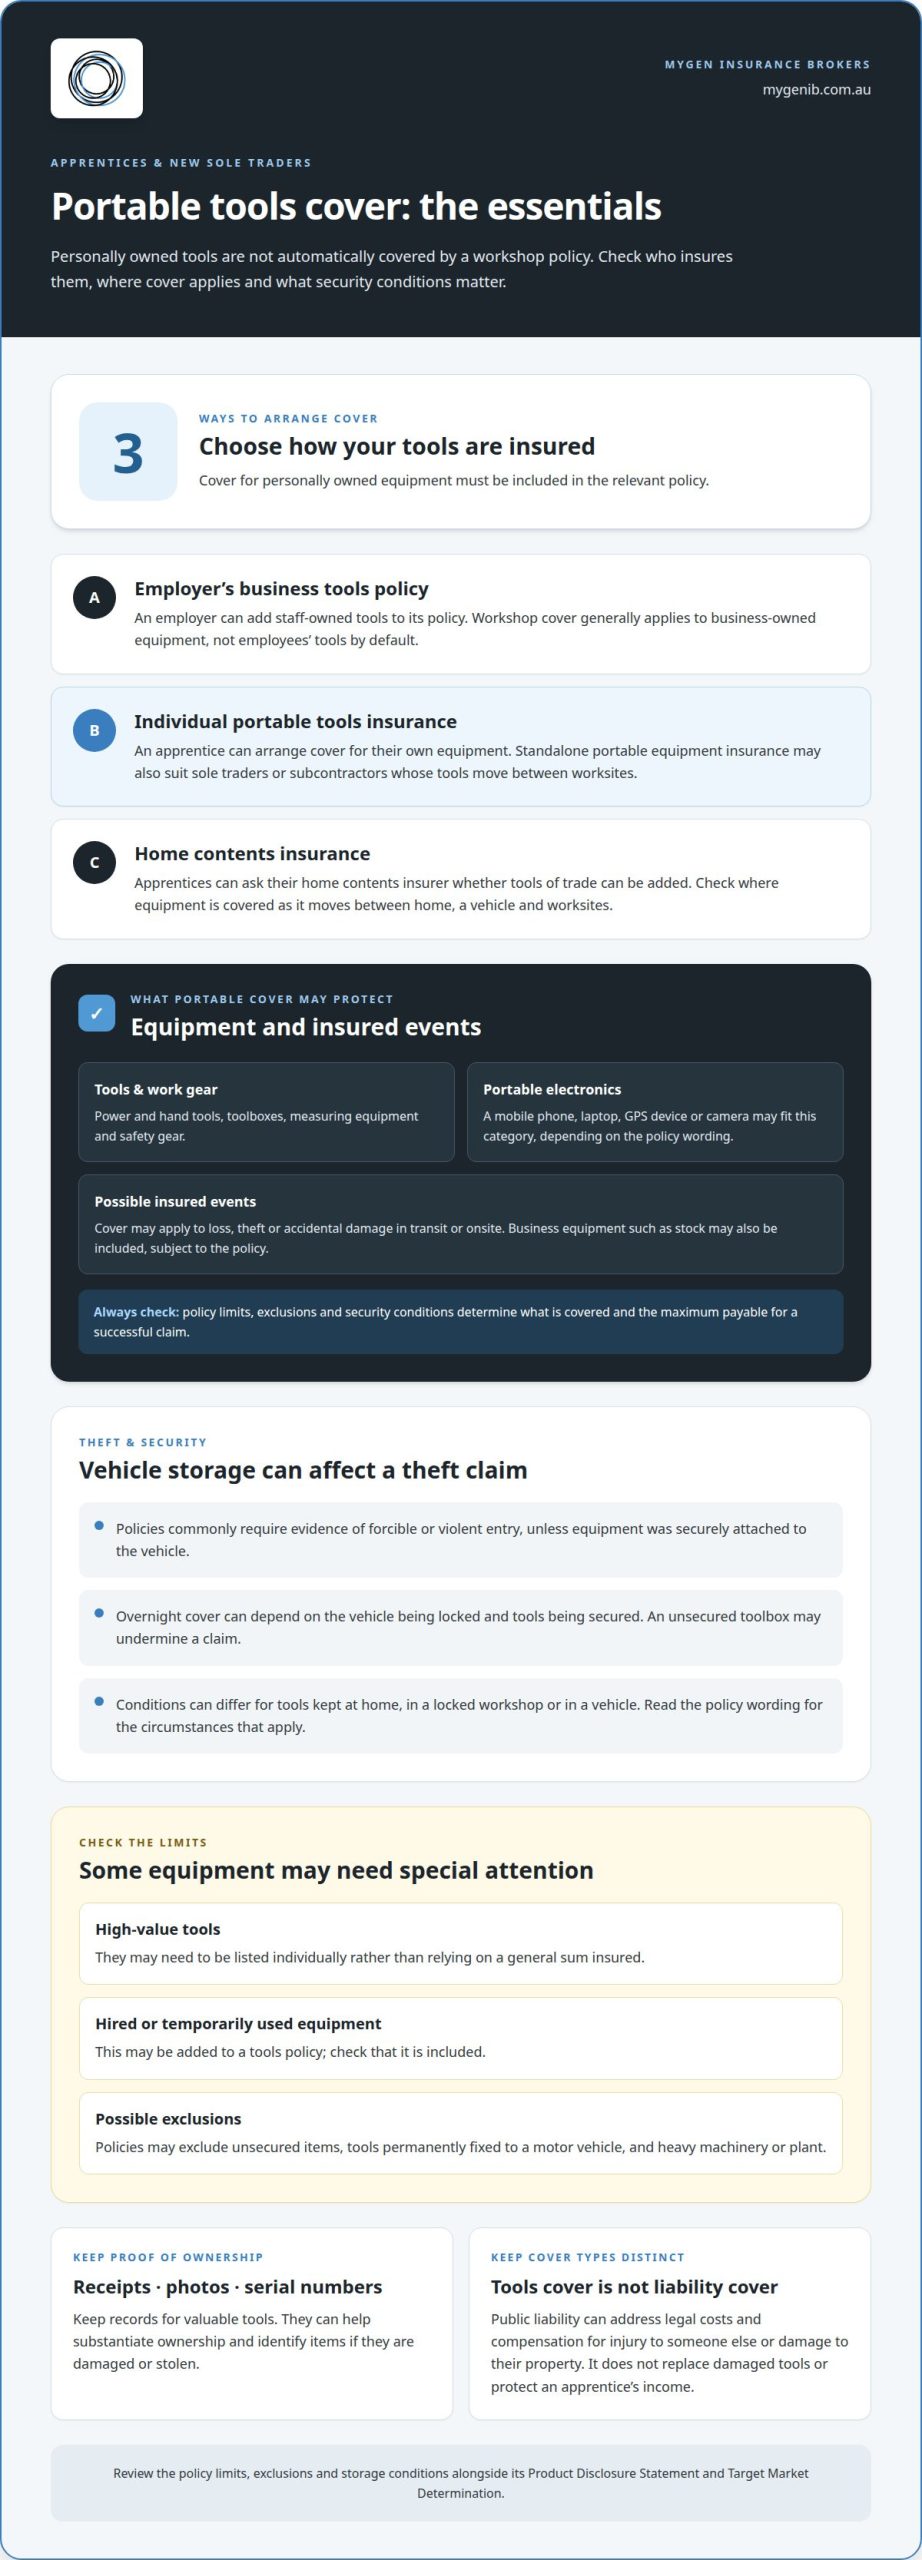
Personally owned tools are covered only when the relevant policy includes them. An employer can add staff-owned tools to its business tools policy, or an apprentice can arrange individual portable tools insurance. This distinction matters because a workshop policy generally covers business-owned tools, not employees’ equipment by default. Workers compensation addresses work-related injury or illness, not tools that are lost, stolen or damaged.
Portable equipment included in cover
Portable equipment cover may include power and hand tools, toolboxes, measuring equipment, safety gear and portable electronics. A mobile phone, laptop, GPS device or camera may fit this category, but the policy wording determines what’s covered. Cover can apply to loss, theft or accidental damage in transit or onsite. Theft from a vehicle may depend on security conditions, such as locked storage or evidence of forced entry.
Cover for tools and employee apprentices
Portable tools cover can suit apprentices and subcontractors who rely on their own equipment for work. Employee apprentices are generally covered by their employer’s public liability insurance, so they don’t usually need separate public liability cover. Public liability can address legal costs and compensation if trade work injures someone else or damages their property. It’s separate from equipment insurance: a liability policy won’t replace damaged tools or protect an apprentice’s income.
Claims, cover amounts and policy choices
There’s no single cover amount for every trade: policy limits set the maximum payable for a successful claim. When comparing cover, review the limits, exclusions and security conditions, along with the Product Disclosure Statement and Target Market Determination. Membership of a trade association, union or training organisation doesn’t by itself establish cover for personally owned tools; the employer’s policy or an individual portable policy must include them. Receipts, photos and serial numbers can help substantiate ownership if you claim. Keep these records for valuable equipment and provide them with the claim details requested by the insurer.
Limits of a workshop tools and equipment policy
A workshop policy can protect business equipment, but its scope may not match every tradie’s needs. Ownership, location, item value and policy exclusions all affect what’s covered.
Limits of workshop equipment cover
A workshop tools policy generally covers business-owned tools, not staff-owned equipment unless it’s included. This matters when an apprentice brings a personally owned drill or toolbox to work. High-value tools may need to be listed individually, rather than relying on a general sum insured, so their value is recognised within the policy.
Portable equipment cover can also be arranged as a standalone policy. This may suit a sole trader or subcontractor whose main concern is tools moving between worksites, rather than broader business risks. Hired or temporarily used equipment may be added to a tools policy, while heavy machinery and plant may fall outside portable cover. A broker can help assess how equipment ownership and use affect the cover arrangement.
Exclusions and security conditions
Policy exclusions describe events, conditions and types of loss that aren’t covered. Portable equipment insurance may exclude unsecured items, tools permanently fixed to a motor vehicle, and heavy machinery or plant. These limits matter when a work vehicle carries equipment that has been installed or left loose in its tray.
For theft, policies commonly require evidence of forcible or violent entry, unless equipment was securely attached to the vehicle. Overnight cover can depend on whether the vehicle was locked and tools secured; leaving a toolbox unsecured may undermine a claim. Conditions can differ for tools stored at home, in a locked workshop or in a vehicle. For help considering business risks alongside equipment cover, explore business insurance options.
Tools insurance for apprentices and new sole traders
For apprentices, tools of trade insurance is portable equipment cover for work tools against insured loss, theft or accidental damage. It can help protect equipment used onsite or while travelling between jobs, where a workshop policy may not cover personally owned items.
If you own a drill, test meter or toolbox as an apprentice, the practical question is who insures it. Your employer can include staff-owned equipment under its business tools policy, or you can arrange individual cover. A workshop should review its tool insurance arrangement when a new apprentice or employee joins, so ownership and cover responsibilities are clear.
New sole traders and subcontractors can consider standalone portable equipment insurance when tools travel between jobs. This may be enough if broader insurance isn’t required by law or contract. If you take on wider business risks, tools cover alone won’t address every exposure, such as liability for injury or property damage.
Before choosing cover, list valuable tools and equipment, especially items that would be difficult to replace. Keep receipts, photos and serial numbers together: these records can help substantiate ownership when you claim. Clear records are particularly useful if tools are damaged or stolen, because they identify the specific items involved. Read the policy’s exclusions and storage conditions alongside its cover limits, rather than focusing only on the types of tools insured.
Apprentices can also ask their home contents insurer whether tools of trade can be added to their contents insurance. That option and a portable policy are different arrangements, so understand where equipment is covered as it moves between home, a vehicle and worksites. For a broader view of business risks as you start out, explore business insurance guidance.
MyGen Insurance Brokers
MyGen Insurance Brokers helps apprentices and new sole traders understand how equipment fits into their wider business risks. If your tools travel between worksites, or you’re moving from employment to self-employment, we can review your circumstances and discuss suitable insurance options.
Business Insurance can help address business risks beyond tools, while Commercial Motor Insurance may be relevant if a vehicle is part of your work. If you work from home or own property, Home Insurance may also be relevant to your broader arrangements. The right mix depends on how you work, what you own, and where you use or store it.
Contact MyGen Insurance Brokers to discuss your situation and the insurance considerations that matter to your work.
Make your next move with a clearer risk picture
Your work can change as you move from apprenticeship towards running jobs independently. Use that transition as a chance to review how your insurance needs fit together, rather than carrying assumptions from employment into self-employment. The right questions depend on the work you take on and how your business operates.
MyGen Insurance Brokers can help you consider business risks through Business Insurance, Professional Indemnity Insurance and Commercial Motor Insurance. If you’re weighing up tools of trade insurance for apprentices or planning your next step as a sole trader, a conversation can help clarify your priorities.
Contact MyGen Insurance Brokers to discuss your circumstances and take a considered next step with confidence.
Frequently Asked Questions
How can I get tool insurance?
Start by identifying which tools you own, where you use them and how you transport them. For tools of trade insurance for apprentices, an employer may arrange cover for staff-owned equipment through its business policy, or you can explore individual portable equipment cover. A broker can help relate these details to policy limits and exclusions. Keep an inventory so the items being insured are clearly identified.
Do apprentices need insurance?
An apprentice employed by a business generally doesn’t need separate public liability cover for work-related third-party injury or property damage, as the employer’s cover generally applies. That doesn’t automatically protect personally owned tools. For example, if you supply your own impact driver, establish whether the employer’s policy insures it or whether you need separate equipment cover. A self-employed apprentice has different business risks to consider.
What is tools & stock insurance?
Tools and stock insurance covers business equipment used to do work and goods held for sale or supply. For example, a carpenter’s tools help complete jobs, while timber purchased for a customer’s project is stock or work material. Policies set their own insured items, limits and exclusions, so the label alone doesn’t tell you whether a particular item or loss is covered.
Can my apprentice’s tools be added to the business policy?
Yes, an employer can add staff-owned tools to its business tools and equipment policy. This can make the arrangement clearer for a workshop with several apprentices bringing their own gear. Record whose tools are included and their details, particularly for valuable items. If your tools aren’t included, you can consider arranging individual portable equipment cover instead.
Does tools of trade insurance cover an apprentice’s tools if they are stolen from a vehicle or worksite?
Theft may be covered, but it depends on the policy’s security conditions and where the tools were stored. A vehicle claim may require evidence of forced entry or that tools were securely attached to the vehicle. At a worksite, a locked workshop or secured toolbox may matter. An unlocked vehicle or unattended, unsecured equipment may fall outside cover, so check the storage conditions.