Relying on a “tick and flick” approach to your business insurance is the fastest way to leave your hard-earned assets unprotected in 2026. We understand how frustrating it feels to be treated like just another number in an automated system, especially when you’re facing rising premiums that don’t seem to offer any extra value. Using a comprehensive business insurance renewal checklist 2026 ensures you don’t fall victim to hidden exclusions in the fine print that could leave you stranded when you need support the most.
We’ve developed this guide to help you reclaim control, close dangerous coverage gaps, and secure your company’s future with total certainty. This methodical review covers your current risks, from the impact of inflation on property replacement to the evolving complexities of cyber threats. We’ll help you move past the automated noise to build a policy that actually matches your reality.
Key Takeaways
- Learn why automated “tick and flick” renewals fail to protect your assets in a shifting economy and how to avoid being treated like just another number in a system.
- Follow our comprehensive business insurance renewal checklist 2026 to conduct a thorough audit of your operations, ensuring your liability limits keep pace with your revenue growth.
- Understand how 2026 inflation and supply chain disruptions affect your asset valuations so you can close dangerous coverage gaps before they become costly liabilities.
- Discover the peace of mind that comes from a consultative “deep-dive” review, moving beyond generic quotes to find a policy tailored to your specific industry risks.
The 2026 Risk Landscape: Why a ‘Set and Forget’ Renewal Fails
The Australian market in 2026 doesn’t reward complacency. If you’ve been tempted to just sign the renewal papers without a second look, you’re essentially gambling with your company’s future. Automated algorithms often miss the nuances of your specific trade, treating your livelihood as a data point rather than a complex operation. This is why a thorough business insurance renewal checklist 2026 is vital; it forces a move away from generic “tick and flick” processing toward a strategy that actually protects you.
Inflation hasn’t just affected your weekly groceries; it’s fundamentally shifted the cost of rebuilding premises and replacing specialised equipment. If your asset valuations haven’t been updated since last year, you’re likely carrying a significant shortfall. We’ve seen supply chain disruptions push lead times and costs to record highs, meaning a standard Business Owner’s Policy (BOP) might no longer provide the safety net you expect.
To better understand how to prepare for your upcoming review, watch this helpful video:
This year is the time to look beneath the surface. While a basic business insurance policy might’ve worked when the market was stable, today’s environment demands precision. Using a detailed business insurance renewal checklist 2026 allows us to focus on human-centric risk discovery. A computer simply can’t understand the unique ways your business has pivoted or expanded over the last twelve months.
Evolving Regulatory and Economic Pressures
ASIC and the ATO have sharpened their focus on corporate governance and director responsibilities this year. These regulatory shifts mean your liability exposure has likely increased without you realising it. When replacement values outpace policy limits, the hidden cost of underinsurance becomes a terminal threat to your cash flow. We help you identify these gaps before a claim occurs, ensuring your coverage remains a stable, calming force for your team.
Your Essential 2026 Business Insurance Renewal Checklist
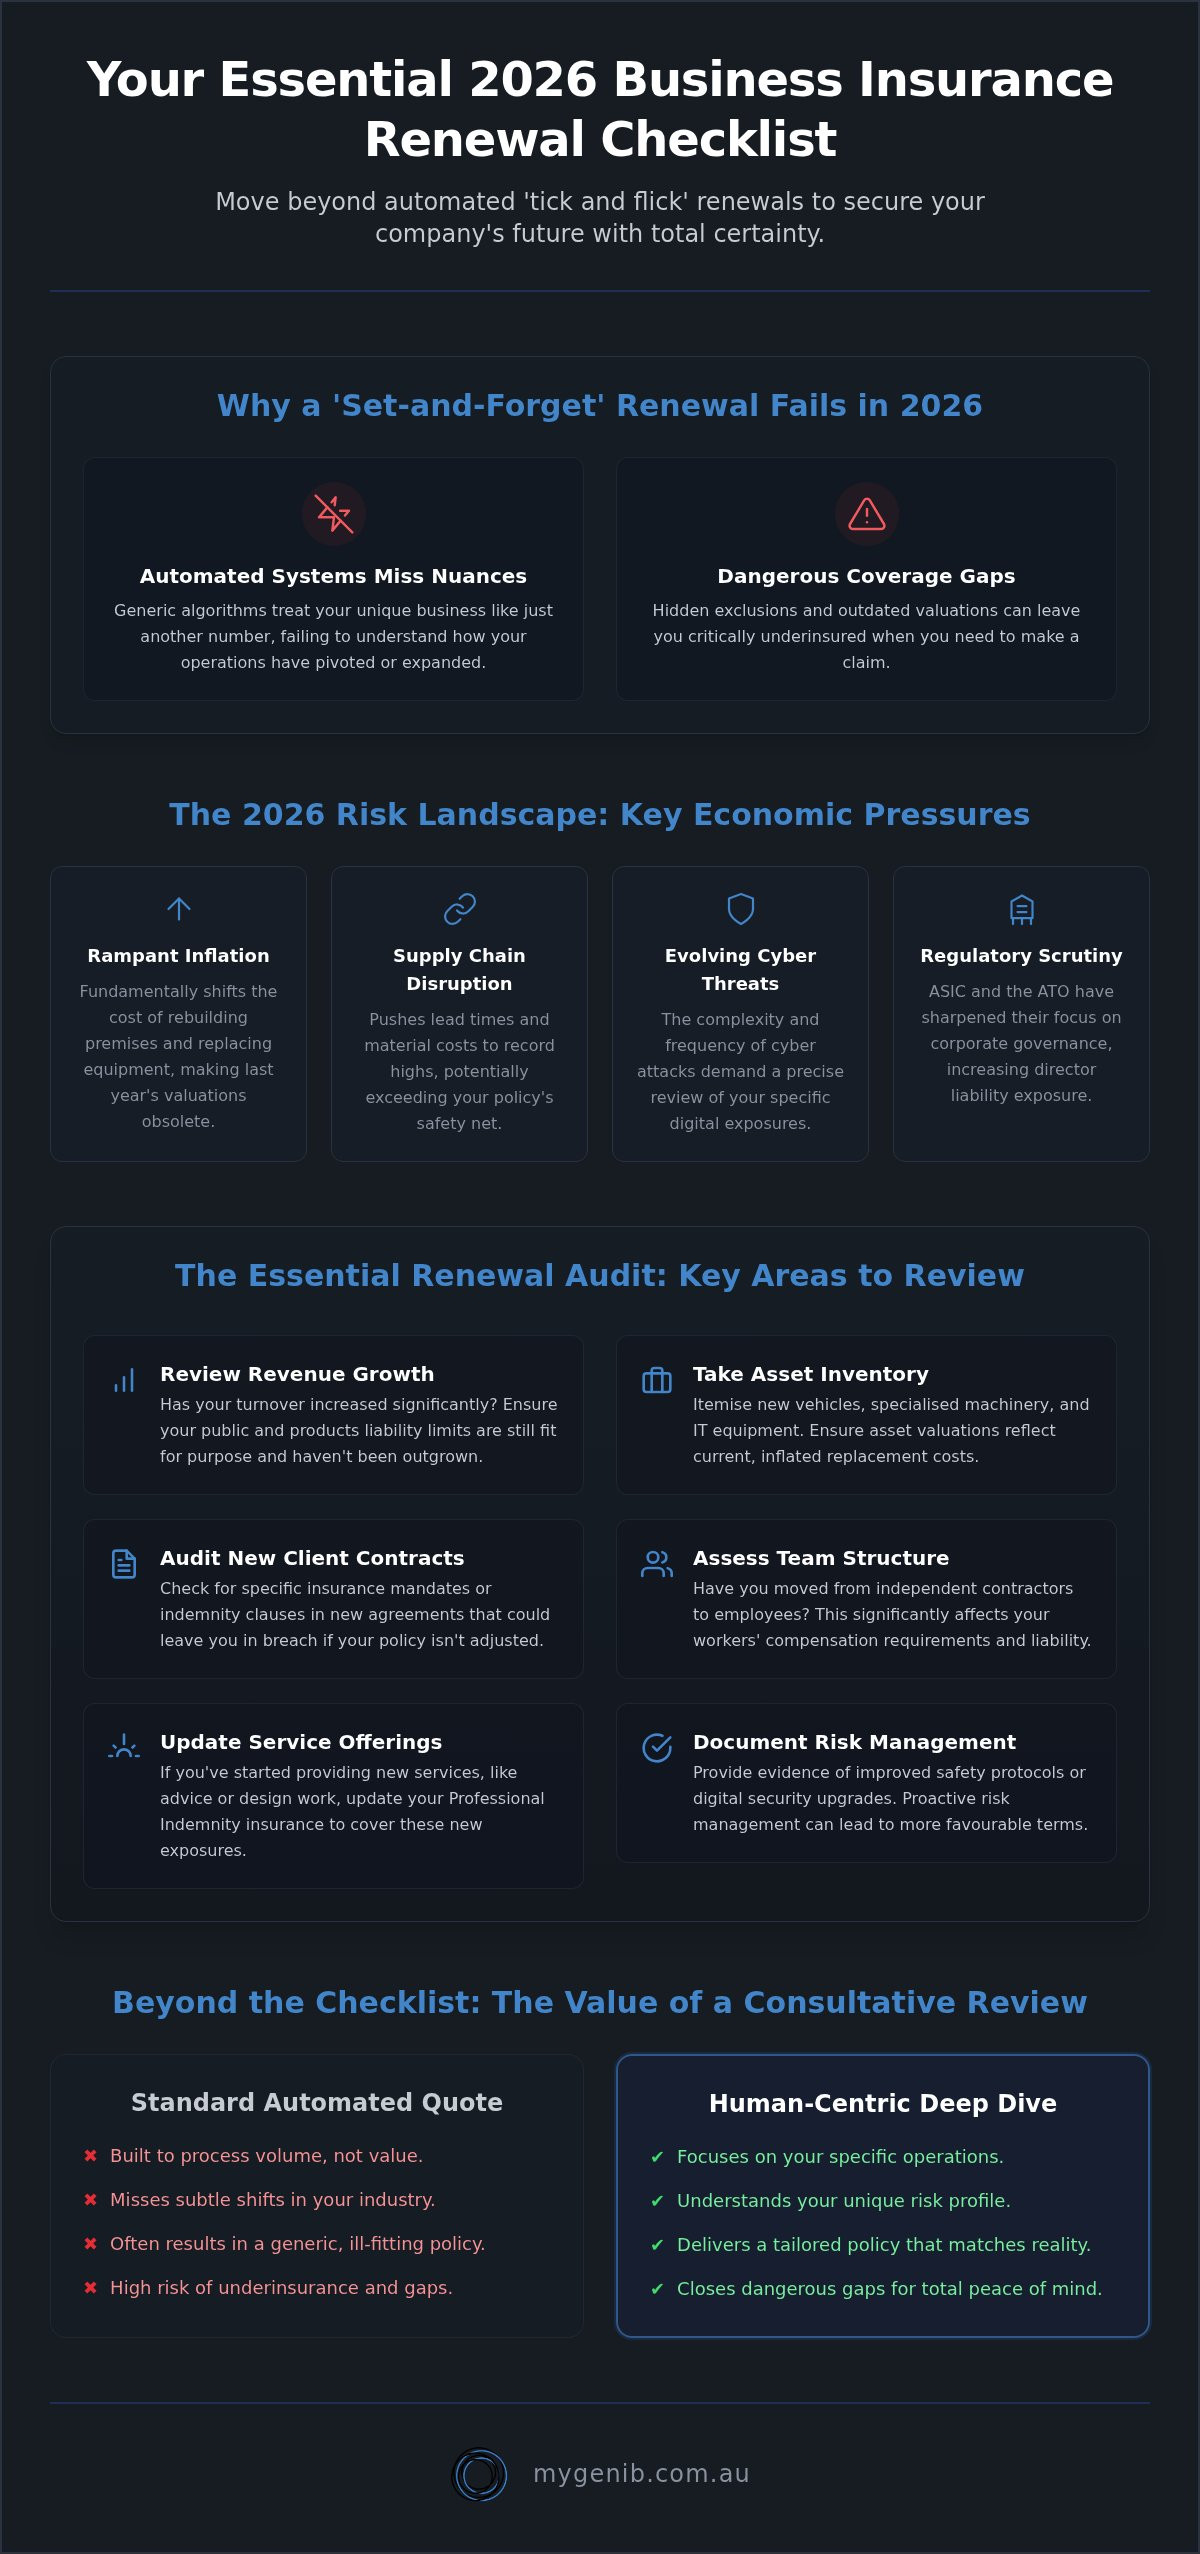
Preparing for your renewal requires more than just checking your bank balance. Our business insurance renewal checklist 2026 provides a structured way to look at your operations with the diligence they deserve. Start by examining your revenue growth. If your turnover has increased significantly this year, your existing liability limits may no longer be fit for purpose. While a state-issued guide to commercial insurance offers a helpful baseline for understanding policy structures, your specific Australian context requires a more nuanced approach to risk.
We also suggest auditing your service offerings. If you’ve started providing advice or design work, you’ll need to update your professional indemnity insurance to reflect these new exposures. We also recommend documenting any improved safety protocols or digital security upgrades. Demonstrating proactive risk management can often help us negotiate more favourable terms on your behalf.
Operations, Assets, and People
Take a physical inventory of your business. Have you acquired new vehicles, laptops, or specialised machinery in the last 12 months? Itemising these assets ensures you aren’t left with a shortfall when replacement costs are at an all-time high. It’s also vital to assess changes in your team structure. Moving from independent contractors to employees affects your workers’ compensation requirements and entity structure. Don’t forget to review new client contracts; these often contain specific insurance mandates that could leave you in breach if your policy hasn’t been adjusted. If you feel like your current setup is missing these details from your business insurance renewal checklist 2026, reaching out for a consultative review can provide the certainty you need.
Beyond the Checklist: The Value of a Consultative Review
While ticking off items on your business insurance renewal checklist 2026 gives you a head start, it doesn’t replace the intuition of a seasoned professional. Automated systems are built to process volume, not to understand the subtle shifts in your industry’s risk profile. A “skimmer” quote might look attractive on paper, but it often ignores the underlying complexities that a manual deep-dive assessment would uncover. We focus on looking beneath the surface to ensure no detail is left to chance.
Transitioning from confusion to clarity happens when you partner with expert insurance brokers who treat your business as their own. It’s about Rethinking Insurance Coverage to move beyond the standard templates that fail to account for your specific growth. A personal broker identifies the gaps that algorithms consistently miss, such as the nuances of a new service line or a unique contractual obligation that an automated system would simply overlook.
Designing a Protective Mentorship
We view our role as a protective mentor rather than just a service provider. Part of this involves a meticulous claims history analysis, which we use as a lever to negotiate better 2026 premiums with underwriters. By presenting a clear, well-documented picture of your risk management efforts, we can often secure value that automated systems simply can’t access. A tailored policy is the only way to achieve genuine peace of mind, knowing your coverage is as unique as the business you’ve built.
Taking the Next Step Toward Certainty
Navigating a shifting Australian market requires more than just a standard review. By following our business insurance renewal checklist 2026, you’ve taken a vital step toward closing coverage gaps and protecting your livelihood. True peace of mind doesn’t come from an automated algorithm; it comes from a deep-dive investigation into your specific risks. We believe in looking beneath the surface to ensure your policy matches your current reality perfectly.
With over 20 years of industry experience, we reject “tick and flick” quotes in favour of a personalised risk assessment for every client. We’re here to act as your protective mentor through the entire process. Book a consultative 2026 renewal review with MyGen today to trade confusion for total certainty. Your business deserves a steady hand and a partner who is genuinely invested in your security.
Frequently Asked Questions
When should I start the business insurance renewal process for 2026?
You should begin the renewal process 90 to 120 days before your current policy expires. This timeframe allows us to collect the necessary data and perform a manual risk assessment without the stress of a last-minute rush. Starting early provides the leverage needed to negotiate with insurers, ensuring you aren’t forced into a generic policy that doesn’t fit your needs.
What happens if my business has changed structure since my last renewal?
Any shift in structure, such as incorporating or changing partnership details, requires an immediate update to your policy. If the legal entity named on your insurance doesn’t match your current business structure, you risk a total loss of cover during a claim. We work with you to transition your protection seamlessly, ensuring your new entity is fully recognised and protected from day one.
How do I know if my current liability limits are still sufficient for 2026?
Your limits are likely insufficient if your annual turnover has increased or if you’ve signed contracts with higher indemnity requirements this year. Reviewing your business insurance renewal checklist 2026 helps you pinpoint where your growth has created new exposures. We’ll compare your current limits against industry benchmarks to ensure your safety net is wide enough to catch a worst-case scenario.
Can an insurance broker help me lower my premiums during renewal?
Brokers help lower premiums by presenting a comprehensive “risk story” that proves your business is well-managed and proactive. By using a business insurance renewal checklist 2026 to document your improved security measures or staff training, we give underwriters a reason to offer more competitive rates. We look for suitability and depth rather than just the cheapest possible price point.