
Business growth can leave your assets underinsured, even if your policy hasn’t changed. Underinsurance means your cover is insufficient for the value of your business assets. The sum insured is the maximum your insurer will pay for a claim. Avoiding underinsurance for your business assets starts with keeping insured values aligned with what you own and what it would cost to replace or rebuild today.Cover can fall behind as you buy equipment, increase stock, expand or face rising rebuilding costs. A figure that once seemed reasonable may no longer reflect the business you run today.This article explains how to review your sums insured after growth or purchases, estimate current replacement and rebuilding costs, and spot changes that can quietly create a shortfall. A clear review process helps you make informed decisions about protecting the assets your business relies on. Key Takeaways Review insured values after buying equipment, increasing stock, moving premises or changing how your business operates. Base building cover on the cost to rebuild, and contents cover on the cost to replace items new, rather than relying on past values. Check policy limits, exclusions and excesses alongside your asset values so you understand how they may affect a claim. A structured review of your business risks and cover can help identify where tailored Business Insurance may fit. Table of Contents 1. Updating sums insured after business growth or purchases 2. Building reconstruction and contents replacement costs 3. Why business assets become underinsured MyGen Insurance Brokers: Business Insurance 1. Updating sums insured after business growth or purchases A sum insured is the maximum an insurer will pay for a claim. If you buy machinery, increase stock, renovate or expand, compare the values listed in your policy with what the business owns now. New purchases or higher stock levels can create a gap if insured values stay the same. To avoid underinsurance for your business assets, update your asset schedule and notify your insurer when purchases or operations change.Review your cover at least once a year, before renewal, and after a major business change. Check policy limits, exclusions and excesses, and look for an underinsurance clause that could reduce a payout if your assets aren’t insured for their full value. Compare the cover basis and limits with each asset’s current replacement value and rebuilding cost. A broker can assess how equipment purchases, contracts, relocations and operational changes affect your risks and cover.Keep a clear record of your assets for any future claim. Store purchase invoices, asset registers, serial numbers and photographs together, and understand the evidence requirements and lodgement timeframes in your policy. These records can help substantiate ownership and value when you make a claim.Insurance gaps affect businesses and economies alike. The Insurance Council of Australia reported that 26% of Australian SMEs and … [Read more...] about Avoiding underinsurance for business assets as costs change
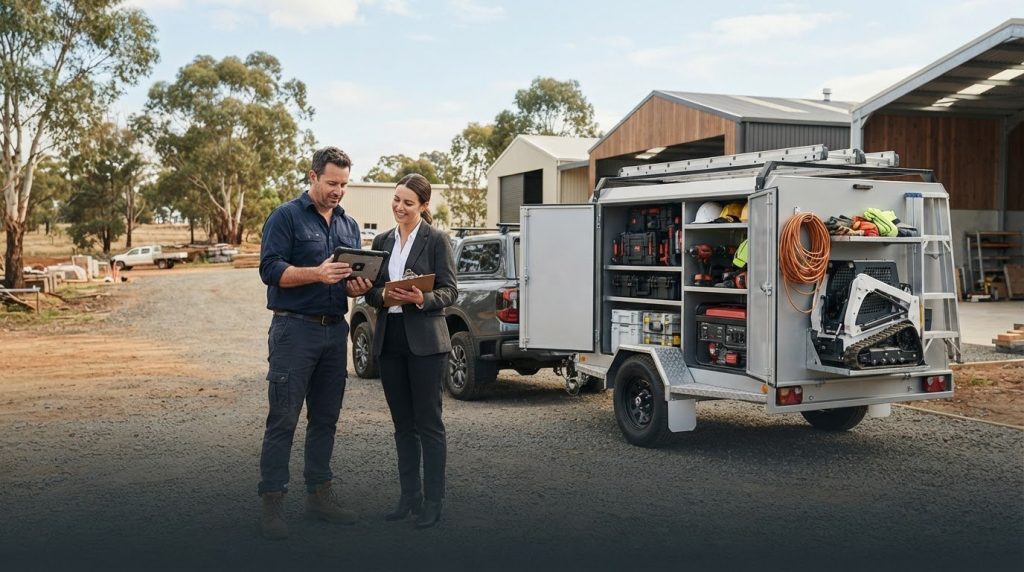
Trailer and Equipment Insurance: A Business Guide
What if your trailer is insured, but the tools it carries are treated differently? It’s understandable to wonder whether both belong under one policy or whether your business insurance reflects how each asset is used, stored and moved. Insurance for trailers and equipment needs a closer look than the policy label alone can provide.This guide explains the insurance categories that may be relevant, including business property, tools of trade and equipment, theft, commercial motor and marine transit cover. It also outlines the information to gather for a useful review, so you can describe your trailer, equipment and day-to-day work clearly.MyGen Insurance Brokers provides personalised business insurance reviews, drawing on 20+ years of industry experience and supporting clients through the policy period and claims process. All services are subject to the company’s terms and conditions, viewable on this site. Key Takeaways Insurance for trailers and equipment is a risk-review question, not one universal policy label. Consider the trailer, its contents and other business assets separately. Build a clearer picture of your risks by recording what you own, how each asset is used, and where it is stored or moved. Review relevant options, such as business property, tools and equipment, theft, commercial motor and marine transit cover, alongside the policy wording. MyGen can review your business risks and potential blind spots to help shape a considered insurance package. Table of Contents Insurance for trailers and equipment: understand the business risks How to review insurance for trailers and equipment before choosing cover Arrange a considered business insurance review for trailers and equipment Insurance for trailers and equipment: understand the business risks It can be difficult to know where a work trailer ends and its contents begin in an insurance review. The trailer, tools carried inside it, equipment used on site and goods being transported each raise different questions. A policy label alone does not explain how each item or business activity is treated.Think of insurance for trailers and equipment as a risk-review question, rather than one universal policy or guaranteed package. How cover applies depends on the policy wording, the property insured and the use described to the insurer. Understanding insurance fundamentals can help you make sense of how policies set out their terms.A video example of trailer insurance in practice: How do trailer cover and tools of trade fit into business insurance? Start by separating the assets and the risks. The trailer is distinct from the tools and equipment it carries. Goods being transported are another consideration, while the trailer’s business use may raise motor-related questions. Assets may also move between locations or be used at worksites, so describe those activities clearly as part of a review.Relevant categories to consider include General Property (Tools of Trade & Equipment), … [Read more...] about Trailer and Equipment Insurance: A Business Guide
Personal Liability of Company Directors in Australia: Is Your Family Home Protected?
If your company faced an unexpected ASIC investigation or a major ATO debt tomorrow, would the 'corporate veil' actually be enough to stop creditors from knocking on your family home’s front door? We understand that most directors step into their roles believing their personal assets are safely cordoned off from the business's risks. However, with the 2026 regulatory landscape becoming increasingly rigorous, that sense of security can often be misplaced. In this guide, we'll demystify the complexities of personal liability of company directors australia and show you how to build a robust firewall around what matters most. We’ll explore the latest 2026 compliance shifts, from Payday Super to industrial manslaughter laws, and provide a clear framework for choosing the right Management Liability or D&O insurance to ensure your peace of mind remains intact. Key Takeaways Debunk the myth of the 'impenetrable' corporate veil and understand how 2026 regulatory shifts can put your family home at risk if things go wrong. Understand the complexities of personal liability of company directors australia by learning to identify high-risk triggers like Fair Work investigations and ATO penalty notices. Distinguish between standalone D&O and comprehensive Management Liability cover to ensure your insurance matches your company's actual footprint rather than a generic template. Gain a clear framework for assessing your industry's specific risk profile, so you can move from a state of uncertainty to one of calm, managed security. Table of Contents The Reality of Personal Liability for Australian Small Business Directors D&O vs Management Liability: What Does Your Company Actually Need? A Risk Assessment Framework: Deciding if You Need Cover The Reality of Personal Liability for Australian Small Business Directors Many Australian directors believe that the 'Proprietary Limited' suffix on their company name acts as a bulletproof vest. While it offers some separation, the 2026 regulatory environment has made the 'corporate veil' increasingly transparent. Australia is widely regarded as having one of the most burdensome liability regimes in the world. This means the personal liability of company directors australia extends far beyond simple business debt. Directors can be held personally responsible for statutory breaches, unpaid taxes, and employee entitlements.To better understand how these risks manifest, watch this helpful video: Directors and Officers (D&O) insurance exists to protect the individual's personal assets. Unlike standard business insurance that covers the entity, D&O acts as a personal firewall for your family home and savings. Small companies often face higher risks because they lack the deep compliance resources of larger corporations, leaving no margin for error when navigating Australian corporate law. We often see directors who are technically brilliant at their trade but struggle with the sheer volume of paperwork … [Read more...] about Personal Liability of Company Directors in Australia: Is Your Family Home Protected?
What Does Management Liability Insurance Cover? The 2026 Australian Business Guide
What if a single administrative oversight or a disgruntled employee's claim could reach past your company bank account and put your family home at risk? You've worked hard to build your business, yet you might be left wondering, what does management liability insurance cover in such a volatile environment? With a 2026 survey of industry leaders showing a 74% increase in claim complexity, the risks are growing. It's natural to feel unease when you realise your personal assets might be on the line for decisions made in the boardroom.This guide provides the clarity you need. We'll look beneath the surface to show how this protection ring-fences your private wealth, clarifies the vital differences between D&O and professional indemnity, and helps you navigate ASIC and Fair Work requirements with precision. Key Takeaways Understand exactly what does management liability insurance cover by exploring its three core pillars, ensuring your personal assets are ring-fenced from corporate lawsuits. Learn to distinguish between professional indemnity and management liability so you can properly secure the individuals steering your business. Gain certainty that your business is prepared for regulatory scrutiny, including protection against fines from unintentional breaches of WHS or Fair Work regulations. Avoid the risks of one-size-fits-all automated quotes by opting for a tailored risk assessment that identifies specific exposures within your unique industry. Table of Contents Understanding the Core Pillars of Management Liability Coverage Real-World Scenarios: What Management Liability Covers in Practice Why a Consultative Broker is Essential for Management Protection Understanding the Core Pillars of Management Liability Coverage Many business owners mistakenly believe their general business cover protects their private life. While Professional Indemnity Insurance covers the professional advice you provide, it doesn't address the internal risks of running a company. Management liability is a multi-layered policy designed to protect the "people" managing the business, rather than just the business assets. It acts as the essential safeguard for directors against personal liability under the Corporations Act 2001. When asking what does management liability insurance cover, it's helpful to see it as a shield for your personal reputation and bank account.To better understand how these protections apply in a modern workplace, watch this helpful overview from Nasdaq: Directors and Officers (D&O) Liability: Protecting Your Personal Assets This pillar is the most vital for Australian SME leaders who want to sleep soundly. Directors and Officers (D&O) liability insurance is centred on protecting your personal wealth, including your family home, from legal actions brought by shareholders, creditors, or regulators. It addresses "wrongful acts" like a breach of duty, negligence, or misleading statements made in your capacity as a leader. Without this … [Read more...] about What Does Management Liability Insurance Cover? The 2026 Australian Business Guide

The Essential Business Insurance Renewal Checklist for 2026
Relying on a "tick and flick" approach to your business insurance is the fastest way to leave your hard-earned assets unprotected in 2026. We understand how frustrating it feels to be treated like just another number in an automated system, especially when you're facing rising premiums that don't seem to offer any extra value. Using a comprehensive business insurance renewal checklist 2026 ensures you don't fall victim to hidden exclusions in the fine print that could leave you stranded when you need support the most.We've developed this guide to help you reclaim control, close dangerous coverage gaps, and secure your company's future with total certainty. This methodical review covers your current risks, from the impact of inflation on property replacement to the evolving complexities of cyber threats. We'll help you move past the automated noise to build a policy that actually matches your reality. Key Takeaways Learn why automated "tick and flick" renewals fail to protect your assets in a shifting economy and how to avoid being treated like just another number in a system. Follow our comprehensive business insurance renewal checklist 2026 to conduct a thorough audit of your operations, ensuring your liability limits keep pace with your revenue growth. Understand how 2026 inflation and supply chain disruptions affect your asset valuations so you can close dangerous coverage gaps before they become costly liabilities. Discover the peace of mind that comes from a consultative "deep-dive" review, moving beyond generic quotes to find a policy tailored to your specific industry risks. Table of Contents The 2026 Risk Landscape: Why a 'Set and Forget' Renewal Fails Your Essential 2026 Business Insurance Renewal Checklist Beyond the Checklist: The Value of a Consultative Review The 2026 Risk Landscape: Why a 'Set and Forget' Renewal Fails The Australian market in 2026 doesn't reward complacency. If you've been tempted to just sign the renewal papers without a second look, you're essentially gambling with your company's future. Automated algorithms often miss the nuances of your specific trade, treating your livelihood as a data point rather than a complex operation. This is why a thorough business insurance renewal checklist 2026 is vital; it forces a move away from generic "tick and flick" processing toward a strategy that actually protects you.Inflation hasn't just affected your weekly groceries; it's fundamentally shifted the cost of rebuilding premises and replacing specialised equipment. If your asset valuations haven't been updated since last year, you're likely carrying a significant shortfall. We've seen supply chain disruptions push lead times and costs to record highs, meaning a standard Business Owner's Policy (BOP) might no longer provide the safety net you expect.To better understand how to prepare for your upcoming review, watch this helpful video: This year is the time to look beneath the surface. While a basic … [Read more...] about The Essential Business Insurance Renewal Checklist for 2026
Common Business Insurance Mistakes for Australian SMEs
Did you know that 75 per cent of Australian small businesses currently take an "ad hoc" approach to their risk management? It's a concerning reality, especially when you consider that a single uncovered event can lead to financial ruin. We understand the frustration of paying high premiums for policies filled with complex wording that leaves you feeling uncertain about your actual level of protection. It's tempting to treat insurance as a simple "tick and flick" exercise, but this mindset often leads to common mistakes in business insurance that only surface during a claim.We believe you deserve certainty. This guide will help you move from confusion to clarity by exploring the critical errors leaving local SMEs exposed. You'll discover how a methodical, consultative approach ensures your assets are truly protected, providing the long-term security your business needs to thrive. Key Takeaways Recognise why prioritising speed and the lowest premium creates a "tick and flick" culture that results in shallow, unsuitable protection. Learn how to avoid common mistakes in business insurance by moving past a "set and forget" mentality that leads to dangerous underinsurance. Understand how even a minor misclassification of your business activities can inadvertently void a claim and leave your assets exposed. Discover how a methodical, manual risk assessment identifies unique liabilities that generic automated quotes consistently miss. Table of Contents The Perils of the Tick and Flick Culture in Business Insurance Underinsurance and Misclassification: The Silent Business Killers Building a Robust Risk Strategy Through Consultation The Perils of the Tick and Flick Culture in Business Insurance Many Australian business owners feel the pressure of time and rising overheads. This often leads to a "set and forget" mentality where insurance is treated as a compliance chore rather than a protective strategy. The "tick and flick" mistake is the prioritisation of convenience over comprehensive risk disclosure. Avoiding common mistakes in business insurance begins with acknowledging that speed is the enemy of accuracy, especially when you rush through a digital form just to get a certificate of currency.Automated platforms are designed for the "average" business, but very few Australian SMEs actually fit that mould. These algorithms frequently fail to capture the unique nuances of diverse local industries, from specialised trades to boutique consultancies. Relying on a generic Business Owner's Policy (BOP) without a manual risk assessment is one of the most common mistakes in business insurance today. It’s about looking beneath the surface to ensure your specific risks aren't being ignored by a "one size fits all" computer program.To better understand how these errors can impact your bottom line, watch this helpful video: Why Cheap Premiums Often Lead to Expensive Claims We understand the frustration of seeing your business costs climb. However, choosing … [Read more...] about Common Business Insurance Mistakes for Australian SMEs
Essential Startup Insurance: 2026 Australian Guide
If a single administrative oversight or a sophisticated cyber breach occurred tomorrow, would your Australian startup survive the week? We understand that building a venture from the ground up is exhilarating, yet the weight of regulatory requirements and the need for essential insurance for startups Australia can feel overwhelming. It's common to feel uncertain about which coverage is actually necessary and which is merely a distraction. With the Australian Securities and Investments Commission recording 150 administrative enforcement outcomes in the year ending June 2026, the stakes for compliance have never been higher.This guide helps you identify the critical liabilities facing your business and shows you how to build a protective shield through methodical risk management. We will explore the local landscape in depth, providing a prioritised list of risks so you can protect your personal and business assets with absolute peace of mind. Key Takeaways Recognise hidden operational vulnerabilities, including key person dependency, that could destabilise your venture before it reaches maturity. Gain clarity on the digital and professional threats that require a tailored shield to protect your business assets from sudden, high-impact losses. Discover the methodical process for selecting essential insurance for startups in Australia by building a formal risk register to prioritise your specific needs. Move beyond a "set-and-forget" mentality by integrating risk management into your core strategy for lasting stability and certainty. Table of ContentsOperational and Strategic Vulnerabilities in the Australian Startup EcosystemNavigating Legal, Regulatory, and Digital Threats for New VenturesCrafting a Methodical Risk Mitigation and Insurance Strategy Operational and Strategic Vulnerabilities in the Australian Startup Ecosystem Launching a venture is a high-stakes endeavour where operational oversights can quickly undo years of hard work. While many founders focus on growth, we've observed that the most significant threats often stem from internal strategic gaps. Understanding the broader Australian insurance market provides a useful foundation, but startups require a more granular, methodical approach to identify their unique pressure points. We believe that looking beneath the surface of your daily operations is the only way to ensure long-term security.To better understand this concept, watch this helpful video: A major vulnerability we frequently encounter is Key Person risk. If your startup relies entirely on one developer's proprietary code or a single founder's network without a formal contingency plan, you're essentially one accident away from a total shutdown. This operational fragility makes securing essential insurance for startups australia a matter of survival. It's about creating a safety net that allows you to innovate without the constant fear of a single point of failure.The Risk of Underestimating Product-Market Fit We often … [Read more...] about Essential Startup Insurance: 2026 Australian Guide
Management Liability Insurance Guide for Directors
Imagine receiving a formal notice from Fair Work or the ATO that doesn't just name your company, but lists you personally as a respondent. For many Australian directors, the realisation that their family home and personal savings could be on the line during a business dispute is a source of constant, quiet anxiety. You've spent years building your legacy, and it's only natural to feel protective of the assets you've worked so hard to accumulate. We understand that the distinction between your professional duties and your personal life can feel dangerously thin when regulatory pressure mounts, which is why it's vital to know what does management liability insurance cover before a crisis hits. This guide provides a clear roadmap for protecting your personal wealth, ring-fencing your private life from the unique risks found in our local regulatory environment. We'll break down the specific protections this cover provides and explain why a tailored policy offers far more security than a generic, automated quote. By the end of this article, you'll have the certainty you need to lead your business with confidence, knowing your personal future is secure. Key Takeaways Learn how to ring-fence your personal assets, such as your family home and savings, from the financial fallout of business-related lawsuits and regulatory investigations. Gain a comprehensive understanding of exactly what does management liability insurance cover, including the four distinct pillars of protection required to navigate the Australian corporate landscape. Understand why high-quality legal defence is your first line of protection and how a robust policy manages these rapidly escalating professional costs before they impact your bottom line. Discover the hidden dangers of relying on automated, generic insurance quotes that often overlook the nuanced risks specific to your industry and operational structure. Learn how to move from a state of regulatory anxiety to professional certainty by securing a policy that is meticulously tailored to your unique leadership role and responsibilities. Table of Contents Understanding Management Liability: The Shield for Your Personal Assets The Four Pillars: Exactly What Does Management Liability Insurance Cover? Why Small Businesses Can’t Rely on "Tick and Flick" Insurance Quotes Understanding Management Liability: The Shield for Your Personal Assets When business owners ask what does management liability insurance cover, the simplest answer is that it acts as a personal shield for your private assets. While most business insurance policies are designed to protect the entity's physical property or its public reputation, management liability is fundamentally different. It covers the costs of defending and settling claims that arise from "wrongful acts" committed while managing a company. This means that if a decision you make in the boardroom leads to a legal challenge, the policy steps in to manage the financial … [Read more...] about Management Liability Insurance Guide for Directors