
What if the “instant” online quote you just purchased is actually the biggest risk your company faces? We understand the pressure to tick a box and get back to work, but the reality is that generic business insurance often leaves dangerous gaps in your protection. It’s frustrating to spend hours trying to decipher terms like indemnity and liability, only to wonder if your policy will actually hold up when a claim is filed.
You deserve the certainty that comes from a personalised insurance shield rather than a one-size-fits-all document. This guide explores the 2026 Australian landscape, including new privacy obligations and payday super changes, to help you move beyond automated quotes. We’ll show you how to simplify your portfolio and build a relationship with a seasoned expert who prioritises your long-term security over a quick, superficial transaction.
Key Takeaways
- Move beyond the “set and forget” mindset to build a dynamic business insurance strategy that protects your livelihood against evolving 2026 risks.
- Distinguish between essential covers like Public Liability and Professional Indemnity to ensure your professional advice and physical assets are fully shielded.
- Uncover the “Broker Advantage” by learning how a human expert identifies hidden vulnerabilities that generic, automated online quotes frequently overlook.
- Gain the clarity needed to simplify your insurance portfolio, turning complex industry jargon into a professional relationship built on trust and thoroughness.
What is Business Insurance and Why Does Your Australian Firm Need It?
At its heart, business insurance is more than just a monthly expense; it’s a protective suite of covers designed to safeguard your physical assets, your team, and your legal viability. It is a specialised branch of General insurance that focuses on the unique risks inherent in the commercial world. Rather than a static document, we view it as a dynamic risk management strategy. Our primary objective is to ensure that a single catastrophic event, such as a major property fire or a significant legal claim, doesn’t result in the permanent closure of your business.
To better understand how these different covers work together, watch this helpful overview:
Australian SMEs are especially vulnerable right now. Selecting the right business insurance requires looking beneath the surface of your daily operations. Under-insurance is a growing concern as businesses try to manage rising costs by trimming premiums. However, this often leaves your livelihood exposed at the very moment you can least afford a financial shock. We believe in building a shield that is deep enough to handle reality, ensuring your cover grows alongside your revenue and staff numbers.
The “Tick and Flick” Trap: Why Cheap Online Quotes Often Fail
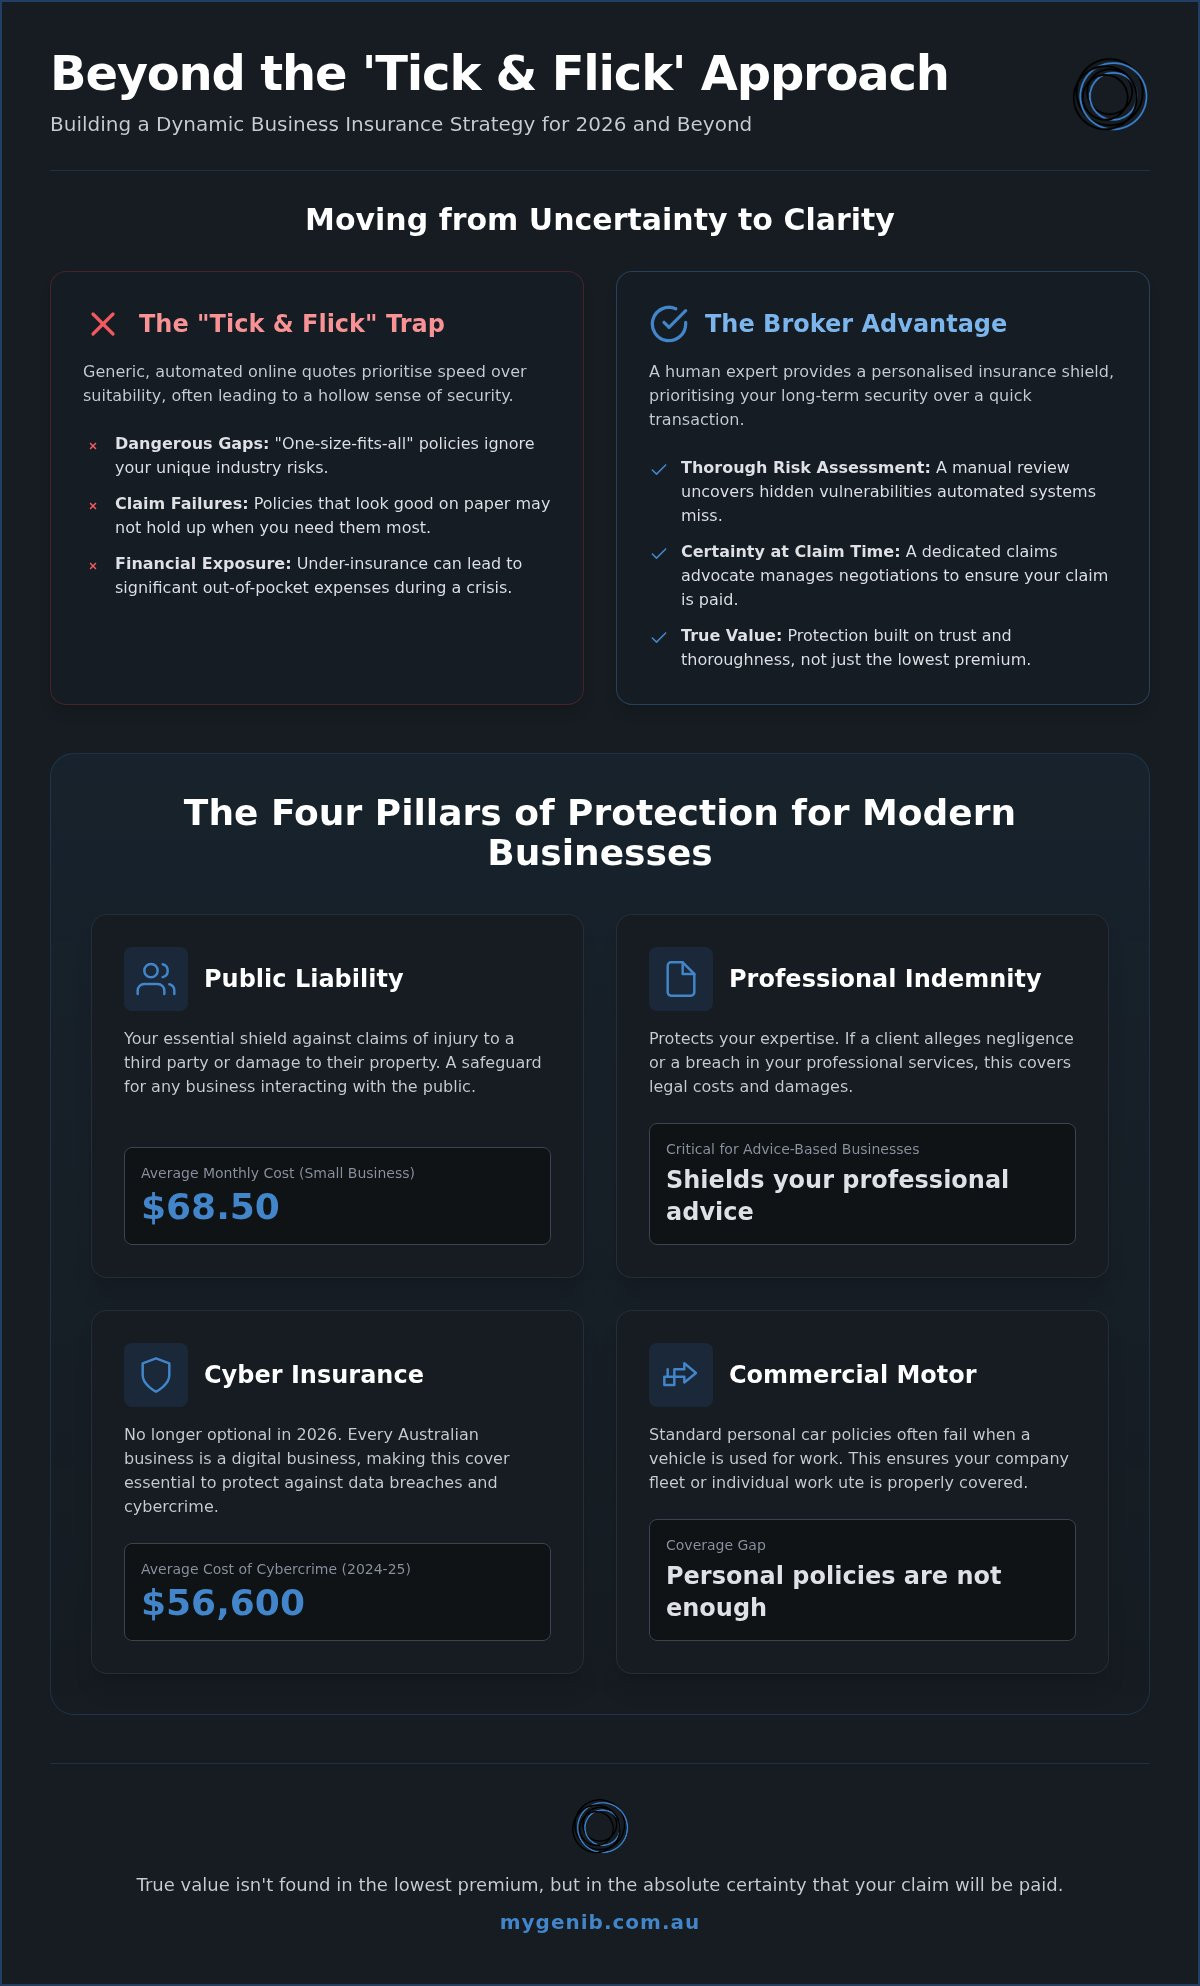
Many automated platforms encourage a “tick and flick” approach that prioritises speed over suitability. These generic systems often ignore the subtle nuances of your specific industry, leading to “one-size-fits-all” policies that look good on paper but fail during a claim. If your policy doesn’t account for your unique operational risks, you may find yourself facing significant out-of-pocket expenses. A thorough, manual risk assessment is the only way to avoid these dangerous gaps in your protection.
The Four Pillars of Protection for Modern Businesses
Building a resilient company requires a structured approach to risk. While there are many Types of business insurance available, four specific pillars form the foundation of a modern business insurance strategy. These aren’t just administrative hurdles; they’re the difference between a minor setback and a total loss.
- Public Liability: Your shield against third-party injury or property damage claims. With the average small business paying around $68.50 per month for public liability, it’s an essential safeguard for anyone interacting with the public.
- Professional Indemnity: This protects your expertise and advice. If a client alleges negligence in your professional services, PI covers the legal costs and damages.
- Cyber Insurance: Every Australian firm is a digital firm in 2026. With the average cybercrime incident costing small businesses $56,600 in the 2024-25 financial year, this cover is no longer optional.
- Commercial Motor: Standard personal car policies often fail when a vehicle is used for work. This pillar ensures your company fleet or individual work ute is properly covered for commercial use.
Tailoring Cover to Your Specific Industry Risk Profile
Your daily risks look very different if you’re a plumber compared to a marketing consultant. For advice-based businesses, professional indemnity insurance serves as a critical layer that a tradesperson might prioritise less than tool cover. We help you look beneath the surface to identify which pillars of business insurance need the most reinforcement. If you’re unsure where your gaps lie, you can reach out for a thorough assessment of your current risk profile.
The Broker Advantage: Moving from Uncertainty to Clarity
We often see business owners tempted by the speed of comparison sites. While saving a few dollars on business insurance feels like a win initially, it often leads to a hollow sense of security that vanishes the moment a crisis hits. Our consultative process is designed to uncover the specific risks you haven’t yet considered, such as evolving regulatory requirements or specific contractual liabilities. As participants in the industry governed by the Insurance Council of Australia, we know that true value isn’t found in the lowest premium, but in the absolute certainty that your claim will be paid.
Having a seasoned hand in your corner matters most when things go wrong. A broker acts as your dedicated claims advocate, managing the technical negotiations with insurers so you don’t have to face a faceless entity alone. At MyGen, our “deep-dive” methodology is the direct antidote to the corporate detachment found in automated platforms. We take the time to look beneath the surface of your operations, ensuring your business insurance remains a robust shield rather than a forgotten piece of paperwork.
Your 2026 Insurance Checklist: Getting Started the Right Way
Taking the first step toward clarity doesn’t have to be overwhelming. We suggest starting with these two fundamental actions to protect your livelihood:
- Step 1: Document your assets. List your physical equipment alongside your professional exposures to create a clear map of what needs protection.
- Step 2: Prioritise conversation over clicks. Commit to a consultative review with an expert who asks the right questions, rather than settling for a generic two-minute quote.
For a more detailed look at effective risk management, we encourage you to view the complete guide to business insurance.
Securing Your Legacy in a Changing Landscape
Protecting your Australian business in 2026 requires looking beyond the superficial “tick and flick” approach. You’ve seen how the four pillars provide a foundation for security. You also understand why a human-led risk assessment beats an automated quote every time. We believe that true peace of mind comes from knowing your livelihood is shielded by accuracy and diligence rather than a generic document. With over 20 years of industry experience, we are here to do the heavy lifting for you, providing specialist claims advocacy and a deeply personal touch. It’s time to move from uncertainty to clarity with a strategy that evolves alongside your success. You can speak with an expert broker at MyGen for a personalised risk review to ensure your business insurance is truly fit for purpose. We’re ready to help you build a secure future with confidence.
Frequently Asked Questions
Is business insurance a legal requirement in Australia?
Certain forms of cover are compulsory under Australian law. Workers’ compensation insurance is mandatory if you employ staff, while Compulsory Third Party (CTP) is required for business vehicles. Beyond these, many professional bodies or commercial contracts require specific levels of public liability. We guide you through these legal obligations to ensure your firm remains compliant and fully protected from the start.
How much does business insurance cost for a sole trader in 2026?
The cost for a sole trader depends heavily on your specific trade and the level of exposure you face daily. A consultant working from home faces different risks compared to a mobile tradesperson. We reject the “one-size-fits-all” pricing model of automated sites. Instead, we perform a thorough investigation to find a premium that reflects your actual needs and professional risks.
What is the difference between Public Liability and Professional Indemnity?
Public Liability addresses physical accidents, such as a visitor being injured at your workspace or property being damaged. Professional Indemnity is different because it covers the consequences of your advice or professional errors. If a client suffers a financial loss because of a mistake in your service, PI is the shield you need. Both are vital for a complete risk management strategy.
Can I bundle all my business covers into one policy?
We often recommend bundling your business insurance requirements into a single, cohesive portfolio. This simplified approach reduces your paperwork and minimises the risk of having gaps in your protection. By coordinating your liability, cyber, and motor covers, we ensure your entire operation is managed as one logical unit. It’s an efficient way to turn a complex task into a managed outcome.