
What if the automated calculator you relied on to protect your livelihood is actually your biggest financial risk? It’s exhausting trying to keep up with rising replacement costs while wondering if your digital assets or that specialised portable gear are actually covered. You’ve likely felt the frustration of clicking through a generic quote only to realise it doesn’t understand the nuances of your specific industry.
We’re here to change that by showing you how to secure business contents insurance that reflects the true value of your assets in 2026. This guide explores the essential steps to accurate valuation, the shift towards tailored risk assessments, and how a dedicated broker ensures no physical or digital asset is left vulnerable. You’ll gain the clarity needed to move from uncertainty to complete confidence in your coverage, knowing your business is protected by more than just a best guess.
Key Takeaways
- Understand why a “one-size-fits-all” policy often fails Australian SMEs and how to define coverage that specifically protects your tools, stock, and fit-out.
- Learn how to calculate replacement value rather than book value to ensure your business contents insurance accurately reflects 2026 market prices.
- Discover the benefits of a consultative brokerage approach that looks beneath the surface to identify overlaps with other policies like professional indemnity insurance.
- Master a methodical inventory process that captures every physical asset, including specialised equipment and signage, to eliminate the risk of underinsurance.
Understanding Business Contents Insurance in the 2026 Australian Landscape
Think of your business contents as the tangible and intangible engine that keeps your operations moving. Whether it’s the specialised tools in your workshop, the retail stock on your shelves, or the bespoke fit-out of your office, these assets represent your hard work and capital. Standard business contents insurance is designed to protect these items from loss, theft, or damage; however, many Australian SMEs find that generic, off-the-shelf policies leave them exposed when a claim actually occurs.
To get the most out of your coverage, you need total risk visibility rather than just a tick-box exercise. This involves Understanding Business Owner’s Policies and how they bundle different protections to suit your specific industry. Relying on a “one-size-fits-all” approach often fails when unique operational risks or high-value equipment aren’t properly accounted for in the fine print.
To better understand this concept, watch this helpful video:
Physical vs Digital Assets: What Counts as Contents?
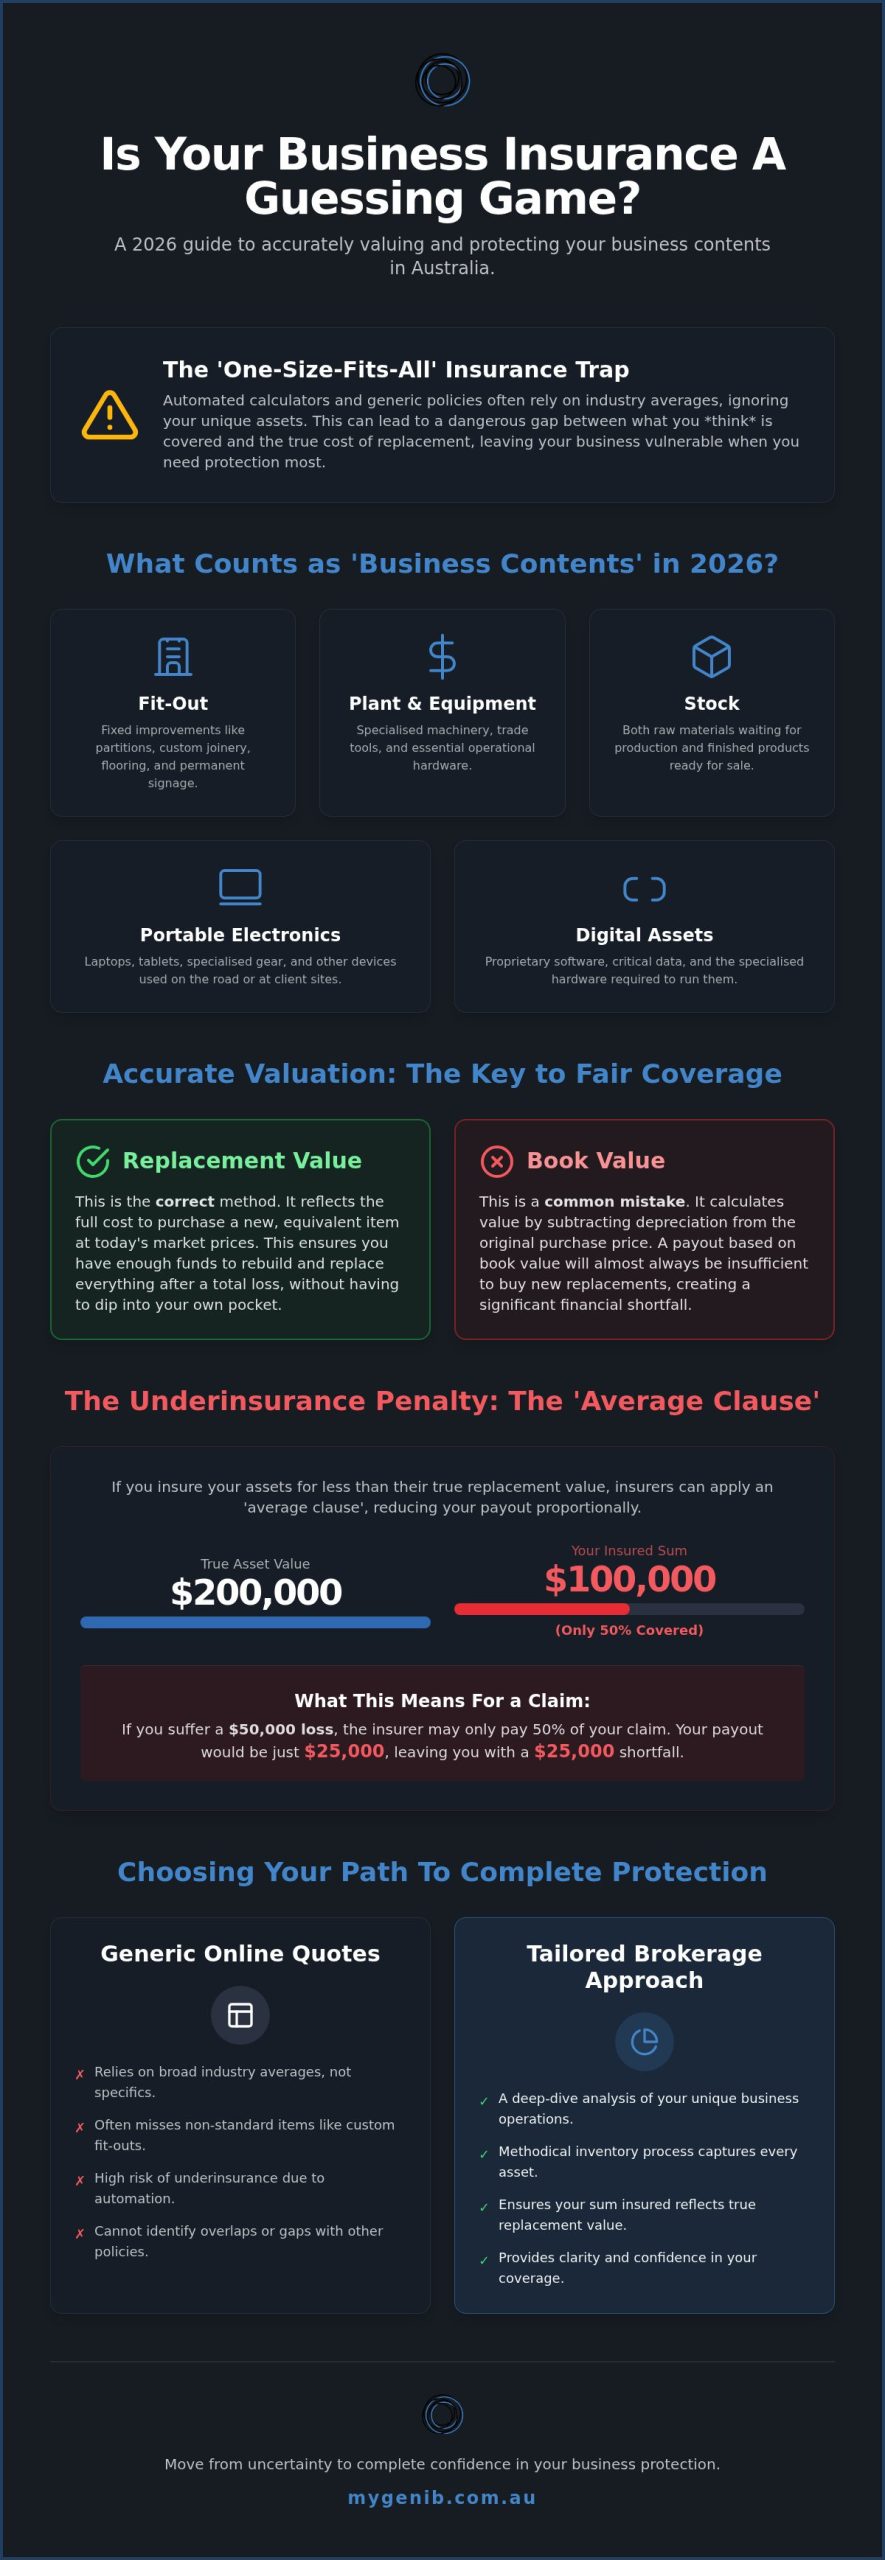
In 2026, the definition of contents has moved beyond desks and chairs. We look beneath the surface to identify everything that keeps your doors open. This includes:
- Fit-out: Fixed improvements like partitions, flooring, and signage.
- Plant and equipment: Machinery and tools specific to your trade.
- Stock: Both raw materials and finished products ready for sale.
- Portable electronic devices: Gear used on the road or at client sites.
The modern shift also includes digital assets and specialised software hardware. If your operations hinge on proprietary tech, ensuring it’s covered under your business contents insurance is vital. For a broader look at your options, see The Complete Guide to Business Insurance in Australia.
How to Calculate the Real Value of Your Business Assets
Calculating the value of your assets requires a methodical approach that looks beneath the surface. It’s not just about the big-ticket items; you need a comprehensive inventory that includes often-overlooked components like exterior signage, custom shop fittings, and every piece of stock. When you review Australian business insurance types, you’ll see that asset protection is a cornerstone of operational stability.
Once your list is complete, assess the replacement value rather than the book value. Book value accounts for depreciation, but in the event of a total loss, you need to buy everything new at 2026 market prices. You should also factor in the time it takes to source specialised equipment. If replacing a core asset takes months, your business contents insurance should ideally align with your wider risk strategy to account for these delays.
The Dangers of Underinsurance and Automated Estimates
Many business owners fall into the “underinsurance trap” by using automated calculators that rely on industry averages. These tools often ignore your specific risk profile, leading to a dangerous gap in coverage. If you under-declare your value, most Australian policies trigger an “average clause,” which allows the insurer to reduce your payout proportionally to the underinsurance. Replacement value is the current cost to buy the item new today, not what you paid five years ago. Taking the time to organise a personalised review ensures your sum insured is accurate and your livelihood is protected.
Why a Tailored Brokerage Approach Beats Generic Online Quotes
While automated “instant quote” platforms promise speed, they often act as skimmers, glossing over the intricate details that define your specific industry risks. We believe in a deep-diver methodology. A professional broker doesn’t just process a transaction; they act as a protective mentor who investigates the nuances of your operations to ensure your business contents insurance is truly fit for purpose. This consultative review is essential for identifying subtle gaps where your physical assets might overlap with your professional indemnity insurance, preventing you from paying for redundant cover or falling through the cracks of a generic policy.
When a claim occurs, the value of this relationship becomes clear. You aren’t just a policy number in a queue; you have a seasoned expert navigating the complexities on your behalf. This partnership ensures that your claims are managed with the same diligence used to craft your policy, moving you from a state of stress to one of certain relief.
Integrating Contents Cover into a Comprehensive Strategy
A truly secure business doesn’t view insurance in silos. We help you understand how your contents protection works alongside other essential policies, such as commercial vehicle insurance, to ensure your tools and equipment are covered while in transit. As your business grows and you acquire new technology or stock, it is vital to review the value of your assets regularly. This methodical approach keeps your coverage aligned with real-world replacement costs, providing the peace of mind you deserve. If you’re ready to move beyond generic estimates, speak with a MyGen broker for a personalised risk assessment today.
Securing Your Business Future with Precision
Protecting your livelihood shouldn’t be left to the guesswork of an algorithm. By moving beyond generic calculators and embracing a methodical valuation of your physical and digital assets, you ensure your business contents insurance is built on reality rather than estimates. We’ve seen how 2026 replacement costs and industry-specific risks can create dangerous gaps in off-the-shelf policies; this is why a deep-dive assessment is your strongest safeguard against underinsurance.
With over 20 years of industry expertise, we focus on consultative risk management that puts your peace of mind first. You deserve a dedicated Australian broker who acts as a protective mentor, looking beneath the surface to secure every detail of your operations. Take the first step toward certainty and Request a Personalised Business Insurance Review today. We’re ready to help you build a more secure future.
Frequently Asked Questions
Is my business stock covered at cost price or retail price?
Most policies cover stock at its replacement cost, which is the price you paid to acquire or manufacture the items. While you might expect retail price coverage, insurance is designed to restore your business to its previous position without including lost profit margins. For protection against lost profits on unsold goods, you should consider business interruption cover alongside your business contents insurance.
Does business contents insurance cover my laptop if I take it home or to a cafe?
Coverage for mobile devices outside your primary office depends on whether you’ve included a specialised “portable equipment” or “general property” extension. Standard contents cover is often restricted to the physical business premises listed on your policy. If you frequently work from cafes or client sites, we can help you specify these items for national coverage so they remain protected while in transit.
How often should I update my asset inventory for insurance purposes?
You should review your asset inventory at least once a year or whenever you make a significant purchase that changes your risk profile. In the current high inflation environment, waiting for your annual renewal might leave you exposed to a valuation gap. We recommend a methodical update every time you upgrade technology or fit out new sections of your workspace to maintain accuracy.
What happens if I accidentally underestimate the value of my contents?
Underestimating your value can trigger an “average clause,” which results in a significantly reduced claim payout from the insurer. If you insure for only 50% of the actual replacement value, the insurer may only pay 50% of any claim you make, even for minor losses. This is why we avoid automated quotes and perform deep-dive assessments to ensure your business contents insurance reflects real-world costs.