
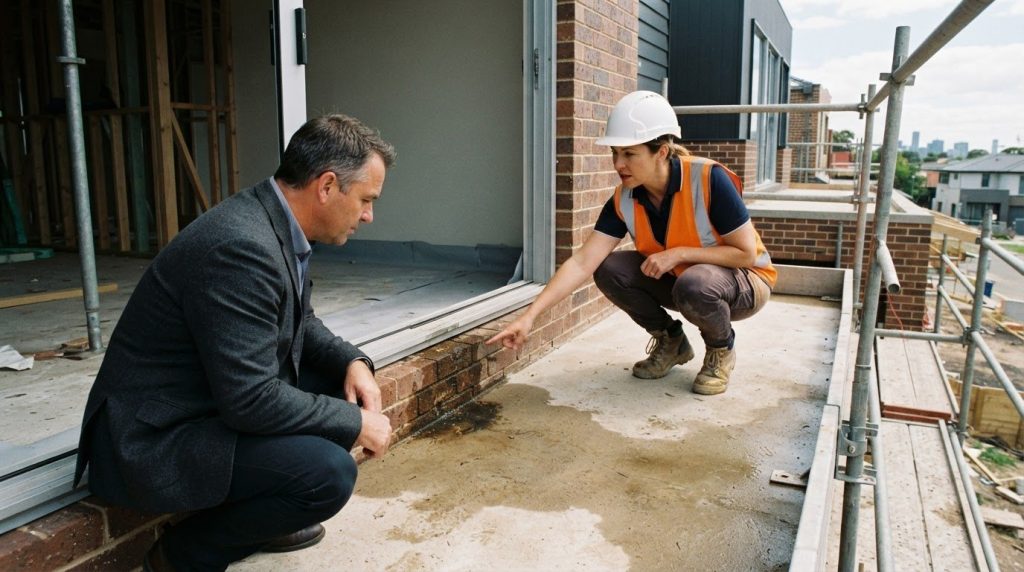
A design decision can create liability even when the work is unpaid. Professional indemnity for architects is compulsory in some Australian jurisdictions: in South Australia, practising architects must hold their own policy or be named on their employer’s, with at least A$1 million cover for any one claim and in the aggregate, plus defence costs in addition to the limit.It’s understandable to want a clear answer before arranging cover, especially if you work for an employer, take on private projects or provide advice as a building designer. Professional indemnity for architects should reflect the services you actually provide and the risks attached to them.This article explains what professional indemnity insurance may cover, when an employer’s policy may apply and why professional duties can arise even when no fee is charged. It also outlines the business and project information to prepare for a quote, so you can start the conversation with a clear picture of your work. Key Takeaways Read your employer’s policy carefully and distinguish work done in your role from private or freelance projects. Understand how design errors, regulatory issues or incomplete documents can lead to allegations of financial loss. Remember that professional duties can apply to unpaid architectural work, so pro bono services still need careful risk consideration. Prepare a clear summary of your services, projects and business changes to help shape a relevant insurance quote. Table of Contents What if my employer’s professional indemnity insurance covers me? Professional indemnity insurance for architects and building designers Civil liability for professional design and advisory services MyGen Insurance Brokers: Business Insurance What if my employer’s professional indemnity insurance covers me? An employer’s policy protects you only within its insured scope, role and named insureds. South Australian architects must hold their own professional indemnity policy or be named on their employer’s. That policy excludes private or freelance architectural services outside the job. In Victoria, each architect remains responsible for compliant cover, including when employed.Professional indemnity insurance can respond when a client alleges that an architect’s, engineer’s or designer’s advice or service caused financial loss. Depending on the policy, it may help meet legal defence costs and compensation. A design error or incomplete drawing could lead to a claim. Public liability is different: it generally concerns third-party injury or property damage, not the quality of professional advice.Who needs cover depends on the work, jurisdiction and contracts. Architects may have registration requirements, while a client may require a building designer or engineer to hold cover before engagement. In South Australia, the duty of care also applies to unpaid architectural work, so pro bono projects still carry professional exposure. List every service you provide, including side … [Read more...] about Professional indemnity cover for architects and building designers
Intellectual property infringement insurance and what it covers
A copyright claim can reach a business even if the infringement was inadvertent. Intellectual property infringement insurance may cover loss, damage or liability arising from alleged inadvertent infringement of copyright, patents or other intellectual property rights connected with professional services, subject to the policy’s terms and limits.It is understandable to expect a policy to respond when a claim arrives, but the wording matters. The cover must apply to the type of infringement alleged, relate to the insured’s professional business and be current when the claim is made. This article explains how Professional Indemnity Insurance may address infringement claims, what cover can include and which conditions affect whether a policy responds. It also looks at the consequences of using protected material without permission, helping you understand the risks before a dispute escalates. Key Takeaways Using an image in client work without permission or a licence can expose a business to a copyright claim, even when the mistake was inadvertent. Consider how a claim could affect legal costs, finances and business reputation when assessing the level of cover needed. Review whether professional indemnity cover addresses alleged inadvertent infringement linked to your services, and understand its limits and settlement conditions. MyGen Insurance Brokers can help businesses consider Professional Indemnity Insurance as part of a tailored approach to business risk. Table of Contents Copyright infringement claims involving images Legal, financial and reputational consequences Copyright infringement cover under professional indemnity insurance MyGen Insurance Brokers: Business Insurance Copyright infringement claims involving images A graphic designer may face a damages claim after using a copyrighted image without permission or a licence. An advertising agency may face similar action if a client campaign includes protected content. While dedicated wall art for workplaces can be sourced safely through specialists like Panther Print, incorporating digital imagery into client work carries strict licensing responsibilities. The claim may concern the image itself, even if the mistake was not deliberate. Intellectual property infringement insurance can help cover legal costs when defending infringement claims against a business, its customers or licensees.IP infringement insurance may cover both defending allegations and pursuing alleged infringers. “IP defence insurance” usually refers to cover for defending claims, but policy labels and scope vary. Policies may cover copyright, trademark and patent disputes. Prior to rolling out new branding, conducting clearance searches with intellectual property specialists such as Henry Goh & Co can help businesses mitigate the risk of conflicting marks. Whether design disputes are covered depends on the wording and the types of infringement the insurer accepts.Cover may include legal fees to defend a claim, … [Read more...] about Intellectual property infringement insurance and what it covers

What is Public Liability Insurance? A Clear Guide for Australian Businesses
A local business owner recently discovered that a single moment of inattention on a job site could lead to a legal claim larger than their entire annual turnover. For many Australian entrepreneurs, the anxiety isn't just about the accident itself; it's the crushing weight of legal jargon and the worry that a generic policy won't actually stand up when it's needed most. You likely feel that protecting your livelihood should be straightforward, yet when you're trying to figure out what is public liability insurance, you're often met with automated forms that don't understand the specific risks of your trade. We believe you deserve better than a "best guess" approach to your security. This guide functions as a clear roadmap to help you move from a state of uncertainty to one of complete confidence by showing you how to align your cover with your actual daily operations. We'll explore the critical differences between public and product liability, look at why the Insurance Council of Australia is currently pushing for urgent civil liability reforms, and help you determine the level of protection that truly fits your business size and sector. Our goal is to ensure you feel protected by a policy that is as diligent and thorough as you are. Key Takeaways Learn exactly what is public liability insurance and how it acts as a vital financial buffer against the unpredictable costs of third-party injury or property damage claims. Discover why a robust policy covers far more than just settlements, providing the essential legal and investigative support needed to defend your business's reputation and livelihood. Understand the concept of "duty of care" in an Australian context to better identify the specific operational risks that could lead to significant financial exposure. See why standard cover limits shouldn't be a "best guess" and how a tailored approach helps you determine a level of protection that reflects your daily reality. Learn to look beneath the surface of generic policies to ensure your cover is organised around your specific trade rather than a one-size-fits-all template. Table of Contents Understanding Public Liability Insurance: Your Business Safety Net What Does Public Liability Cover (and What Does It Ignore)? Organising the Right Cover: Moving Beyond Automated Quotes Understanding Public Liability Insurance: Your Business Safety Net At its heart, Public liability is about protection against the unexpected. If a customer trips over a loose cable in your shop or a delivery driver is injured by a falling pallet at your warehouse, you're legally responsible for the fallout. This insurance covers the financial loss resulting from your legal liability for third-party injury or property damage. It's the difference between a minor setback and a business-ending financial crisis. In Australia, every business operator has a "Duty of Care" to ensure their actions don't cause harm to others. When this duty is breached through negligence, it … [Read more...] about What is Public Liability Insurance? A Clear Guide for Australian Businesses