
What if an employee used their authorised access to take money or property, and your policy didn’t respond? Fidelity insurance for employee theft may help protect a business against certain losses caused by employee dishonesty, but cover depends on the policy wording and the circumstances of the loss. Some policies treat third-party fraud and other criminal acts separately.Before relying on insurance as a financial backstop, it helps to understand what may be covered and what conditions apply. This guide explains how fidelity cover can differ from other business insurance and what exclusions, evidence requirements and claim conditions to check. It also sets out practical steps for comparing policy wording with your business’s risks. Key Takeaways Fidelity insurance for employee theft may respond to specified losses, but the policy wording determines the scope of cover. Map staff access to money, stock and approvals to identify where your business could face employee-dishonesty risks. Check who counts as an insured person, as well as limits, excesses, exclusions and notification requirements. If theft is suspected, preserve records, document what is known and follow the policy’s notification instructions while seeking appropriate advice. Table of Contents What is fidelity insurance for employee theft, and what might it cover? How to assess fidelity insurance for employee theft before choosing cover Handling Employee Theft: When to Call Your Broker What is fidelity insurance for employee theft, and what might it cover? Suspected employee theft can create financial uncertainty as well as a difficult workplace situation. Understanding what your policy may respond to is a useful first step. Fidelity insurance for employee theft may cover specified losses caused by employee dishonesty, but the policy wording and circumstances determine whether a particular loss is covered.Depending on the wording, cover may include theft of business money, securities or other property by an employee. It is not a blanket guarantee against every dishonest act, and it may not extend to contractors or outside parties unless the policy says so. For a general overview of the concept, see Fidelity bond.This video provides another overview of fidelity guarantee insurance: Is fidelity insurance the same as employee dishonesty or crime insurance? Insurers may use terms such as “fidelity”, “employee dishonesty” or “crime” differently. Fidelity cover generally focuses on losses caused by dishonest employees, while a broader crime policy may include other types of criminal activity. The product name alone does not confirm what is insured.Fidelity insurance covers specified losses from employee dishonesty, with protection determined by the policy wording and the circumstances of the loss. Check how the policy defines insured people, theft and fraud, and whether it treats cash, electronic funds and physical property differently.Do not assume a general business insurance … [Read more...] about Fidelity Insurance: Australian Employee Theft Guide
Machinery Breakdown Cover: Australian Business Guide 2026
Your standard commercial property policy will not pay a single cent when a vital motor suddenly burns out from within. It's easy to assume that standard business packs protect against every operational halt, but fire and perils policies routinely exclude internal mechanical or electrical faults. That's why securing genuine machinery breakdown insurance cover is vital to keep unforeseen equipment failure from derailing your operations.We understand the acute stress of watching revenue evaporate while machinery sits idle, particularly when automated quote forms overlook the distinct nuances of your plant. In this guide, you'll discover how specialised breakdown cover steps in when internal components fail, how to link sums insured directly to business interruption protection, and how to secure tailored safeguards without relying on generic algorithms. Key Takeaways Understand why standard commercial property policies exclude internal motor burnout and mechanical faults, leaving critical plant unprotected. Discover how specialised machinery breakdown insurance cover protects your balance sheet against sudden electrical, mechanical, and pressure vessel failures. Learn how connecting business interruption and deterioration of stock extensions safeguards revenue and perishable assets during prolonged equipment downtime. See how consultative broker risk assessments expose single points of failure that automated, generic quote forms regularly overlook. Table of Contents Demystifying Machinery Breakdown Insurance Cover: Internal Failure vs Property Perils Evaluating Essential Policy Extensions: Business Interruption and Deterioration of Stock Securing Tailored Machinery Cover: Why Consultative Brokerage Outperforms Automated Quotes Demystifying Machinery Breakdown Insurance Cover: Internal Failure vs Property Perils Many business owners discover the hard boundary of their commercial property policy only after a critical machine grinds to a halt. Standard property insurance is built exclusively for external perils; it responds to fire, storm damage, impact, or theft. In contrast, specialised machinery breakdown insurance cover exists to protect against sudden, internal physical loss. This includes mechanical derangement, electrical arcing, motor burnout, or pressure vessel explosion originating from within the unit.Understanding this distinction has guided industrial underwriting since the early history of machinery insurance, when boiler failures exposed massive gaps in conventional property forms. However, protection is not boundless. Every Australian commercial underwriter strictly excludes routine wear and tear, gradual corrosion, and lack of maintenance. Cover applies to sudden, unforeseen events rather than predictable mechanical aging.To see how underwriters evaluate these internal mechanical risks, watch this concise industry breakdown: Key Protected Assets: From Cold Storage Compressors to CNC Machinery Tailored machinery breakdown … [Read more...] about Machinery Breakdown Cover: Australian Business Guide 2026
Small Business Continuity Planning: Practical 2026 Guide
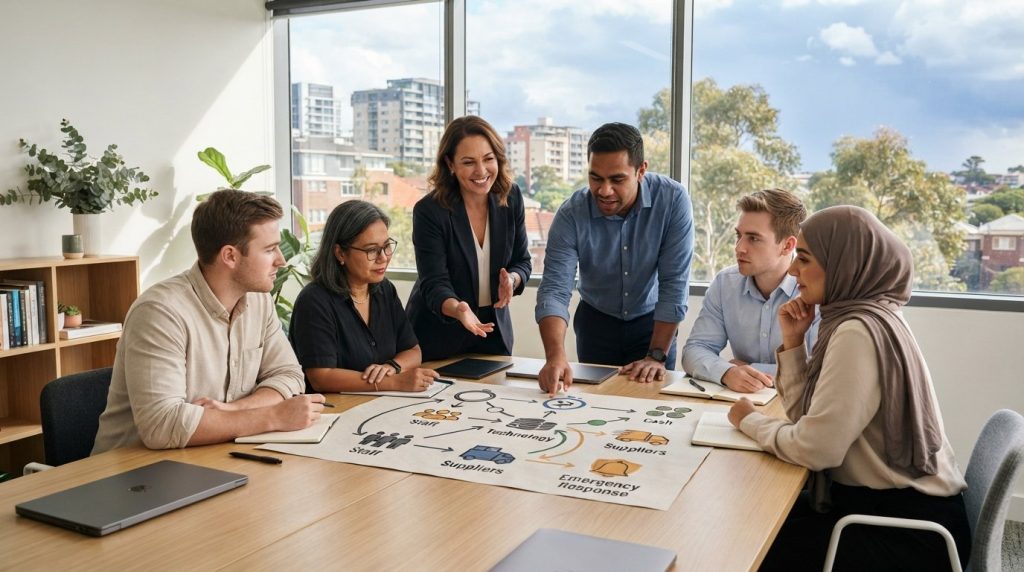
True operational resilience is an active habit, not a hundred-page binder gathering dust on an office shelf. For most founders, practical business continuity planning for small business operations often feels buried beneath dense corporate jargon and unrealistic disaster recovery templates. We recognise the pressure: you don't have weeks to spend parsing theoretical paperwork, nor spare capital to pour into cumbersome emergency manuals.You can safeguard your livelihood without drowning in administrative complexity. In this practical guide, you will discover how to build a sensible continuity plan that protects your staff, daily trading, and cash flow from sudden disruptions. We break down your core operational risks, set clear recovery priorities, and outline a straightforward roadmap to keep your enterprise trading when unexpected shocks strike. Key Takeaways Effective business continuity planning for small business replaces unwieldy corporate manuals with agile, practical playbooks designed for immediate operational action. A focused Business Impact Analysis clarifies your most vital dependencies, helping you allocate limited recovery resources directly where they protect revenue. Routine tabletop simulation exercises prepare your team for realistic disruptions, including cyber incidents, supply chain failures, and sudden infrastructure outages. Sustainable operational resilience requires pairing practical internal response protocols with tailored business insurance to defend cash flow during prolonged trading halts. Table of Contents What Is Business Continuity Planning for Small Business? How to Build a Small Business Continuity Plan in 5 Steps How to Test, Maintain, and Fund Your Continuity Strategy What Is Business Continuity Planning for Small Business? At its heart, business continuity planning for small business is about keeping your essential operations alive when unforeseen crises occur. Many enterprise-level guides push bloated manuals and expensive software platforms that small teams simply don't need. Real resilience isn't found in a complex software suite; it lives in a lean, actionable roadmap that your staff can execute under pressure without hesitation.To grasp how these core concepts come together practically, watch this concise overview of continuity principles: Rather than adopting dense overseas frameworks, Australian organisations typically follow the standard emergency management structure. Citing a recognized business continuity planning framework, this approach divides resilience into four straightforward pillars: Prevention, Preparedness, Response, and Recovery (PPRR).Adapting the Australian PPRR Model to Daily Operations Translating the PPRR model into daily operations ensures practical protection without administrative burden: Prevention: Actions that stop disruptions before they start, like updating server firewalls and servicing backup generators. Preparedness: Developing step-by-step procedures, backing … [Read more...] about Small Business Continuity Planning: Practical 2026 Guide
Insurance for Australian Online Retailers: 2026 Guide
While you're busy managing a slice of the record A$82.6 billion online spend in Australia, one report of cybercrime hits every six minutes. Finding the right insurance for online retailers in Australia isn't just a legal checkbox anymore; it's about making sure your hard work doesn't vanish overnight. We understand the stress of navigating complex regulations, especially when a single faulty product or a data breach could lead to expensive lawsuits that threaten everything you've built.You deserve more than a generic, "tick and flick" automated policy that might fail you when it matters most. We'll show you exactly which covers are essential for your e-commerce business to protect your assets and reputation. From understanding the "deemed manufacturer" trap to securing your digital storefront, this guide provides the clarity you need to stay compliant and confident in your coverage. Key Takeaways Understand how Australian Consumer Law impacts your e-commerce store and why the "deemed manufacturer" rule makes product liability non-negotiable for importers. Learn how to build a robust shield with specialised insurance for online retailers in Australia, covering everything from public liability to protecting your digital assets. Discover why cyber insurance has become a mandatory lifeline in 2026 to safeguard customer data and manage your legal reporting obligations after a breach. Find out why generic automated quotes often leave dangerous gaps in your cover and how a consultative broker ensures your policy is tailored to actually pay out. Table of Contents Understanding the Core Risks for Online Retailers in Australia Essential Coverage Checklist for Your E-commerce Business Why a Consultative Broker Beats an Automated Quote Understanding the Core Risks for Online Retailers in Australia Running an e-commerce store feels like a digital venture, but the risks are grounded in real-world consequences. Effective insurance for online retailers in Australia acts as a multi-layered shield, protecting you from both physical product failures and invisible digital threats. Many owners believe that because they don't have a physical shopfront, their public liability risk is non-existent. They're wrong. If a delivery driver trips while collecting stock from your home office, or a customer is injured by a faulty item you've sold, the financial fallout is your responsibility.To better understand how these different layers of protection work together, watch this practical breakdown of foundational business cover: Under the Australian Consumer Law (ACL), retailers face strict statutory obligations that cannot be ignored. If you import products from overseas and the original maker doesn't have an Australian office, you're legally "deemed the manufacturer" under Section 7 of the ACL. This means you're directly liable for any personal injury or property damage those products cause. Since June 2025, the introduction of a statutory tort for serious invasions … [Read more...] about Insurance for Australian Online Retailers: 2026 Guide
How an Insurance Broker Helps with Claims: A Guide to Navigating Disputes
Imagine the gut-wrenching moment you open an email to find your major claim has been rejected based on a single, obscure clause. You've paid your premiums faithfully, but when disaster strikes, you're suddenly stuck in a queue for a faceless call centre. It's a deeply frustrating experience. This guide details how an insurance broker helps with claims by stepping in as your technical advocate to challenge unfair decisions. We'll show you how a professional's deep understanding of policy fine print and industry leverage can move your claim from a "no" to a successful payout. From managing complex paperwork to interpreting the latest AFCA dispute processes, we'll explain how to secure the protection you actually paid for. Key Takeaways Understand how a dedicated technical advocate manages your claim from initial lodgement through to settlement, providing a personalised alternative to faceless call centres. Learn the specific framework of how an insurance broker helps with claims by cross-referencing rejection letters against policy fine print to identify grounds for a formal dispute. Discover why moving beyond "tick and flick" automated quotes to a consultative risk review is the most effective way to prevent coverage gaps before a crisis occurs. Gain clarity on the Internal Dispute Resolution (IDR) process and how professional submissions can turn a complex claim rejection into a successful payout. Table of Contents The Broker as Your Advocate: Moving Beyond the Policy Document How to Dispute an Insurance Claim Decision: A Step-by-Step Framework Preventing the Dispute: The Value of Consultative Risk Management The Broker as Your Advocate: Moving Beyond the Policy Document Claims advocacy is the professional management of an insurance claim from the moment of lodgement through to the final settlement. Understanding how an insurance broker helps with claims starts with recognising their role as a technical advocate who ensures the insurer meets every contractual obligation. Unlike the often frustrating call centre experience found with direct insurers, a broker provides a single point of contact. This person knows your business intimately and understands the stress a pending claim creates. A key distinction is that an insurance broker has a strict legal duty to act in your best interests. This is a fundamental difference from an insurance agent, who is ultimately a representative of the insurance company itself.When you look at how an insurance broker helps with claims, you see a partnership built on protection. They move beyond the basic policy document to act as a shield against corporate bureaucracy. By investigating the specific circumstances of your loss, they provide the technical evidence needed to support your case. While an insurer focuses on the bottom line, an insurance broker focuses on the fine print to ensure your business remains resilient.Why Direct Claims Often Hit Roadblocks Many unrepresented claimants find their progress … [Read more...] about How an Insurance Broker Helps with Claims: A Guide to Navigating Disputes

Malicious Damage by Tenant Insurance Cover: A Landlord’s Guide to Real Protection
What if the damage your tenant left behind isn't considered 'malicious' by your insurer, leaving you to foot a five-figure repair bill alone? We understand the quiet anxiety that comes with handing over the keys to your most significant asset, as you've likely spent years building your property portfolio. It's a common frustration to feel that your malicious damage by tenant insurance cover might contain fine print that excludes the very events you fear most.We'll help you navigate the complex definitions that separate accidental mishaps from intentional harm, ensuring your investment is truly protected under Australian law. We'll examine the distinction between wear and tear and malicious acts, providing a streamlined path to recovery if things go wrong. You'll gain the clarity required to manage your property with professional confidence and genuine peace of mind. Key Takeaways Define the critical difference between intentional harm and accidental mishaps to ensure your policy responds exactly when you need it. Master the documentation process by using comprehensive Entry Condition Reports and date-stamped photos to build an undeniable case for your insurer. Learn why a personalised approach to malicious damage by tenant insurance cover provides more robust protection than the standard gaps found in generic, automated policies. Discover how a dedicated broker acts as your advocate during the claims process, moving you from a state of uncertainty to one of calm and security. Table of Contents Malicious Damage vs. Accidental Damage: Defining the Risk How to Organise Your Property for a Successful Claim Securing the Right Cover: Why Personalised Brokerage Matters Malicious Damage vs. Accidental Damage: Defining the Risk Understanding the nuances of your policy is the first step toward genuine protection. Malicious damage is an intentional act driven by a motive to cause harm or destruction. Think of a tenant punching holes in plasterboard during an argument. This differs sharply from accidental damage, which lacks intent, or the gradual wear and tear that occurs over years of occupancy.In an insurance context, malicious damage is defined as an intentional act committed with the specific motive to cause harm, destruction, or loss to a property.Landlords often fall into the deliberate act trap. This occurs when an insurer denies a claim because the tenant intended the action, but perhaps not the resulting damage. For example, if a tenant attempts a DIY repair that goes wrong, the act was deliberate, but the damage wasn't necessarily malicious. Without the right malicious damage by tenant insurance cover, you might find yourself responsible for the full cost of professional repairs.Why Policy Wording is Critical for Australian Landlords Every insurer in Australia interprets these terms differently, impacting your out-of-pocket expenses. Some policies carry a higher excess for claims involving malicious damage by tenant insurance cover, while … [Read more...] about Malicious Damage by Tenant Insurance Cover: A Landlord’s Guide to Real Protection
What Does Cyber Insurance Actually Cover? An Australian Small Business Guide (2026)
Did you know that the average cost of a data breach in Australia has climbed to A$4.26 million in 2026? For a local business owner, that figure isn't just a statistic; it's a potential door-closer. We understand that you've likely invested in firewalls and antivirus software, yet you still feel uneasy wondering what does cyber insurance actually cover when those defences are breached. It's natural to feel overwhelmed by the complexity of the 2026 Privacy Act reforms or to worry that hidden exclusions might leave you unprotected.We believe your insurance should be a stabilising force that offers genuine peace of mind. This guide moves beyond the jargon to explain how a policy functions as your pre-paid emergency response team. We'll clarify the distinction between first-party and third-party coverage, providing you with a clear roadmap for recovery and the confidence that your specific risks are managed. Key Takeaways Identify the vital distinction between first-party protections for your own digital assets and third-party coverage for legal liabilities following a breach. Uncover the specifics of what does cyber insurance actually cover, including your immediate access to a 24/7 crisis response team and forensic IT specialists. Learn how to navigate the significant recovery costs and stricter regulatory penalties introduced by the 2026 Privacy Act reforms. Understand why a manual risk assessment with a local expert is the only way to ensure your policy protects against complex fraud and social engineering. Table of Contents The Core Pillars: First-Party vs Third-Party Cyber Coverage The "Actually" Factor: Incident Response and Crisis Management Ensuring Your Policy Works: The Role of Personal Consultation The Core Pillars: First-Party vs Third-Party Cyber Coverage Understanding what does cyber insurance actually cover starts with dividing the policy into two essential pillars. First-party coverage acts as your internal safety net, funding the immediate repair of your own digital infrastructure and the recovery of compromised data. In contrast, third-party coverage steps in when your breach impacts others, providing a shield against legal claims from clients or partners whose private details were exposed.Integrating both pillars is vital for a robust business insurance strategy in 2026. While Cyber insurance has evolved significantly, its core purpose remains ensuring that a single digital mishap doesn't lead to total financial ruin. When we look at what does cyber insurance actually cover, we must consider both the immediate technical fix and the long-term liability that arises from a loss of trust.To better understand how these components work in practice, watch this helpful video: Business Interruption and Digital Asset Recovery When a breach occurs, the immediate financial bleed isn't just the repair bill; it's the silence of your cash register. Business Interruption coverage replaces lost income during the period your systems … [Read more...] about What Does Cyber Insurance Actually Cover? An Australian Small Business Guide (2026)
Australian Startup Risks: 2026 Resilience Guide
Did you know that a cybercrime is reported every six minutes in Australia, with the average incident costing a small business around $46,000? Identifying the common business risks for startups in Australia is the first step towards avoiding these costly pitfalls. While launching a new venture is exhilarating, the weight of regulatory requirements and the fear of a single legal slip-up can quickly turn that excitement into sleepless nights.This guide shows you how to build a protective shield around your venture through methodical risk management. We'll examine the latest 2026 privacy law updates, prioritise the threats you can't ignore, and help you find the peace of mind that comes from knowing your assets are secure. You'll gain a clear path forward, replacing uncertainty with the confidence of a seasoned founder. Key Takeaways Identify the operational "key person" vulnerabilities and market miscalculations that often derail new ventures before they find their footing in the local market. Navigate the complex landscape of common business risks for startups in Australia, including the latest 2026 regulatory shifts in data privacy and consumer law. Learn to build a robust risk register that categorises threats by impact, allowing you to prioritise your protective efforts where they matter most. Discover how to transition from generic, automated cover to a tailored insurance strategy that acts as a genuine safety net for your personal and business assets. Table of Contents Operational and Strategic Vulnerabilities in the Australian Startup Ecosystem Navigating Legal, Regulatory, and Digital Threats for New Ventures Crafting a Methodical Risk Mitigation and Insurance Strategy Operational and Strategic Vulnerabilities in the Australian Startup Ecosystem Identifying common business risks for startups in Australia requires looking past your pitch deck to the nuts and bolts of daily operations. Many founders focus entirely on growth while ignoring the structural cracks that can widen under pressure. It's vital to adopt a methodical approach to risk management to ensure your foundation is solid enough to support your long-term vision.Market miscalculation often stems from a lack of local insight. You might have a brilliant tech solution, but if it doesn't account for Australian consumer habits or the "tyranny of distance" in logistics, your costs will spiral. Shipping goods across our vast continent presents unique hurdles that international models often overlook, making domestic supply chain resilience a non-negotiable priority.To better understand the financial and operational realities of starting a business locally, watch this helpful video: The Risk of Underestimating Product-Market Fit A "global" product often hits a wall when it meets specific Australian standards or cultural nuances. We've seen countless ventures sink capital into services that the local market simply doesn't value. Iterative testing isn't just a buzzword; it's a … [Read more...] about Australian Startup Risks: 2026 Resilience Guide