
A detail that seems minor to you can affect an insurer’s decision. In Australia, understanding your duty of disclosure means taking reasonable care to share information you know, or could reasonably be expected to know, that may affect whether an insurer accepts your application or the terms it offers. The duty can also apply when you renew, extend, vary or reinstate a policy.It’s understandable to be unsure what you need to disclose, especially when rules differ between countries and the consequences can be serious. This article explains what disclosure means, what may happen if you breach the duty, and how insurance disclosure works in Australia and the United Kingdom. It also covers when the duty applies and what information may be relevant, so you can approach an insurance application with greater confidence. Key Takeaways In Australian family law proceedings, breaching disclosure obligations can affect evidence, costs and whether a case proceeds; serious non-compliance may also amount to contempt. Disclosure duties in family law can continue throughout a case, and financial disclosure covers direct and indirect circumstances, including certain property disposals. Insurance disclosure rules differ between Australia and the UK. In Australia, the duty can apply when you apply for, renew, extend, vary or reinstate a policy. If you’re considering cover for your business, MyGen Insurance Brokers can help you explore Business Insurance and related cover options that fit your risks. Table of Contents What are the consequences of breaching disclosure obligations? Legal advice about disclosure Insurance disclosure in Australia and the United Kingdom MyGen Insurance Brokers: Business Insurance What are the consequences of breaching disclosure obligations? A duty of disclosure requires you to provide relevant information. A duty of care concerns how you act, while a duty to notify means reporting a specified event or change. In Australian family law disputes, disclosure begins during pre-action procedures and continues until the case is finalised. Insurance disclosure periods differ and are explained in the insurance section.In family law proceedings, failing to disclose information, filing a false undertaking or breaching an undertaking can affect the case. The Court may refuse to admit information or documents, stay or dismiss all or part of the case, or make a costs order against a party. A party found guilty of contempt for withholding documents or breaching an undertaking may be fined or imprisoned.Non-compliance can also matter in property settlements. Sections 79(5) and 90SM(5) of the Family Law Act allow disclosure failures to be considered in property proceedings. The High Court of Australia has observed, at paragraph 24, that failure to disclose relevant evidence may sometimes require a guilty verdict to be quashed.A Melbourne man concealed assets valued at more than $4 million. After proceedings began in September 2017, the Federal … [Read more...] about Duty of disclosure: what it means and the consequences of breaching it
How to Read a PDS Document and Compare It With Your Schedule
A PDS can look complete and still be the wrong version for your policy. To learn how to read a PDS document and check whether it’s current, compare its issue or version details with the insurer’s latest PDS, then match it to the policy named on your schedule. The PDS sets out standard terms; your schedule shows the specific cover that applies to you.It’s easy to focus on the cover summary and miss an exclusion, waiting period or claims requirement in the detail. A careful review can help you identify what’s covered, where limits apply and whether the policy fits your needs.This guide walks you through the sections to review, how to compare them with your schedule and what to check when confirming the document’s currency. You’ll have a clearer way to assess the cover before relying on it. Key Takeaways Compare the PDS version and issue details with the insurer’s current document before relying on its terms. Trace the cover, exclusions and claims steps that matter to your circumstances, including any evidence the policy requires. Look closely at waiting periods and benefit limits, then compare the PDS’s standard terms with the specific details on your schedule. If you need help assessing business cover against your risks, MyGen Insurance Brokers can help you consider Business Insurance options. Table of Contents Reviewing policy coverage, exclusions and claims procedures Checking waiting periods and benefit limits Differences between a PDS and a policy schedule MyGen Insurance Brokers: Business Insurance Reviewing policy coverage, exclusions and claims procedures Start with the PDS contents and locate the cover, exclusions, claims and important information sections. Australian financial product disclosure requirements are set out in the Corporations Act 2001, according to the Australian Government Federal Register of Legislation. Read the PDS before deciding whether to buy a financial product. To compare PDS documents from different providers, line up the same details side by side: covered events, benefits, exclusions, limits, claims steps and charges. Compare equivalent cover, not just matching labels, because each financial product may define benefits differently. Note where wording could affect what a claim covers. Check each insured event against its exclusions and conditions. For example, if a business policy covers theft, look for exclusions or requirements relating to the property, location or circumstances. Record the benefit limit and any excess beside the relevant cover. A PDS explains standard terms; your schedule identifies your specific cover. Find fees and charges by searching the PDS for “fees”, “charges” and “premiums”, then compare the amount, frequency and what each charge applies to. For insurance in super, review the fund’s PDS for the cover, benefits, risks and fees, and identify how premiums relate to your super account. Read the warnings and important information, including eligibility rules, definitions and … [Read more...] about How to Read a PDS Document and Compare It With Your Schedule
Portable equipment insurance for tradies and their gear
A stolen tool kit can leave a tradie without essential gear and the ability to earn. To arrange portable equipment insurance for tradies, list the tools and equipment you want covered, set limits that reflect their value, and compare policy terms and exclusions. Depending on the policy, cover may include loss, theft or accidental damage while tools are in transit or at a worksite.Look beyond the headline cover: how tools are stored, how theft is defined and which claims are excluded can all affect whether a policy suits your work. This guide explains what portable equipment insurance may cover, how to arrange it and what to look for in the Product Disclosure Statement and Target Market Determination.You’ll also learn why wear and tear, electrical surge and mechanical breakdown may be excluded, so you can understand the limits before choosing cover for your gear. Key Takeaways Make an inventory of the tools and portable gear you rely on, then set cover limits with their replacement value in mind. Cover can depend on where equipment is kept and how it is secured, particularly when it’s left in a vehicle overnight. Read the policy wording for exclusions such as wear and tear, electrical or mechanical breakdown, and damage linked to unsecured storage. Compare the protection you need with the policy limits and exclusions so you can choose cover that fits the way you work. Table of Contents Cover for tools and portable business assets used by tradies What does portable equipment insurance cover? Wear and tear, electrical surge and breakdown exclusions MyGen Insurance Brokers: Business Insurance Cover for tools and portable business assets used by tradies Portable cover is designed for tools and equipment taken away from business premises, whether they’re travelling in a vehicle or moving between job sites. Compare policies based on covered events, security conditions and limits for individual items.Optional Tools Cover Some tradies’ insurance policies let you add optional cover for valuable tools of trade. Check whether the wording covers items you own or are responsible for, and whether employees’ or apprentices’ tools can be included. Compare each item limit with its replacement value, not just the overall limit. The Product Disclosure Statement and Target Market Determination explain the cover and its intended customers.Cover in Transit and Onsite Portable equipment cover may protect tools against loss, theft or accidental damage in transit or onsite, subject to the policy wording. Theft from a vehicle may require evidence of forcible entry, while unsecured tools may not be covered. Theft at a job site can also depend on storage and security conditions. Home contents insurance typically doesn’t extend to tools used for business, so don’t assume household cover protects them.Buying Cover and Getting a Certificate To compare policies in Australia, make a tool inventory, estimate replacement values, then compare covered events, exclusions, … [Read more...] about Portable equipment insurance for tradies and their gear
Glass Breakage Insurance for Shopfronts and What It Covers
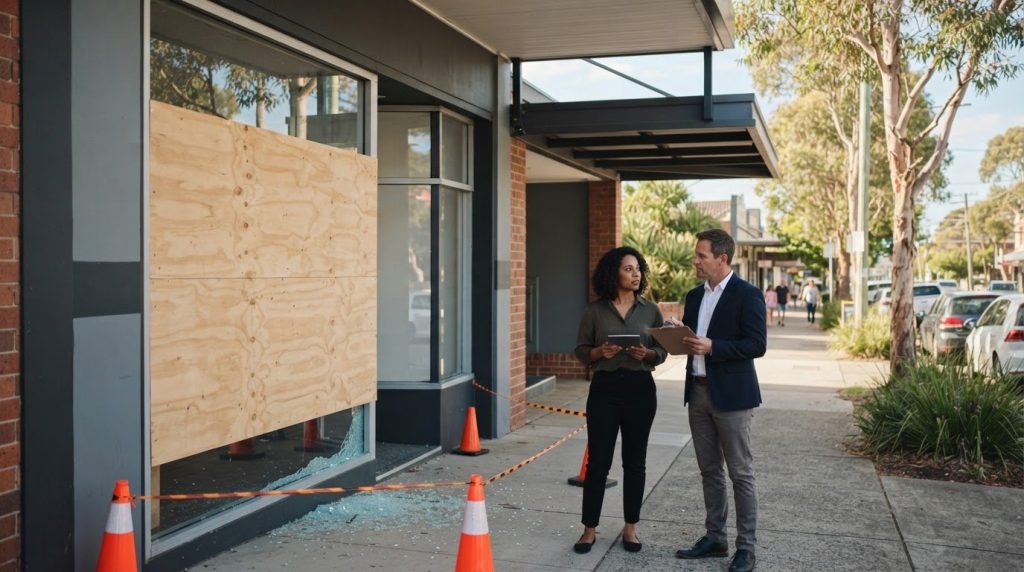
A broken shopfront may need urgent attention before you know whether insurance will cover the damage. Glass breakage insurance for shopfronts can cover the repair or replacement of insured glazing, including labour, but coverage depends on the policy, the cause of the breakage and any exclusions. A standard business property policy may limit glass cover or exclude it altogether.It’s understandable to focus first on the shattered pane and the risk to customers, staff and stock. Make the area safe, document the damage and notify your insurer promptly. Arrange urgent help if the opening is hazardous or unsecured.This article explains what plate glass insurance may cover, what to do after breakage and when emergency repairs are needed. It also explains how temporary boarding-up can make a site safer without completing the permanent replacement. Key Takeaways Check whether your policy specifically includes the damaged glass and what excess applies before deciding whether to claim. If life is in immediate danger, call Triple Zero (000) first, as advised by the Australian Communications and Media Authority. Urgent repair may be needed when glass is unstable, public access is at risk or the shop cannot be secured safely. Clarify whether emergency make-safe work includes permanent replacement, and keep repair details with your claim records. Table of Contents What is Plate Glass Insurance? What should I do if glass breaks at my business? When broken commercial glass needs emergency repair MyGen Insurance Brokers: Business Insurance What is Plate Glass Insurance? Shopfront Glass Claim Scenarios Plate glass insurance covers fixed glass when the policy includes the damaged item and the cause is covered. Possible claim scenarios include a vehicle striking an entry door, vandalism breaking a display window or hail damaging external glazing. For customer-facing venues—from local retailers to grooming establishments like Straight 8 Barbers—policies may also cover internal partitions, wall mirrors, signs, lettering or stock damaged by shards. Check which items are insured before an incident occurs.Exclusions and Insurance Limits Exclusions specify damage or circumstances a policy does not cover, while limits cap the amount payable. Scratches or chips that do not amount to breakage, glass defects, wear and tear, or breakage during installation or alteration may be excluded. Gradual deterioration or poor maintenance may also be treated differently from sudden accidental breakage. Check that the policy specifically lists or clearly includes the glass element.Replacement glazing may need to meet current safety requirements, rather than simply match the broken pane. This may apply to doors, low-level glazing and side panels near doors. Because the required replacement type can affect repair decisions, record the glass specifications.Premiums depend on factors such as the total glass value, glass type, location and claims history. Compare the … [Read more...] about Glass Breakage Insurance for Shopfronts and What It Covers
Management Consultant Insurance Cover and Claims
An allegation that your professional advice caused a loss can lead to a claim, even when there is no physical damage. In Australia, insurance for management consultants may include Professional Indemnity Insurance for legal costs and damages arising from claims of negligence. Public liability generally addresses specified claims involving personal injury or property damage. Cyber cover is not automatically included in every professional indemnity policy, so check the policy wording.Choosing cover is easier when you know what risks to consider, especially if your work spans strategic planning, project management or recruitment. This guide explains how the main covers may respond, how claims-made policies affect notification, and what to do if a claim arises. It also shows how your services, client interactions, business property and digital risks can shape your insurance needs. Key Takeaways Match cover to the advice and services you provide, and distinguish professional advice claims from injury or property damage claims. Understand how a claims-made policy’s notification period and retroactive date can affect whether a claim may be covered. When a claim arises, promptly follow the policy’s notification requirements and keep relevant records of the work and communications. Consider how client visits, business equipment, employees and digital operations may shape the insurance your consultancy needs. Table of Contents Making a claim What does management consultant insurance cover? Industry-specific insurance for management consultants MyGen Insurance Brokers: Business Insurance Making a claim A claim against a management consultant may concern professional advice, documents, public liability or other business circumstances. The policy wording explains which cover may respond and how to notify a claim.For context on structuring liability cover and handling claims, watch this video: Defamation and intellectual property claims A client might allege that a consultant’s report harmed their reputation, raising a defamation claim. An allegation of unauthorised use of protected material or branding may involve intellectual property liability. Neither is automatically covered. Check the policy schedule and wording for relevant cover, exclusions and notification conditions. A broker can explain how the policy treats these allegations.Claims-made policies and cover periods A claims-made policy responds to claims first made against a business during the policy period. It may cover incidents occurring after the policy’s retroactive date, subject to its terms. The alleged error and the claim may occur at different times. For management consultant Professional Indemnity Insurance, the limit in place when the claim is notified applies, not the limit held when the work was completed. The management consultant wording provides seven years of automatic run-off cover, subject to its terms and conditions. Review the retroactive date and run-off provisions … [Read more...] about Management Consultant Insurance Cover and Claims
Risk management for SMEs: assess risks and plan responses
A risk is not only a major disaster. It is anything uncertain that could affect your business’s operations, finances or reputation. Practical risk management advice for SMEs starts with identifying potential threats, assessing how likely they are and considering their consequences. Then decide whether to avoid, reduce, share or accept each risk.Risk planning can feel like another demand on a small team. A clear, practical process helps you focus on the issues that matter most and prepare for disruption. This article explains how to assess likelihood and impact, involve the right people and give your team clear actions. It also covers how suitable insurance can help limit the financial consequences of events that other controls cannot prevent. Key Takeaways Build a continuity plan around critical processes, key staff roles, emergency contacts and how your team will communicate during disruption. Compare each risk’s likelihood with its potential consequences, then direct attention to the exposures that could cause the greatest harm. Give named team members responsibility for recording risks, weighing financial and operational impacts, and keeping response actions accessible. Use suitable insurance as one part of your response plan to help reduce the financial impact of covered events; it won’t prevent the risks themselves. Table of Contents 1. How can insurance help small entrepreneurs or SMEs, or how it relates to risk management? 2. Risk likelihood and consequence assessment 3. Risk management teams and plans MyGen Insurance Brokers: Business Insurance 1. How can insurance help small entrepreneurs or SMEs, or how it relates to risk management? Insurance is one part of risk management: it can transfer some financial consequences of covered events, but it won’t prevent fires, theft, cyber incidents or injuries. Start by identifying threats across daily operations, staff, customers, suppliers, property, vehicles and data. Then decide which risks need prevention, a continuity strategy, insurance or acceptance.A business continuity plan sets out how owners and staff will respond to unexpected events. Record critical processes, key staff roles, emergency contacts, communication steps and relocation arrangements. Include data backups and alternative suppliers if disruption could stop essential work.For a practical overview, watch Strategies for Managing Risk as an SME from ConsumerCentriX: Disaster recovery means restoring systems, records and operations after an incident. Name who activates the plan, where vital documents are stored and how staff can work if the usual site or systems are unavailable. Test the steps and update them as the business changes.SME business insurance can help limit financial losses from insured events. Coverage varies by policy: property cover may protect buildings, contents, stock and equipment, while business interruption cover may help with ongoing fixed costs after insured property damage. Dedicated providers … [Read more...] about Risk management for SMEs: assess risks and plan responses
Avoiding underinsurance for business assets as costs change
Business growth can leave your assets underinsured, even if your policy hasn’t changed. Underinsurance means your cover is insufficient for the value of your business assets. The sum insured is the maximum your insurer will pay for a claim. Avoiding underinsurance for your business assets starts with keeping insured values aligned with what you own and what it would cost to replace or rebuild today.Cover can fall behind as you buy equipment, increase stock, expand or face rising rebuilding costs. A figure that once seemed reasonable may no longer reflect the business you run today.This article explains how to review your sums insured after growth or purchases, estimate current replacement and rebuilding costs, and spot changes that can quietly create a shortfall. A clear review process helps you make informed decisions about protecting the assets your business relies on. Key Takeaways Review insured values after buying equipment, increasing stock, moving premises or changing how your business operates. Base building cover on the cost to rebuild, and contents cover on the cost to replace items new, rather than relying on past values. Check policy limits, exclusions and excesses alongside your asset values so you understand how they may affect a claim. A structured review of your business risks and cover can help identify where tailored Business Insurance may fit. Table of Contents 1. Updating sums insured after business growth or purchases 2. Building reconstruction and contents replacement costs 3. Why business assets become underinsured MyGen Insurance Brokers: Business Insurance 1. Updating sums insured after business growth or purchases A sum insured is the maximum an insurer will pay for a claim. If you buy machinery, increase stock, renovate or expand, compare the values listed in your policy with what the business owns now. New purchases or higher stock levels can create a gap if insured values stay the same. To avoid underinsurance for your business assets, update your asset schedule and notify your insurer when purchases or operations change.Review your cover at least once a year, before renewal, and after a major business change. Check policy limits, exclusions and excesses, and look for an underinsurance clause that could reduce a payout if your assets aren’t insured for their full value. Compare the cover basis and limits with each asset’s current replacement value and rebuilding cost. A broker can assess how equipment purchases, contracts, relocations and operational changes affect your risks and cover.Keep a clear record of your assets for any future claim. Store purchase invoices, asset registers, serial numbers and photographs together, and understand the evidence requirements and lodgement timeframes in your policy. These records can help substantiate ownership and value when you make a claim.Insurance gaps affect businesses and economies alike. The Insurance Council of Australia reported that 26% of Australian SMEs and … [Read more...] about Avoiding underinsurance for business assets as costs change
Trailer and Equipment Insurance: A Business Guide
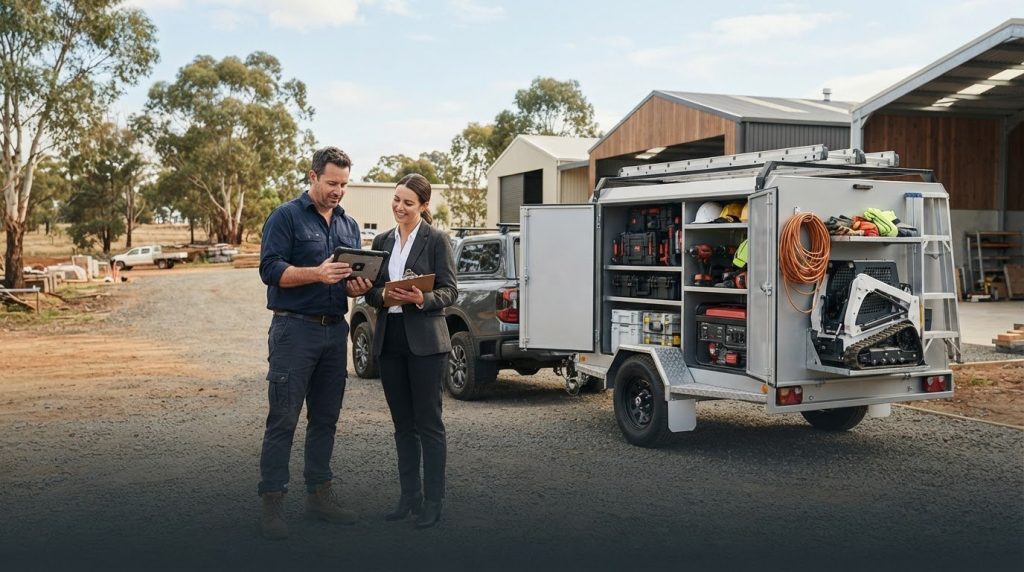
What if your trailer is insured, but the tools it carries are treated differently? It’s understandable to wonder whether both belong under one policy or whether your business insurance reflects how each asset is used, stored and moved. Insurance for trailers and equipment needs a closer look than the policy label alone can provide.This guide explains the insurance categories that may be relevant, including business property, tools of trade and equipment, theft, commercial motor and marine transit cover. It also outlines the information to gather for a useful review, so you can describe your trailer, equipment and day-to-day work clearly.MyGen Insurance Brokers provides personalised business insurance reviews, drawing on 20+ years of industry experience and supporting clients through the policy period and claims process. All services are subject to the company’s terms and conditions, viewable on this site. Key Takeaways Insurance for trailers and equipment is a risk-review question, not one universal policy label. Consider the trailer, its contents and other business assets separately. Build a clearer picture of your risks by recording what you own, how each asset is used, and where it is stored or moved. Review relevant options, such as business property, tools and equipment, theft, commercial motor and marine transit cover, alongside the policy wording. MyGen can review your business risks and potential blind spots to help shape a considered insurance package. Table of Contents Insurance for trailers and equipment: understand the business risks How to review insurance for trailers and equipment before choosing cover Arrange a considered business insurance review for trailers and equipment Insurance for trailers and equipment: understand the business risks It can be difficult to know where a work trailer ends and its contents begin in an insurance review. The trailer, tools carried inside it, equipment used on site and goods being transported each raise different questions. A policy label alone does not explain how each item or business activity is treated.Think of insurance for trailers and equipment as a risk-review question, rather than one universal policy or guaranteed package. How cover applies depends on the policy wording, the property insured and the use described to the insurer. Understanding insurance fundamentals can help you make sense of how policies set out their terms.A video example of trailer insurance in practice: How do trailer cover and tools of trade fit into business insurance? Start by separating the assets and the risks. The trailer is distinct from the tools and equipment it carries. Goods being transported are another consideration, while the trailer’s business use may raise motor-related questions. Assets may also move between locations or be used at worksites, so describe those activities clearly as part of a review.Relevant categories to consider include General Property (Tools of Trade & Equipment), … [Read more...] about Trailer and Equipment Insurance: A Business Guide